by jqm | Nov 15, 2026 | Insurance
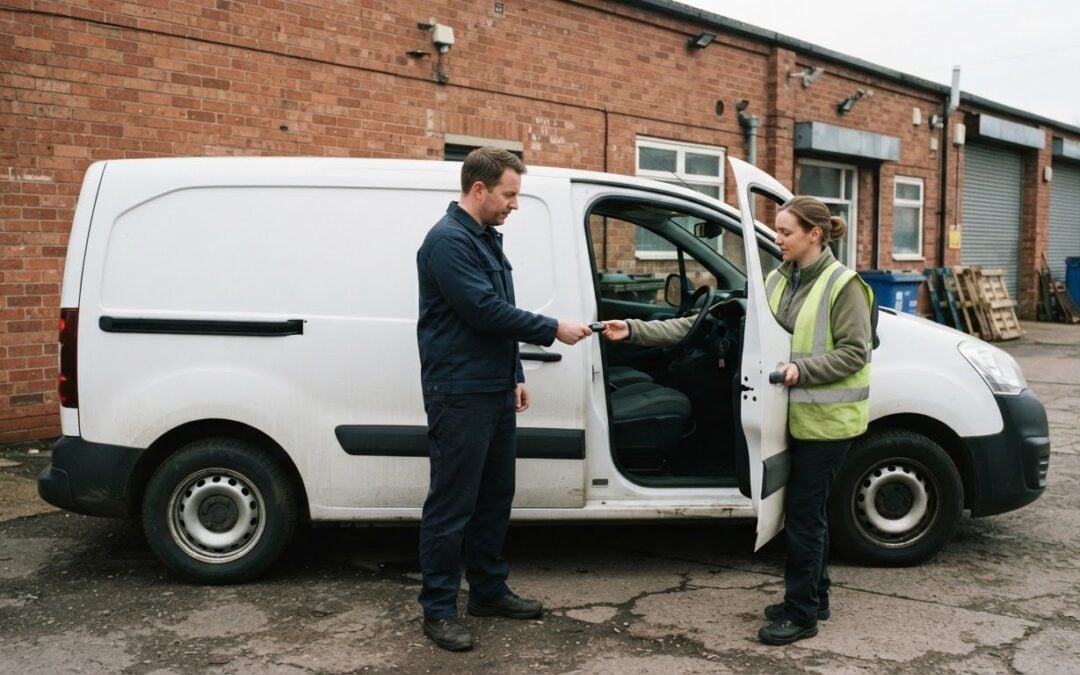
An any-driver commercial vehicle insurance policy can let eligible staff drive a business vehicle without naming each driver individually. It doesn’t automatically mean every employee is covered: eligibility and permitted use depend on the policy, and any-driver cover usually applies to drivers over 25, although insurer rules vary. In the United Kingdom, van insurance is a legal requirement under the Road Traffic Act for owning or driving a van or pickup, unless the vehicle is declared off-road and kept on private property.
It’s understandable to want cover that keeps pace when staff or vehicles change. This guide explains what business vehicle insurance can cover and when your business may need it. It also outlines how to update drivers or vehicles and what information helps when arranging cover for several vans. You’ll find practical points to consider when choosing cover, so you can make a decision based on how your vehicles are used and who needs to drive them.
Key Takeaways
- Understand how comprehensive and third-party, fire and theft cover differ, and consider which protection fits your business vehicles.
- Keep your policy details aligned with your fleet by arranging updates when drivers or vehicles change.
- Identify when business use means a vehicle needs appropriate insurance, including when staff drive it for work.
- Prepare useful vehicle and driver details to make a multi-van quote more straightforward, and understand who may qualify to drive.
Comprehensive cover and third-party, fire and theft
Commercial van insurance commonly offers comprehensive or third-party, fire and theft cover. Comprehensive cover can protect against damage to your vehicle, as well as damage or injury you cause to others while driving. For example, it may cover damage to your van in a collision, subject to the policy excess and terms. Third-party, fire and theft cover protects against liability to others and damage to your van caused by fire or theft, but not accidental damage to your own van.
The cover level describes the type of loss insured, not who is allowed to drive. An any-driver commercial vehicle insurance policy still has driver eligibility conditions. Check the policy wording and schedule for the vehicles, business use, exclusions and excesses. Comprehensive cover is not automatically broader in every respect, so compare the protections stated in the policy rather than relying on the label alone.
- Personal belongings: Cover for items kept in a van may be limited, excluded or offered as an extra. Tools and business equipment may need separate protection. For example, a laptop left in the cab may be treated differently from goods carried for work.
- Personal accident: This can provide a benefit after specified injuries to an insured person. Check who qualifies, which injuries are covered and any limits in the policy documents.
- Breakdown cover: This is an optional extra on some insurance policies. It can provide roadside assistance or recovery, depending on the selected terms.
- Motor legal cover: This optional cover can help with certain legal costs after an insured motoring incident. The policy sets the circumstances and limits.
For a business van, choose a cover level that reflects the financial risks you need to manage. Comprehensive cover may suit a business that wants protection for damage to its own vehicle, while third-party, fire and theft may suit a different risk preference. Review belongings, personal accident, breakdown and legal cover separately, and confirm each protection you select appears in the policy documents.
How do I add or remove a driver or change my vehicle?
Keep your cover aligned with the people and vans used by your business. Give the insurer accurate information whenever a driver joins or leaves, or a vehicle changes.
Adding Drivers and Vehicles
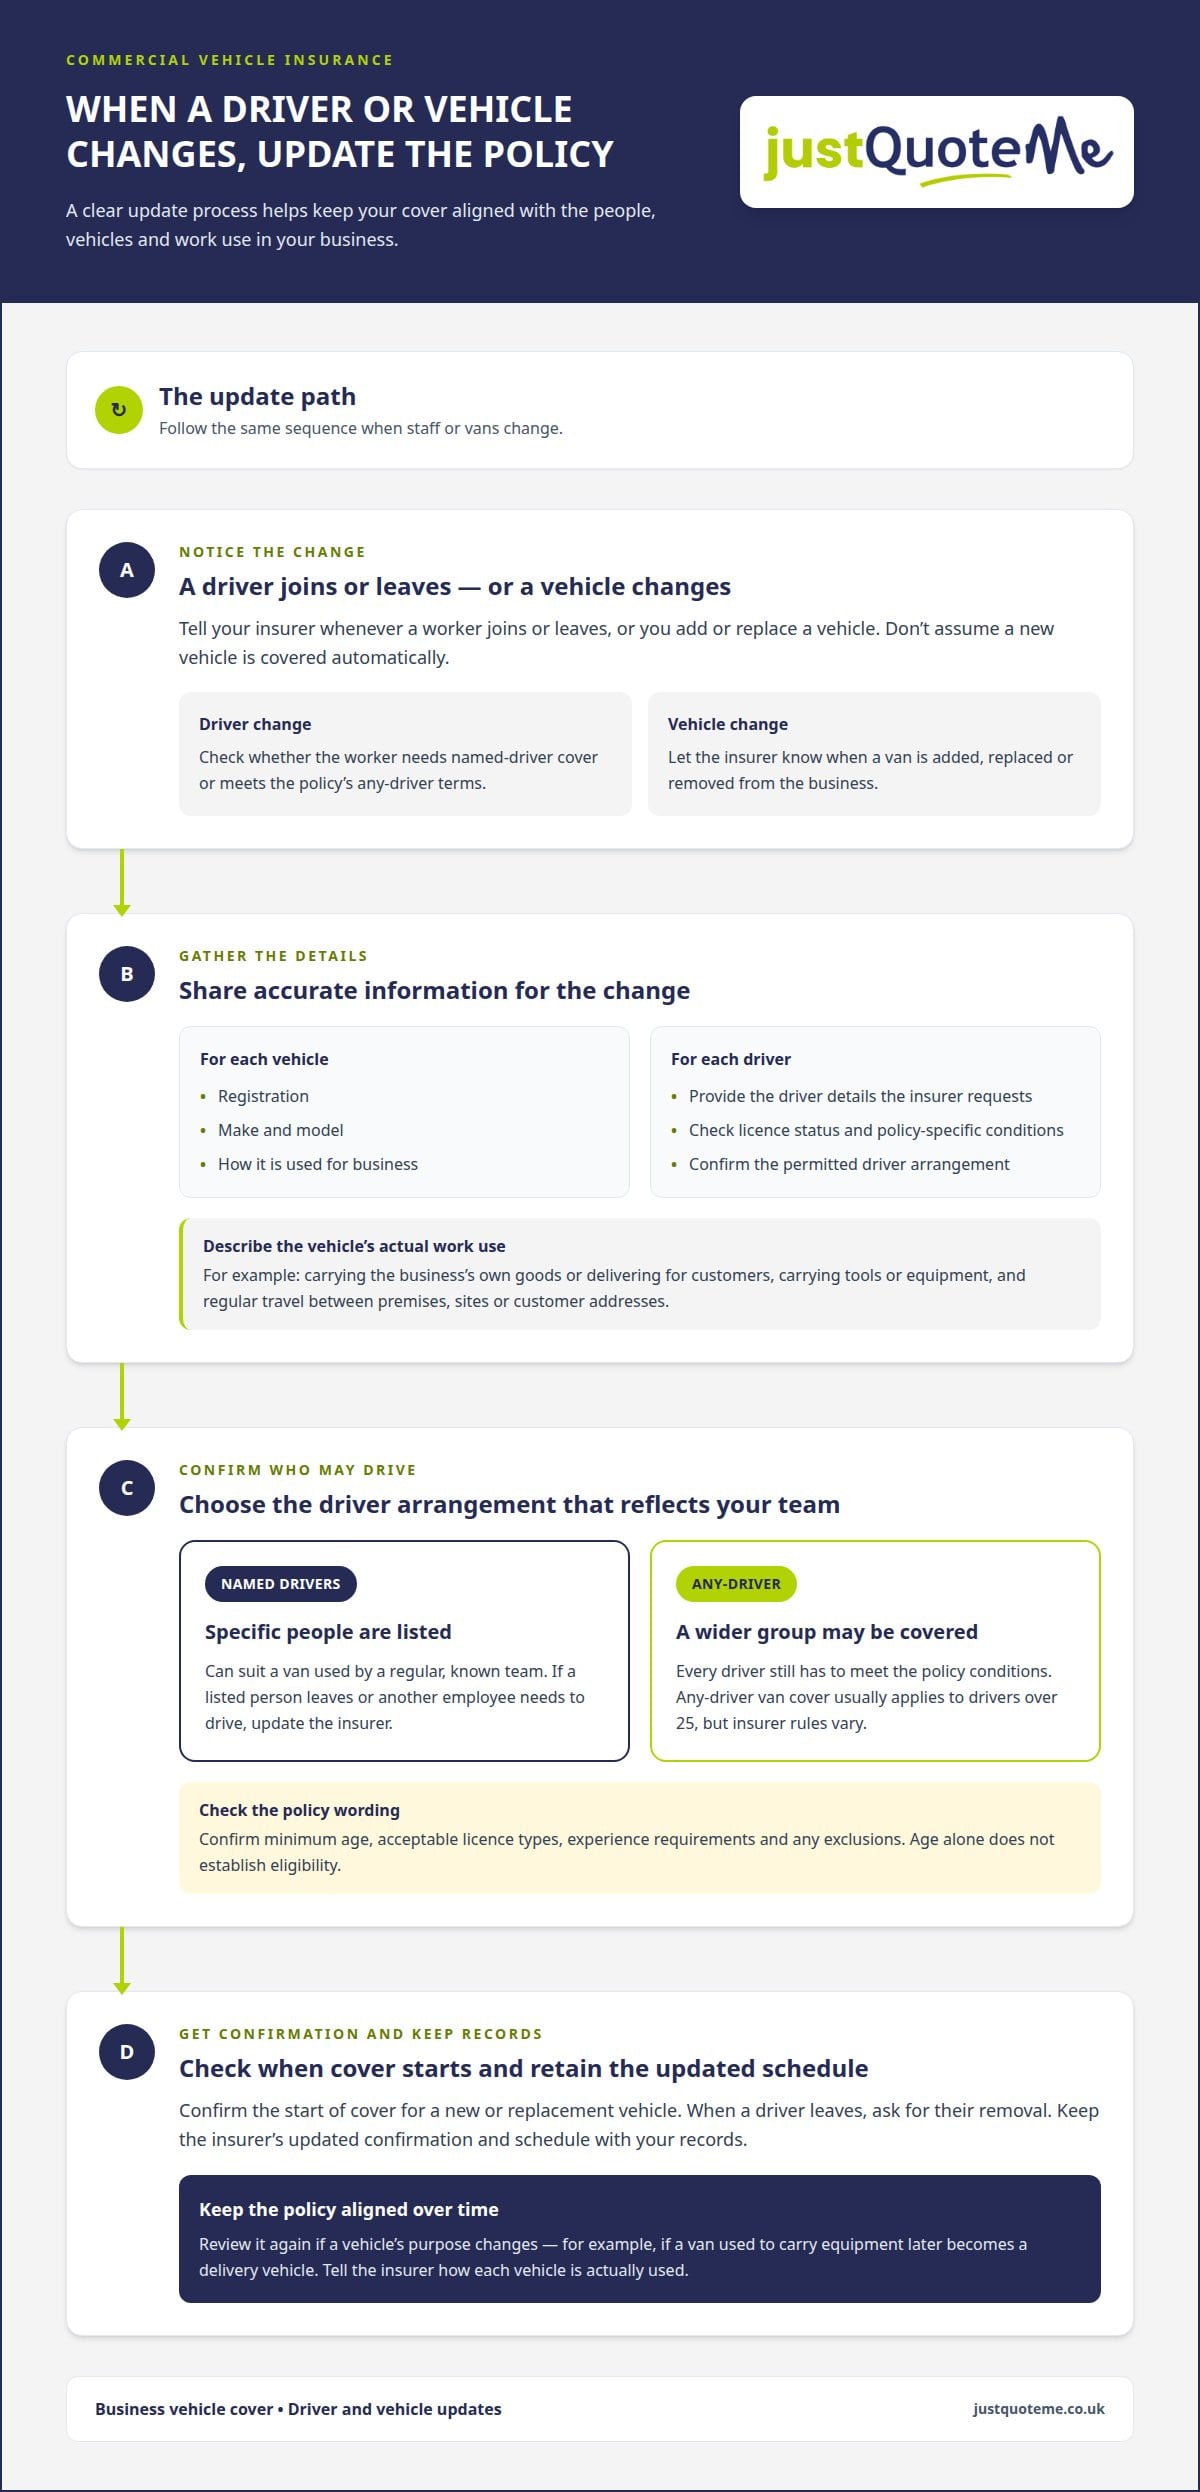
For a multi-van policy, tell the insurer when you add or replace a vehicle rather than assuming it is covered automatically. Provide its registration, make, model and business use, then confirm when cover starts. When a worker joins, share the requested driver details and establish whether they need named-driver cover or meet the policy’s any-driver terms. When an employee leaves, ask for their removal and keep the updated schedule with your records. Eligibility for multi-van cover depends on details such as the vehicles, their use and your business circumstances.
Named Driver Choices
Named-driver cover lists the specific people permitted to drive. Any-driver cover allows a wider group, but only when each person meets the policy conditions. A named arrangement can suit a van used by a regular, known team, while broader cover may fit changing staffing needs. For example, if two employees use a van, naming them makes it clear who is permitted to drive. Update the insurer when either person leaves or another employee needs to drive, so the information remains current for any claim.
Driver Eligibility and Restrictions
Any-driver van insurance in the UK usually covers drivers over the age of 25, although insurer rules vary. Age alone does not establish eligibility: licence status and any policy-specific conditions also matter. Confirm the minimum age, acceptable licence types and any experience requirements shown in the policy documents. Check exclusions for vehicle use, driver eligibility and business activities, too. A claim may be affected if the driver or use falls outside the agreed terms, so make those conditions clear to staff before they take a van.
When a driver or vehicle changes, give the insurer the details and keep its updated confirmation. For help considering cover across your business, explore business insurance options.
When business vehicle insurance is needed
Business vehicle insurance is relevant when a vehicle is used for work, not simply because a business owns it. A van carrying tools to a building site, delivering goods to customers or travelling between work locations has a business use to describe. Tell the insurer how each vehicle is used so the policy reflects its actual role.
In the United Kingdom, van insurance is a legal requirement under the Road Traffic Act for owning or driving a van or pickup, unless the vehicle is declared off-road and kept on private property. A vehicle used for business on public roads still needs appropriate cover. The policy should reflect its work purposes and permitted drivers.
Start by listing each vehicle’s regular work use. A tradesperson’s van, for example, may carry equipment between jobs, while a catering business may use a van to transport supplies. These activities can affect which cover is suitable, so describe them accurately when arranging or renewing insurance.
- Deliveries: State whether staff carry the business’s own goods or deliver items for customers.
- Tools and equipment: Explain whether workers keep tools in the van, as vehicle insurance may not cover the contents.
- Work locations: Describe regular travel between premises, sites or customer addresses.
- Staff driving: Identify whether one employee, named drivers or a wider group uses each vehicle.
Review the policy whenever a vehicle’s purpose changes. A van used only to carry equipment may later become a delivery vehicle. Tell the insurer about the change and confirm the policy schedule reflects the new use before relying on the van for work. Do the same if a vehicle used personally starts making regular business journeys.
Consider business use alongside vehicle type, driver arrangements and the items carried. A clear account of these details helps match cover to the work being done. Keep policy documents accessible to staff so they can check which vehicle they may drive and for what purposes.
Who is eligible to drive under any driver commercial vehicle insurance?
“Any driver” does not mean every person can drive without conditions. In the UK, this cover usually applies to drivers over the age of 25, although insurer rules vary. The policy wording sets the actual eligibility criteria, so the phrase alone cannot establish whether a particular employee is covered.
Use the policy schedule to identify restrictions that apply to your business vehicles. Check for age limits, licence conditions, permitted vehicle use and other driver requirements. A policy may allow eligible staff to share a van but still restrict who qualifies. Check each person against the terms before they take the keys.
A straightforward process helps keep driver eligibility clear:
- Read the driver conditions: Note the minimum age and licence terms shown in the policy documents.
- Match each driver: Compare the employee’s details with those conditions before authorising them to drive.
- Explain restrictions: Tell staff which vehicles and business purposes the policy allows them to use.
- Review changes: Revisit eligibility when your workforce, vehicles or business use changes, and request a policy update if needed.
For example, if an employee is below the policy’s stated age limit, don’t assume broad any-driver wording overrides that restriction. The same applies if a driver’s licence details or vehicle use do not meet the stated terms. A claim could be affected if the driver falls outside the cover conditions, so make the requirements clear before assigning a van.
Eligibility depends on the exact wording, not simply the number of staff who may drive. Keep the current schedule available to whoever assigns vehicles, and make sure each driver understands the applicable conditions. If your team or van arrangements change, review your business insurance options to consider suitable cover.
Just Quote Me: Commercial Property Insurance
Just Quote Me can help you consider Commercial Property Insurance alongside the risks created by your business vehicles. Vehicle and premises cover address different needs: insurance for your workplace does not replace cover for vans used on the road. If your business owns or occupies premises, reviewing property protection can be a useful part of arranging cover for your operations.
Just Quote Me can also discuss how your business needs relate to Public Liability Insurance, Employers Liability Insurance or Professional Indemnity Insurance. The right combination depends on your activities, people and property, so consider which risks each policy needs to address.
Contact Just Quote Me to discuss your business insurance needs.
Make your next cover review purposeful
Use your next renewal or staffing change to decide how vehicle access should be managed. If an any-driver commercial vehicle insurance arrangement seems suitable, set out who needs to drive, which vehicles they use and what work those vehicles support. A clear picture of daily operations gives the discussion a practical starting point, rather than treating driver access as an isolated decision. Assign someone to keep the details current as your business changes.
Consider the wider risks around your business, too. Just Quote Me offers Public Liability Insurance, Employers Liability Insurance and Professional Indemnity Insurance, each addressing different business exposures from vehicle cover. The right combination depends on your activities and circumstances, so focus on protection relevant to your work.
A considered approach helps you make cover decisions that fit how the business operates today and can be revisited as it changes. Contact Just Quote Me about cover to discuss a suitable next step and move forward with confidence.
Frequently Asked Questions
What is business vehicle insurance?
Business vehicle insurance covers vehicles used for work, with protection defined by the policy. An any-driver commercial vehicle insurance policy may suit a business where eligible staff share work vehicles, while other policies name specific drivers. For example, a van carrying stock between a warehouse and customers has a different work purpose from a car used occasionally for meetings.
How can I get cheaper van insurance?
To manage costs, provide accurate details about the van, its use and its regular drivers. Avoid paying for optional protections the business doesn’t need, but don’t remove cover that addresses a real risk. For example, if a van carries valuable tools, consider whether the contents need separate protection. A clear description helps insurers assess the actual risk rather than make assumptions.
What is the maximum weight of a van that you will insure?
There isn’t one maximum weight that applies to every commercial vehicle policy. The vehicle’s gross vehicle weight, type and business use affect which policy terms are suitable. Weight also matters when assessing whether any-driver commercial vehicle insurance fits the vehicle and its use. Provide the van’s make, model and gross vehicle weight so the cover can be considered against its specifications.
What does any driver commercial vehicle insurance cover in the UK?
Any-driver commercial vehicle insurance provides the cover described in its policy for eligible drivers using insured business vehicles. The protection may include third-party liability and, depending on the chosen level, damage to the insured vehicle. The schedule and wording set the actual scope, including permitted use, exclusions and driver conditions. Check those terms for each vehicle rather than relying on the policy label.
What factors affect the price of any driver commercial vehicle insurance?
The premium reflects the risk presented by the vehicles and how your business uses them. Relevant details can include vehicle type and value, annual mileage, where vehicles are kept, work purposes, driver eligibility and claims history. Delivery work, for example, may involve different journeys from carrying equipment between fixed work sites. Accurate details help insurers assess the specific risk.
What vehicle types and business uses can any driver commercial insurance cover?
Commercial vehicle policies can cover vehicles such as vans and pickups, subject to policy terms and vehicle details. Business uses might include delivering goods, carrying tools or travelling between work locations. Describe what each vehicle carries and the journeys it makes. This helps distinguish a tradesperson’s equipment van from a vehicle used mainly for customer deliveries.
Get Your Free Business Insurance Quote now
Request a Call back for free Expert advice
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Nov 14, 2026 | Insurance
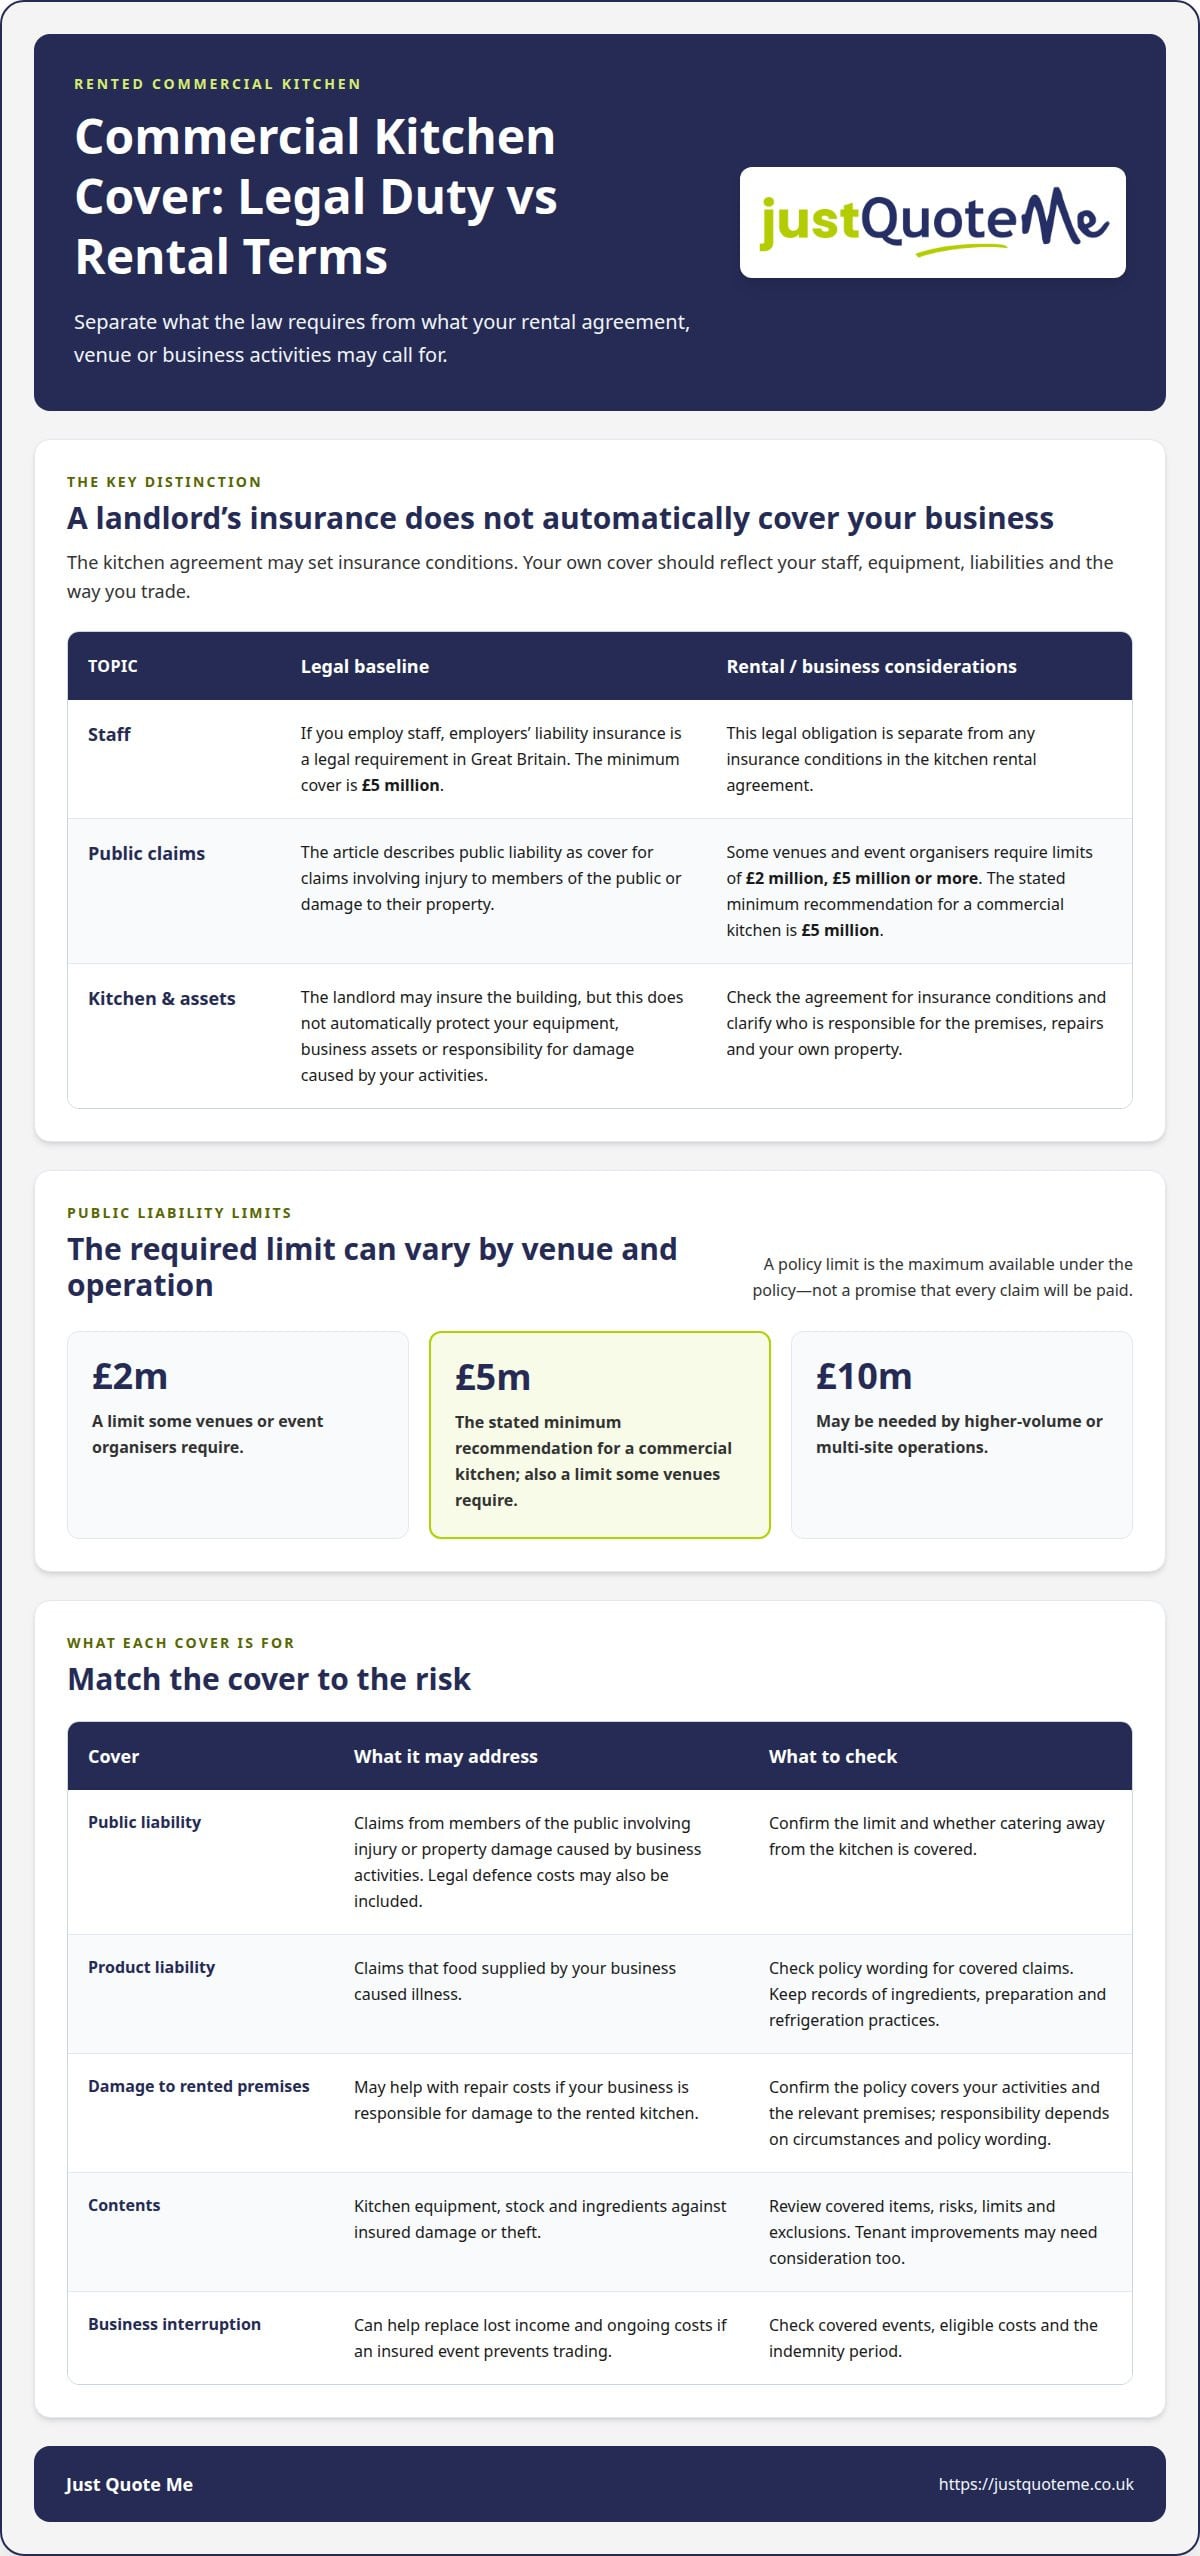
Renting a commercial kitchen doesn’t automatically mean the landlord’s insurance covers your business. Commercial kitchen insurance requirements when renting often come from your kitchen agreement, while employers’ liability insurance is a legal requirement if you employ staff. In Great Britain, the minimum cover is £5 million, according to UK Legislation.
It’s reasonable to want clarity about who pays if a customer is injured, food you supply causes illness or your work damages rented premises. Public and product liability can address claims involving the public and food you supply. Cover for damage to rented premises may help with repair costs if your business is responsible.
This guide explains the main types of cover, what rental agreements may require and how to consider protection for staff, customers, equipment and the kitchen itself. The right cover depends on how you operate, including whether you cater off-site or employ people.
Key Takeaways
- Separate legal obligations from insurance conditions set by the kitchen rental agreement.
- Understand how public liability and product liability relate to different claims involving customers and food you supply.
- Consider who could be responsible for repair costs if your business damages the rented kitchen.
- Match your cover to your staffing, equipment and the way your food business operates.
What Is Commercial Kitchen Insurance?
Commercial kitchen insurance can combine cover for a food business’s liability, premises, equipment and trading risks. The right mix depends on the kitchen, your staff and whether you cater off-site.
In Great Britain, the Employers’ Liability (Compulsory Insurance) Act 1969 requires employers’ liability insurance with a minimum cover of £5 million, according to UK Legislation. In England, Natasha’s Law, the Food Information (Amendment) (England) Regulations 2019, came into force on 1 October 2021 and requires ingredient and allergen labelling on food pre-packed for direct sale, according to UK Legislation. The Regulatory Reform (Fire Safety) Order 2005 does not specifically mandate suppression systems, but requires the responsible person to assess fire risks and implement appropriate measures, according to UK Legislation.
Property and Business Interruption Cover
Property cover can protect insured business assets against covered damage. Business interruption cover can help replace lost income and ongoing costs if an insured event prevents you from trading. For example, a fire that closes a kitchen may interrupt catering while repairs take place. Check the policy wording for covered events, eligible costs and the indemnity period, as these details affect the protection.
Equipment, Inventory, and Tenant Improvements
Contents cover can protect kitchen equipment, stock and ingredients against insured damage or theft. Tenant improvements cover may apply to alterations made to rented premises. For instance, a renter may need cover for their own refrigeration equipment, ingredients and fitted improvements, rather than relying on the landlord’s building insurance. The policy wording sets out covered items and risks, including limits and exclusions.
Other business insurance options include public and product liability, as well as employers’ liability for staff. Professional indemnity, cyber and legal expenses cover may also suit particular operations. If you cater at festivals, markets or private functions, check whether liability cover applies away from your usual premises. Cover for food contamination and product recall also depends on the policy terms.
When comparing quotes, match the business activities, property, liability limits and excesses across each option. Then choose cover that reflects your operation. Comparing these details makes differences in protection clearer than looking at price alone.
Before buying, review exclusions relating to contamination, equipment, stock and off-site catering, as well as any conditions that affect claims. In the UK, employers’ liability is the relevant cover for employee injury or illness claims; workers’ compensation is not the usual UK term.
Public and product liability
Liability insurance addresses different types of claims, including customer injuries, property damage and illness linked to food supplied by a catering business. The right limits and scope matter because kitchen work can expose a business to several kinds of claim.
General Liability and Legal Defence
Public liability can cover claims from members of the public injured or whose property is damaged because of business activities. For example, a visitor could slip on a wet floor or have belongings damaged during a catering job. Cover may also include legal defence costs when a claim is made. Some venues and event organisers require limits of £2 million, £5 million or more before allowing a caterer to trade.
Foodborne Illness and Product Claims
Product liability can address claims that food supplied by a business caused illness. An outbreak of foodborne illness traced to a food business can lead to multiple claims. Food safety procedures matter, but the policy wording determines which claims are covered. Keep records of ingredients, preparation and refrigeration practices to help establish what happened if there is an incident.
For public liability, £5 million is the stated minimum recommendation for a commercial kitchen. Higher-volume or multi-site operations may need £10 million. A limit is the maximum available under the policy, not a guarantee that every claim will be paid. The activity covered also matters: check that catering away from the kitchen falls within the policy.
Legal expenses cover may help with costs arising from contract disputes, employment tribunals, licensing matters, Environmental Health issues, tax or VAT investigations, and debt recovery. Management liability is a separate consideration for decisions made by business leaders. Check the policy wording to see whether it is included.
Businesses serving alcohol should review liquor liability wording as well. Dram shop exposure may be excluded from standard general liability policies, requiring a separate policy or endorsement. To explore suitable business liability cover, consider how your menu, events and trading locations affect your risks.
Damage to rented premises
Damage to a rented kitchen can create costs for both tenant and landlord. For example, a cooking fire could damage extraction equipment, work surfaces or adjoining areas. The landlord may insure the building, but that policy does not automatically protect the tenant’s equipment or business assets, or cover its responsibility for damage caused by its activities.
Who owns the premises affects the property insurance you may need. A business that owns its premises may need cover for the building as well as its contents. In a rented kitchen, the landlord may insure the structure, while the tenant’s policy can cover its own equipment and liability for damage. Rental agreements may also set insurance conditions, so distinguish between the landlord’s and tenant’s responsibilities when arranging cover.
Responsibility depends on the circumstances and policy wording. If a fire starts during a tenant’s use of the kitchen and damages the facility, the tenant may face a claim for repair expenses. Public liability can respond to some third-party property damage claims, but the policy must cover the tenant’s activities and premises. Commercial property insurance relates to buildings and business property, with cover depending on the insured interest.
Food safety controls can also affect how insurers assess a catering risk. A documented HACCP plan may help some establishments qualify for reduced product liability premiums with specific insurers. HACCP records can show how a business manages hazards such as contamination, but they do not replace insurance. Product liability and property damage address different risks, even when both arise from one incident.
Allow for Insurance Premium Tax when considering a policy’s total cost. Insurance Premium Tax on most UK insurance policies is 12%, according to HM Revenue & Customs. The premium and tax are separate parts of the amount payable. For a tenant, the insured property, cooking activities, liability exposure and any landlord requirements all shape the cover arranged and its cost.
Insurance requirements when renting a commercial kitchen
Employers’ liability cover is an important consideration for catering businesses with staff. Public liability insurance is not a legal requirement for UK catering businesses, but venues, councils and event organisers may require it before you trade.
For renters, commercial kitchen insurance requirements often come from the rental agreement. A shared kitchen may set liability limits, ask to be named on the policy or require proof of cover before granting access. These are contractual conditions, not general legal rules. The agreement may also specify who is responsible for damage during cooking or after equipment breakdown.
For employers’ liability, the Employers’ Liability (Compulsory Insurance) Act 1969 requires minimum cover of £5 million in Great Britain, according to UK Legislation. This legal duty applies when you employ staff, including casual, seasonal or family workers. A business with no employees has a different position under this requirement.
Identify the activities your policy needs to cover. A restaurant tenant preparing meals for collection faces different risks from a caterer using the same kitchen for off-site events. Consider whether the policy covers work away from the shared kitchen and claims involving customers, food supplied, staff, equipment and stock. Commercial kitchen insurance requirements may also depend on the limits and conditions in your lease.
Rental arrangements can change as a food business grows. Hiring staff, adding event catering or storing more stock can change the risks that need protection. The kitchen owner may ask for updated evidence after a renewal or a change to the agreement. Keep the agreed activities and insurance conditions clear so your policy remains aligned with the rental terms.
Just Quote Me: Commercial Property Insurance
Just Quote Me can help you consider Commercial Property Insurance alongside the risks your rented kitchen agreement places on your business. This can be a useful next step when you want to understand how property cover fits with liability protection and your trading activities.
A tenant’s needs differ from an owner’s: the landlord may insure the building, while your business owns its equipment and stock and has its own responsibilities. Just Quote Me offers Public Liability Insurance and Employers Liability Insurance, as well as Professional Indemnity Insurance for relevant professional risks. The right combination depends on your business activities and the cover you need.
Request a Call back for free Expert advice.
Make your next kitchen decision with confidence
Your insurance should reflect how your food business operates. Changes to your menu, staffing, equipment or use of a rented kitchen can alter the risks your cover needs to address. Treat the commercial kitchen insurance requirements in your rental agreement as part of your wider business planning, rather than a one-off formality. Clear details about your activities and responsibilities help shape a more relevant discussion about protection.
Just Quote Me offers Public Liability Insurance, Employers Liability Insurance and Professional Indemnity Insurance. These options address different business risks, from claims involving members of the public to employee-related risks and professional advice or services. Consider which concerns matter most to your operation, then take the next step when you’re ready.
Request a Call back for free Expert advice to discuss your business insurance needs and move forward with a clearer plan.
Frequently Asked Questions
What insurance does a catering business need?
A catering business commonly needs public and product liability, as well as employers’ liability if it has staff. Property or contents cover may also suit a business that owns equipment, ingredients or other stock. For example, a mobile caterer working at events should consider whether its liability cover applies away from its usual kitchen. The right combination depends on the business’s activities and assets.
Is employers’ liability insurance mandatory for commercial kitchen staff, and what is the minimum cover?
Yes, employers’ liability insurance is required in Great Britain when a business employs staff. The Employers’ Liability (Compulsory Insurance) Act 1969 requires a minimum cover of £5 million, according to UK Legislation. This includes businesses employing casual, seasonal or family staff. A catering business should account for its actual working arrangements, rather than treating occasional shifts as automatically outside the requirement.
What public liability insurance cover should a UK commercial kitchen have?
£5 million is the stated minimum recommendation for a commercial kitchen, while higher-volume or multi-site operations may need £10 million. Some venues and event organisers set their own limits as a condition of trading. For instance, a caterer taking a booking at a venue should ensure the policy limit meets the venue’s stated requirement and covers the work being carried out there.
Do commercial kitchens need product liability insurance for food and drink sold?
Product liability is commonly relevant when a catering business supplies food or drink, as it can address claims that a product caused illness. A claim could involve a meal sold for collection or food served at an event. Consider the products you prepare and supply, including how you communicate ingredients and allergens, and check the policy terms for product-related claims.
What buildings, contents and equipment insurance is suitable for a commercial kitchen?
Cover should reflect who owns the building and which assets belong to your business. A property owner may need buildings cover, while a tenant may need protection for business-owned equipment, stock and contents. For example, a caterer using its own refrigeration unit in a shared kitchen should consider whether its policy covers that equipment. The rental agreement may also affect the tenant’s responsibilities.
Does commercial kitchen insurance cover fire, cooking oil fires and business interruption?
Fire damage and resulting business interruption may be covered if they arise from an insured event, but the policy wording sets the scope. A cooking oil fire could damage kitchen equipment and stop trading, but whether a claim is covered depends on the specific cause, safety conditions, exclusions and interruption terms. Review these provisions against your cooking methods and the costs that would continue during a closure.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Nov 13, 2026 | Insurance
The charity may hold the policy, but trustee indemnity insurance for charities can protect an individual trustee against covered claims. That distinction matters: trustees of unincorporated charities can be personally liable for the charity’s debts and obligations. A claim about a decision made in their role can also bring legal costs and financial exposure.
It is reasonable to expect insurance to protect the organisation first. Trustee indemnity cover focuses on claims against trustees for alleged wrongful acts, which may include breach of duty, misuse of funds, health and safety issues or unfair dismissal. The policy wording sets the scope, exclusions and limits, so cover depends on the specific policy.
This guide explains how the cover works, which claims it may respond to, and how a charity’s governing documents and Charity Commission rules relate to paying the premium. It also distinguishes trustee protection from other insurance a charity may need, helping you understand where each type of cover fits.
Key Takeaways
- Look beyond the policy name: wording, exclusions and limits determine which claims and legal costs may be covered.
- Separate governance-related claims from risks linked to the charity’s advice, services or other professional work.
- Review the charity’s governing document and make sure any premium paid from charity funds is reasonable.
- Understand which details shape a charity’s quote so you can assess whether the cover fits its activities and risks.
How does trustee indemnity insurance work?
Trustee indemnity insurance can protect individual trustees against claims connected with their charity role. The policy wording defines who is insured, which activities qualify and what claims are covered.
Who the Cover Can Protect
For an unincorporated charity, trustees can be personally liable for its debts and contractual obligations. Joint and several liability means one trustee could bear costs if the others cannot pay. Whether cover extends to a trustee’s role with another not-for-profit entity depends on the policy wording, including whether that role and organisation are among the insured activities. Premiums and limits depend on factors such as the charity’s activities, claims history, number of trustees and selected limit.
Covered Claims and Related Policies
Policies may respond to claims alleging misuse of charity funds, breach of authority, unfair dismissal or health and safety failures. They can also cover alleged wrongful acts, breach of trust or breach of duty, including negligence. The exclusions and limit in the wording define the protection. Claims outside those terms, or above the limit, are not covered. The UK Corporate Manslaughter and Homicide Act is dated 2007, according to the UK legislation register; insurance does not replace sound organisational risk management.
Directors’ and officers’ cover addresses claims involving organisational mismanagement and associated legal costs. Professional indemnity cover addresses risks from professional services, such as advice or training, rather than trustee governance decisions. A charity may need both where trustees govern an organisation that also provides advice. If it employs staff, the Health and Safety Executive says an organisation can be fined £1,000 for not displaying its employers’ liability certificate. Employers’ liability insurance is a separate cover.
Claims-Made Policies and Continuous Cover
Charity professional indemnity policies are written on a claims-made basis. For claims-made policies, the timing of the incident and the report can affect whether cover applies. A retroactive date may include historic work from an agreed date, provided cover remains continuous. For example, a gap between policies could affect cover for a later-reported claim about earlier advice. Check the policy dates and retroactive date when arranging or renewing cover.
Rules for Insuring Trustees
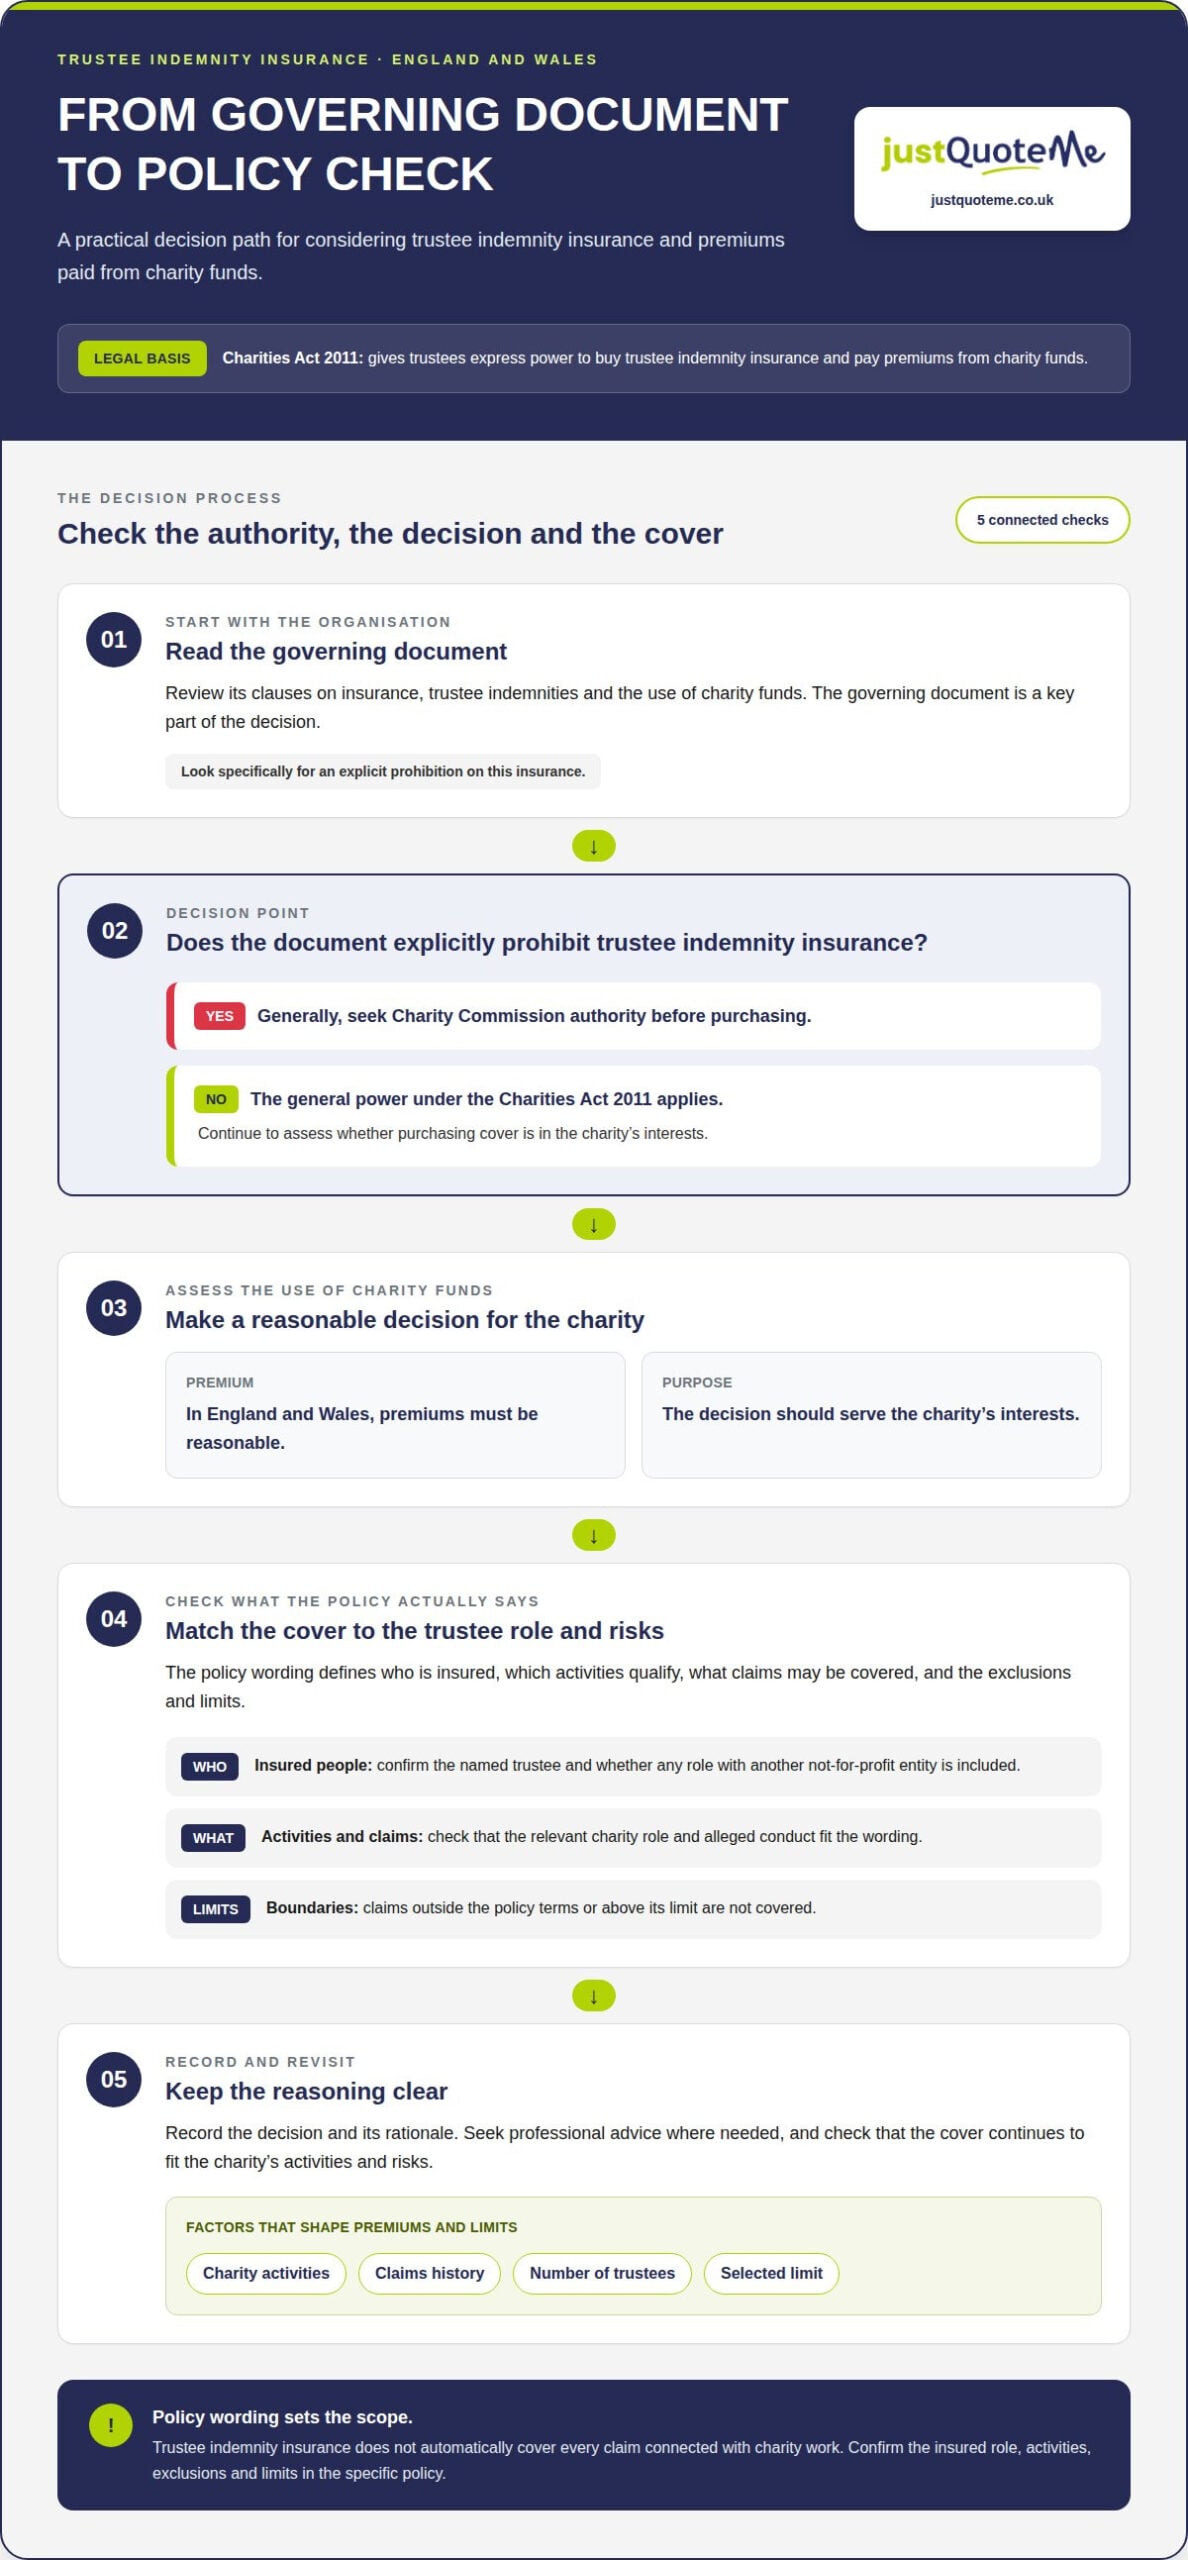
The Charities Act 2011 gives trustees express power to buy trustee indemnity insurance and pay premiums from charity funds. In England and Wales, premiums must be reasonable, and the decision should serve the charity’s interests. Review the governing document: if it explicitly prohibits this insurance, the charity generally needs Charity Commission authority to purchase it. Record the decision and its rationale, and seek professional advice where needed.
Claims for breach of trust, breach of duty, negligence and defamation
Claims against trustees can concern decisions, oversight or statements made while serving a charity. The allegation matters, as do the trustee’s role and the policy wording.
Breach, Negligence and Defamation Claims
A breach of trust claim may allege that a trustee mishandled assets or failed to protect the charity’s interests. A breach of duty or negligence claim may challenge how trustees made or carried out a decision. For example, after a building project runs over budget, a contractor might allege negligent oversight, while the charity faces a dispute about approval or payment. Cover depends on the alleged act, the insured role, and the policy’s exclusions and limits.
Defamation claims may arise from statements made about a person or organisation during charity work. A dispute about denying access could also allege that trustees acted unfairly by restricting someone’s use of a charity service or premises. These examples do not establish cover automatically: the wording must address the type of claim and circumstances. Professional indemnity is distinct, focusing on risks from professional advice or services rather than trustees’ governance decisions.
Claims and Investigations Against Trustees
Trustees may face pressure even before a formal claim. An investigation into a charity decision can require records, explanations and legal support, even if no one seeks compensation. The Charity Commission may be relevant where concerns involve charity governance, but an investigation does not itself prove that a trustee breached a duty. The policy should explain whether it responds to investigations, who can notify the insurer and how it handles legal costs.
When a complaint arrives, preserve relevant minutes, emails, contracts and project records, then notify the insurer using the process stated in the policy. Do not assume a claim is covered simply because it concerns charity work. Check whether the named trustee, activity and alleged conduct fit the policy. To distinguish governance liability from professional-service exposure, Request a Call back for free Expert advice.
What do Charity Commission rules and a charity’s governing document say about insuring trustees?
In England and Wales, the Charities Act 2011 gives charity trustees express power to buy trustee indemnity insurance and pay its premiums from charity funds. The power supports trustee protection, but it does not remove the need to make a careful decision for the charity. The Charity Commission is the regulator for charities in England and Wales, and the governing document remains a key part of that decision.
Start with the governing document’s clauses on insurance, trustee indemnities and use of charity funds. If it explicitly prohibits trustee indemnity insurance, a charity generally needs Charity Commission authority before purchasing it. If it contains no such prohibition, the general power under the 2011 Act applies. Read the exact wording, since a restriction on indemnifying trustees may differ from an express ban on buying insurance.
Any premium paid from charity funds in England and Wales must be reasonable. Trustees should weigh the charity’s interests, its activities, the risks they face and the protection the policy provides. For example, a charity handling substantial finances may assess governance risks differently from one with limited activities. The decision should reflect the organisation’s circumstances, not simply the availability of a policy.
A practical approval process can keep the reasoning clear:
- Review the governing document for insurance powers, restrictions and relevant indemnity clauses.
- Identify the charity’s needs and compare them with the proposed policy’s scope, exclusions and limit.
- Consider whether the premium is reasonable and whether charity funds can properly meet it.
- Record the decision, its rationale and any professional advice taken.
Professional advice can help when a clause is unclear or the policy’s protection is difficult to assess. Keep the governing document, policy wording and decision record together. This creates a clear record of how trustees considered the charity’s interests and the reasonableness of the spending, rather than treating insurance as an automatic renewal expense.
How much does trustee indemnity insurance cost for a UK charity?
There is no single price for every charity. A quote depends on the organisation’s activities, governance risks and the protection it needs. A charity providing advice may face different exposures from one focused on grant-making, while complex operations can affect the cover required. The cost reflects the charity’s risk profile, not simply its charitable status.
The price depends on the charity’s circumstances and is provided after a quote request. Activities, claims history, requested limit and policy terms can all shape the premium. The limit of indemnity is the maximum the insurer will pay under the policy. A higher limit changes the protection selected, so trustees should weigh it against the claims and legal costs the charity could face.
Before requesting a quote, prepare a clear picture of the charity’s work. Include its services, governance arrangements, financial responsibilities and any previous claims. For example, trustees overseeing a building project may want to explain their decision-making and oversight responsibilities. Accurate details help insurers assess the exposure and provide terms relevant to the organisation, rather than a generic estimate.
- Describe the charity’s activities and the decisions trustees oversee.
- Summarise previous claims and any changes to the charity’s work.
- Decide what level of protection the charity is seeking.
- Review the proposed limit, exclusions and excess alongside the premium.
A lower premium may come with a different limit or narrower policy terms. Compare the scope of protection, not just the headline cost. Check how the wording treats legal costs, different trustee roles and claims arising from the charity’s activities. At renewal, tell the insurer about material changes, such as new services or altered governance responsibilities. This gives trustees a sound basis for assessing the quote and whether it fits.
For a tailored quote based on your charity’s circumstances, Get Your Free Business Insurance Quote now.
Just Quote Me: Professional Indemnity Insurance
Just Quote Me can help charities consider Professional Indemnity Insurance for risks arising from advice, training or other professional services. This cover addresses a different exposure from trustee indemnity insurance, which focuses on claims connected with trustees’ governance roles. If your charity provides professional services, the two covers may serve distinct purposes.
Just Quote Me can also help charities consider Public Liability Insurance and Employers Liability Insurance in relation to their activities and staffing. The appropriate protection depends on the work the charity carries out and the risks it faces. Reviewing the policy wording alongside the charity’s activities helps clarify which cover addresses each exposure.
For advice about insurance options for your charity, Request a Call back for free Expert advice.
Make your next insurance review count
Use your next insurance review to connect the charity’s plans with the protection it needs. Changes to services, partnerships or trustee responsibilities can alter the organisation’s risk profile. Treat the review as part of forward planning: identify emerging exposures, clarify which policy addresses each one, and keep the board’s decisions aligned with the charity’s activities.
Trustee indemnity insurance for charities is one part of a wider assessment. Just Quote Me offers Professional Indemnity Insurance, Public Liability Insurance and Employers Liability Insurance for related professional, public and staff risks. These covers address different exposures, so consider them in the context of your charity’s work.
A clear discussion can help you identify the cover relevant to your organisation and its next steps. Contact Just Quote Me about cover, and move forward with a practical insurance review for your charity.
Frequently Asked Questions
Can a charity use its money to buy insurance?
Yes, a charity can use its funds to buy trustee indemnity insurance, subject to its governing document and the charity’s interests. Trustees can record why the cover is relevant, how the premium relates to the charity’s needs and whether the governing document restricts insurance. If the document expressly prohibits the purchase, the charity generally needs Charity Commission authority before proceeding.
Are trustees jointly and severally liable?
Trustees of an unincorporated charity can have joint and several liability for the charity’s obligations. This means one trustee may face the cost if the others cannot pay. For example, if a charity cannot meet a contractual debt, trustees’ personal exposure may become relevant. The organisation’s legal structure and the circumstances of the obligation affect how liability applies.
Are trustees liable for a charity’s debts?
Trustees of an unincorporated charity can be personally liable for its debts and contractual obligations. For instance, if the charity enters a supplier contract but cannot meet its payment obligations, trustees may face personal exposure. This differs from a claim that a trustee personally acted improperly. The charity’s legal structure matters, so trustees should understand its effect on obligations before signing contracts.
How does it work?
The charity arranges a policy that names eligible trustees and sets out the claims, activities and costs it may cover. If a claim arrives, the trustee should follow the policy’s notification process and provide relevant documents, such as correspondence or meeting records. The insurer assesses the claim against the wording, exclusions and limit. A claim connected with charity work is not automatically covered.
What is trustee indemnity insurance for UK charities?
Trustee indemnity insurance is designed to protect individual charity trustees against covered claims arising from their trustee roles. Depending on the wording, this may include allegations involving wrongful acts or governance decisions. The policy may help with legal costs and claims for which a trustee is personally responsible. It does not replace careful governance, and its protection depends on the insured roles and policy terms.
Is trustee indemnity insurance the same as directors and officers insurance?
These are related forms of protection, but their names do not mean their policy terms are identical. Directors’ and officers’ insurance can cover claims arising from organisational mismanagement and associated legal costs. Trustee indemnity insurance focuses on claims against trustees in their charity roles. If a charity’s trustees also act as directors, compare the wording, insured people and activities to understand how the policies fit together.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Nov 12, 2026 | Insurance
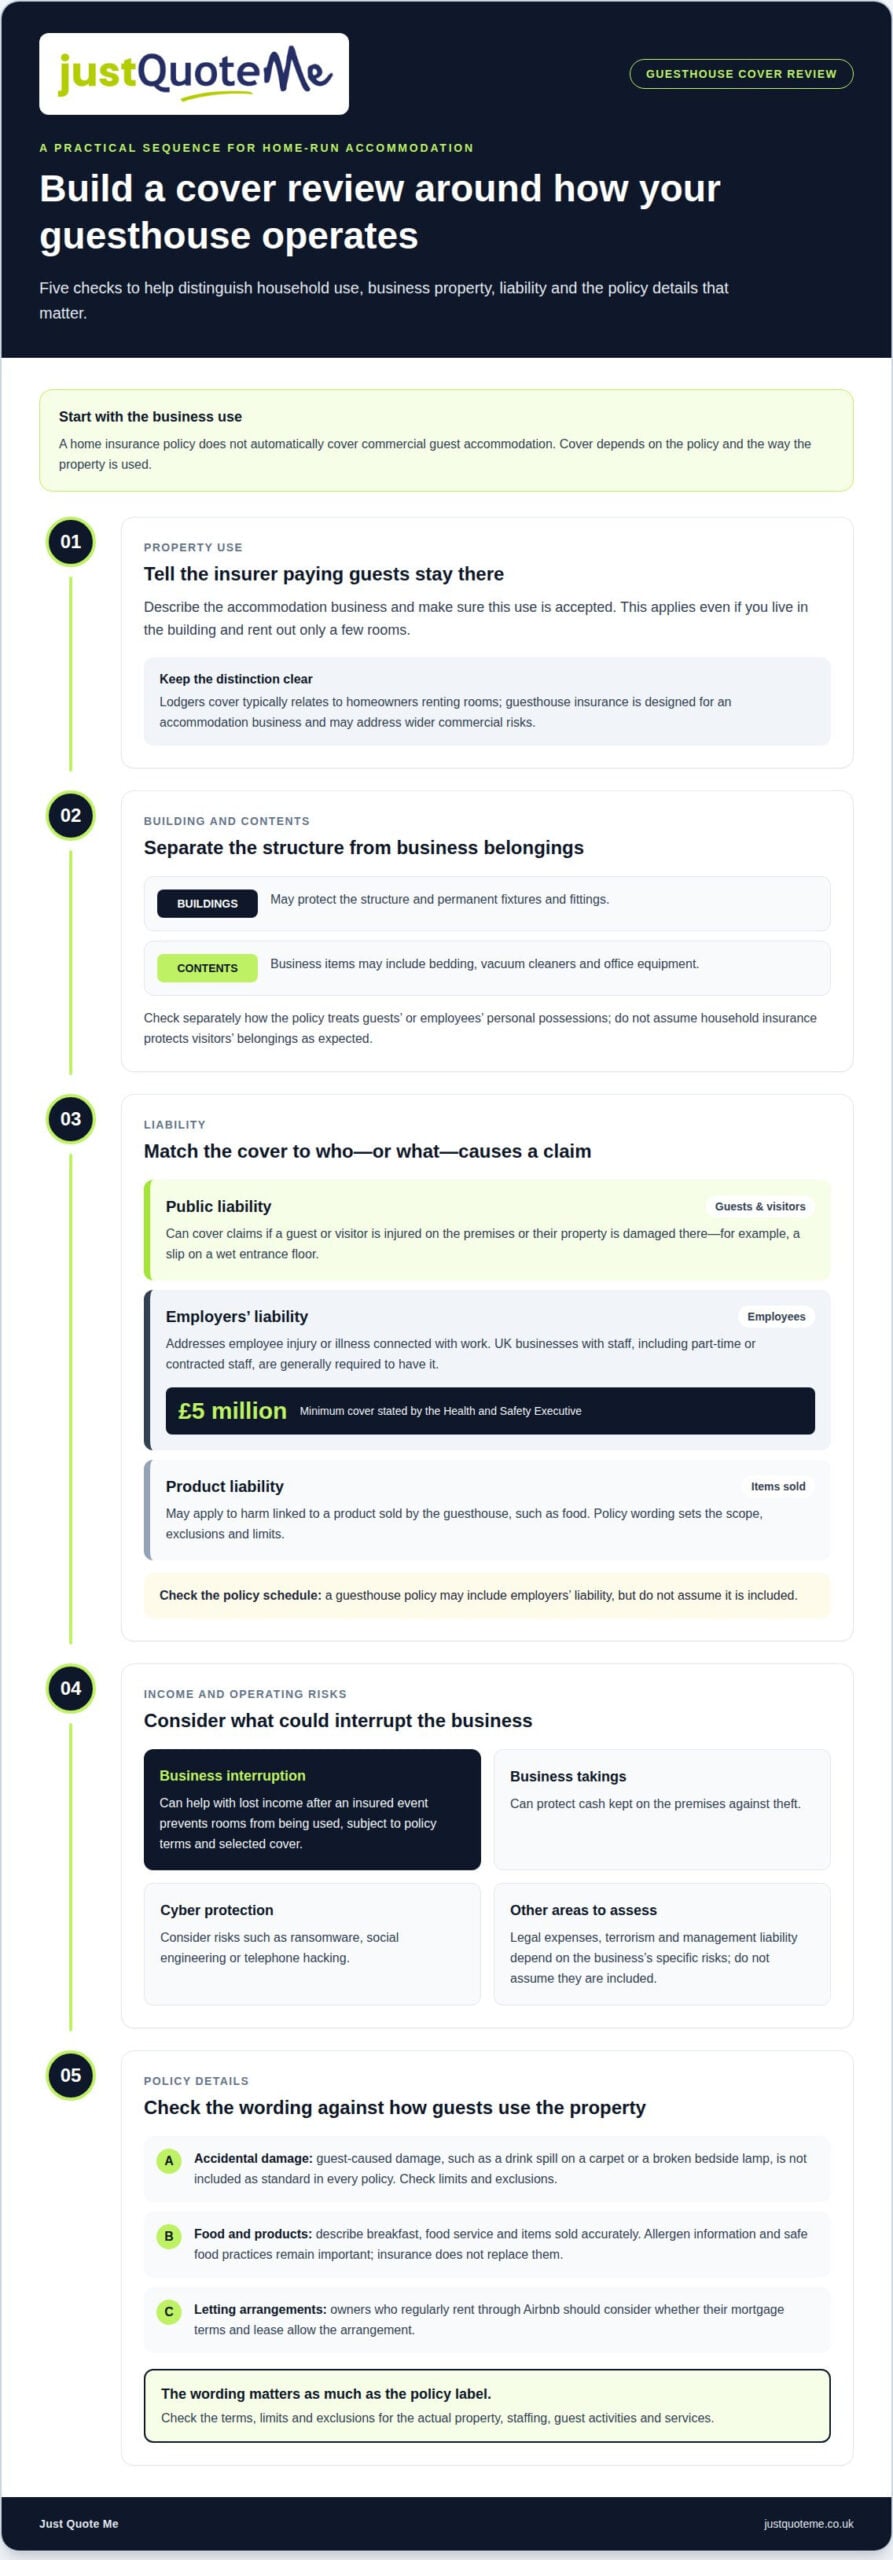
A small, home-run guesthouse may need more than an extension to ordinary home insurance. Guesthouse insurance for paying guests should reflect the accommodation business, including its property, liability to guests and any staff it employs. Public liability insurance can cover claims if a guest or visitor is injured or their property is damaged on the premises.
It’s easy to assume that home insurance or standard lodgers’ cover will take care of everything. But welcoming paying guests brings business risks that need separate consideration, and cover varies between policies.
This guide explains what guesthouse insurance can cover, how public liability differs from employers’ liability, and what to consider for a smaller or home-run property. It also covers buildings and contents, lost income, and details that can shape suitable cover, helping you make a clearer decision about protecting your guesthouse.
Key Takeaways
- Understand how public liability can respond to guest or visitor injury and property damage, and how it differs from cover for employee claims.
- See how guesthouse cover may bring together protection for the building, business contents, liability and income interruption.
- Identify why running accommodation from home can call for business-specific cover rather than relying on a household policy alone.
- Learn which property, staffing and guest-related details can help shape cover for a smaller hospitality business.
Public liability cover
For a bed and breakfast or guesthouse, public liability insurance can cover claims from guests and visitors injured on the premises, or whose property is damaged there. For example, a guest could claim after slipping on a wet entrance floor. The policy terms and limits determine the cover, so the wording matters as much as the policy label.
Public liability concerns members of the public and other businesses, not employees. That distinction matters if a guest is injured in a shared hallway, while a staff member is hurt doing their job. Public liability insurance addresses the first type of claim; employers’ liability addresses employee injury or illness connected with work.
Does guesthouse insurance include employers’ liability insurance, and when is it required? A guesthouse policy may include it, but the cover should be checked in the policy schedule. In the UK, businesses with staff, including part-time or contracted staff, are generally required to have employers’ liability insurance; the Health and Safety Executive says the policy must provide a minimum of £5 million cover.
What insurance does a UK guesthouse need when it accepts paying guests? Consider public liability alongside buildings, contents and business interruption cover, based on the property and how it operates. Public liability is not a substitute for cover for the building, furnishings or lost income if an insured event prevents rooms from being used.
Home insurance alone may not reflect the risks of running a bed and breakfast from residential premises. Buildings cover can protect the structure, while contents cover may protect items such as bedding and cleaning equipment. Business interruption cover can help with lost income after an insured event, subject to the policy terms and selected cover.
Consider specialist options as well. Guesthouse cover may include cyber protection for risks such as ransomware, social engineering or telephone hacking. Business takings cover can protect cash kept on the premises against theft. Legal expenses, terrorism and management liability are other areas to assess against the business’s specific risks, rather than assume they are included.
What is Guest House Insurance?
Guesthouse insurance brings together cover relevant to a business providing accommodation, with protection depending on the policy. Public liability concerns claims from guests or visitors. Product liability addresses a different risk: harm linked to an item the guesthouse sells. For example, a guest might allege that a product bought at reception caused an injury or damaged their belongings.
Food service provides a practical example. If a guest becomes ill after eating breakfast, they may make a claim against the business. Public liability may respond to injury claims, while product liability may apply if the claim relates to food or another product sold. The policy wording sets the scope, exclusions and limits for each type of liability cover.
Owners serving breakfast should also consider how they handle food information. The Food Standards Agency’s allergen guidance is relevant to guesthouses providing breakfast or other food. Clear, accurate allergen information can help guests make informed choices. Insurance does not replace safe food practices or the need to manage service risks carefully.
Consider the difference between a loose stair carpet and a packaged snack sold in the dining room. A guest who trips may bring a public liability claim about the premises. A claim involving an item sold by the guesthouse may fall under product liability, subject to the policy terms. Hotel and guesthouse policies vary, so quotes should reflect what the business actually serves and sells.
When reviewing cover, describe the accommodation and any food or retail activity accurately. This helps establish whether the selected covers match the likely sources of claims, rather than treating every incident as the same liability issue. For a property offering rooms and breakfast, explore a guest house insurance arrangement that takes both activities into account.
Commercial insurance for a home-run guesthouse
Running a guesthouse from your home changes how the property is used. A household policy does not automatically cover business activities just because accommodation is provided at home. If you serve breakfast, advertise rooms or regularly welcome paying visitors, guesthouse insurance can address risks connected with operating commercially.
Tell your insurer that paying guests stay at the property and ensure this use is accepted. Otherwise, a claim connected with guest accommodation may not match the use described under your home insurance. This distinction matters even if you live in the same building and rent out only a few rooms.
Guest house insurance and lodgers cover also serve different purposes. Lodgers cover typically relates to homeowners renting rooms, while a guesthouse policy is designed for accommodation businesses and may address wider commercial exposures. A bed and breakfast is generally a home-based accommodation business, while a guest house operates as a commercial accommodation business.
Think about the property as both a home and a business. Buildings cover may protect permanent fixtures and fittings, while business contents cover can include bedding, vacuum cleaners and office equipment. Guesthouse policies may also cover guests’ or employees’ personal possessions, but don’t assume household insurance will protect visitors’ belongings as you expect.
Accidental damage caused by guests is not included as standard in every policy. For example, a guest could spill a drink on a carpet or break a bedside lamp. Check how the policy treats such incidents, including any limits or exclusions. Owners who regularly rent through Airbnb should also consider whether their mortgage terms and lease allow this arrangement.
For a home-run operation, consider the building’s use, contents, guest belongings and public liability insurance together. If the property is rented, the lease may affect responsibility for buildings cover. Commercial property insurance can be relevant to the building side of a guesthouse’s protection.
Arranging specialist insurance for smaller hospitality properties
Smaller hospitality businesses need cover matched to their building, guests and income risks. For UK guesthouses, compare policy details, not just the headline premium.
Comparing Insurance Providers
Compare buildings insurance with the property’s rebuild cost, not its market value. Then review liability limits, contents protection and business interruption cover in case an insured event makes rooms unusable. Cover for guest possessions or accidental damage can address different needs, so check each inclusion and exclusion.
Consider how a policy treats risks specific to your operation. A guesthouse that serves breakfast, employs staff or keeps cash on the premises has different exposures from one offering rooms only. Hotels and small guesthouses may need specialist hospitality cover, but the relevant sections and limits depend on the business.
Getting an Insurance Quote
To get a quote, provide a clear picture of the premises and business. Useful details include the rebuild value, guest capacity, staff numbers, claims history and exposure to fire or flooding. Describe the accommodation and activities accurately, including any food service, so the proposed cover reflects how the business operates.
Use the quote to identify gaps between your needs and the proposed policy. For example, check whether business interruption cover addresses lost income while rooms are unavailable after an insured event. If you rent the premises, buildings insurance may be the landlord’s responsibility; the lease can clarify this. Reviewing the building, liability and income sections together helps you assess each risk in context.
Choose cover by matching policy wording to the property and its trading risks, rather than selecting limits by price alone. If the building’s rebuild value, guest capacity or activities change, those details can affect the cover required. Request a guesthouse insurance quote to explore cover suited to your hospitality business.
Just Quote Me: Hotel and Guest House Insurance
Just Quote Me arranges Hotel and Guest House Insurance for home-run B&Bs and smaller accommodation businesses. It’s a useful next step when you need cover shaped around the building, guests, staff and day-to-day operations, rather than relying on household insurance alone. Depending on your needs, cover can include public liability, employers’ liability or professional indemnity insurance.
Discuss the property’s use, guest arrangements and the risks you want the policy to address. This gives you a clearer basis for considering suitable cover and understanding how its different elements work together. Just Quote Me provides a straightforward route to advice tailored to your circumstances.
Request a call back for free expert advice from Just Quote Me.
Make your next insurance decision with confidence
Let the needs of your operation guide your next step. A clear picture of how you run the guesthouse and what you want the policy to protect can keep your choices focused as the business changes.
Review the details that matter to your operation, then decide whether you’re ready to explore a quote or would prefer to discuss your questions first. Just Quote Me can help you consider the next step for your circumstances.
Get your free, no-obligation Business Insurance quote, or request a free callback from Just Quote Me.
Frequently Asked Questions
What factors influence bed and breakfast insurance costs?
A quote for guesthouse insurance for paying guests depends on the property, its risks and the cover selected. Insurers may consider rebuild cost, property size and location, guest capacity, staff numbers, claims history, and exposure to fire or flooding. A swimming pool or selected extras, such as home emergency cover, can also affect the assessment. Describe the business accurately when requesting a quote.
Am I covered if a guest damages a room?
Guest damage is covered only if the policy includes protection that applies to the incident. Accidental damage caused by guests isn’t included as standard in every guesthouse policy. For example, a guest might stain a carpet or break a lamp; the policy wording determines whether the damage is covered and which limits or exclusions apply. Review the accidental damage terms alongside your buildings and contents sections.
Are there any exclusions?
Yes, exclusions and limits depend on the policy wording. Accidental damage caused by guests may not be included, and household insurance does not automatically protect guests’ possessions. Review the schedule and wording for exclusions affecting the building, contents, liability and any optional cover. For instance, a policy may treat damage to furnishings differently from damage to the structure, so check each section separately.
Are there any more additional covers?
Yes, additional protection may address risks beyond the core property and liability sections. Options may include business interruption cover for lost income after an insured event, business takings cover for cash kept on the premises, and cyber protection for risks such as ransomware or telephone hacking. Legal expenses, terrorism and management liability are other areas to consider. Relevant options depend on how the guesthouse operates.
Can I protect my guests and employees’ personal possessions?
Yes, guesthouse policies may cover guests’ and employees’ personal possessions against loss or damage. The policy wording sets which belongings qualify, the applicable limits and any exclusions. For example, a guest’s coat or an employee’s bag may be treated differently from business equipment such as bedding or office items. Review the personal possessions section separately from business contents cover.
Do I need public liability cover for my Bed & Breakfast?
For guesthouse insurance for paying guests, public liability cover is identified as a legal requirement for guesthouse insurance. It relates to claims from guests, visitors or other members of the public, rather than employee injury claims. For example, a visitor who alleges an injury on the premises may bring a public liability claim. Employers’ liability is separate and is legally required for businesses with staff, including part-time or contracted workers.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Nov 11, 2026 | Insurance
What if the most important part of professional indemnity cover is what it leaves out? The common exclusions in professional indemnity policies include dishonest acts, fines and penalties, bodily injury or property damage, and claims linked to work outside the policy’s stated scope. Policies contain about 20 standard exclusions on average, but the exact wording varies.
It’s sensible to expect professional indemnity insurance to respond when a client alleges an error or omission in your work. But an exclusion can limit or remove cover for a particular claim, and some policies include exceptions or write-backs that affect how an exclusion applies.
This article explains what professional indemnity insurance is, the exclusions you’re likely to encounter, and why declared services, the retroactive date and contractual terms matter. You’ll also see how exclusions can differ between professions, helping you read your policy wording and understand where cover may stop.
Key Takeaways
- Contract terms can create liabilities beyond your usual professional duty, so understand how the policy treats guarantees, penalties and damages.
- Known claims and circumstances may affect cover from the outset, while the retroactive date can determine whether earlier work falls within the policy period.
- Fraudulent, dishonest or criminal acts are generally excluded; the wording also determines how claims involving individuals are handled.
- Exclusions vary with your profession, services and policy wording, so focus on the risks most relevant to the work you actually do.
Contractual liability beyond the usual duty of care
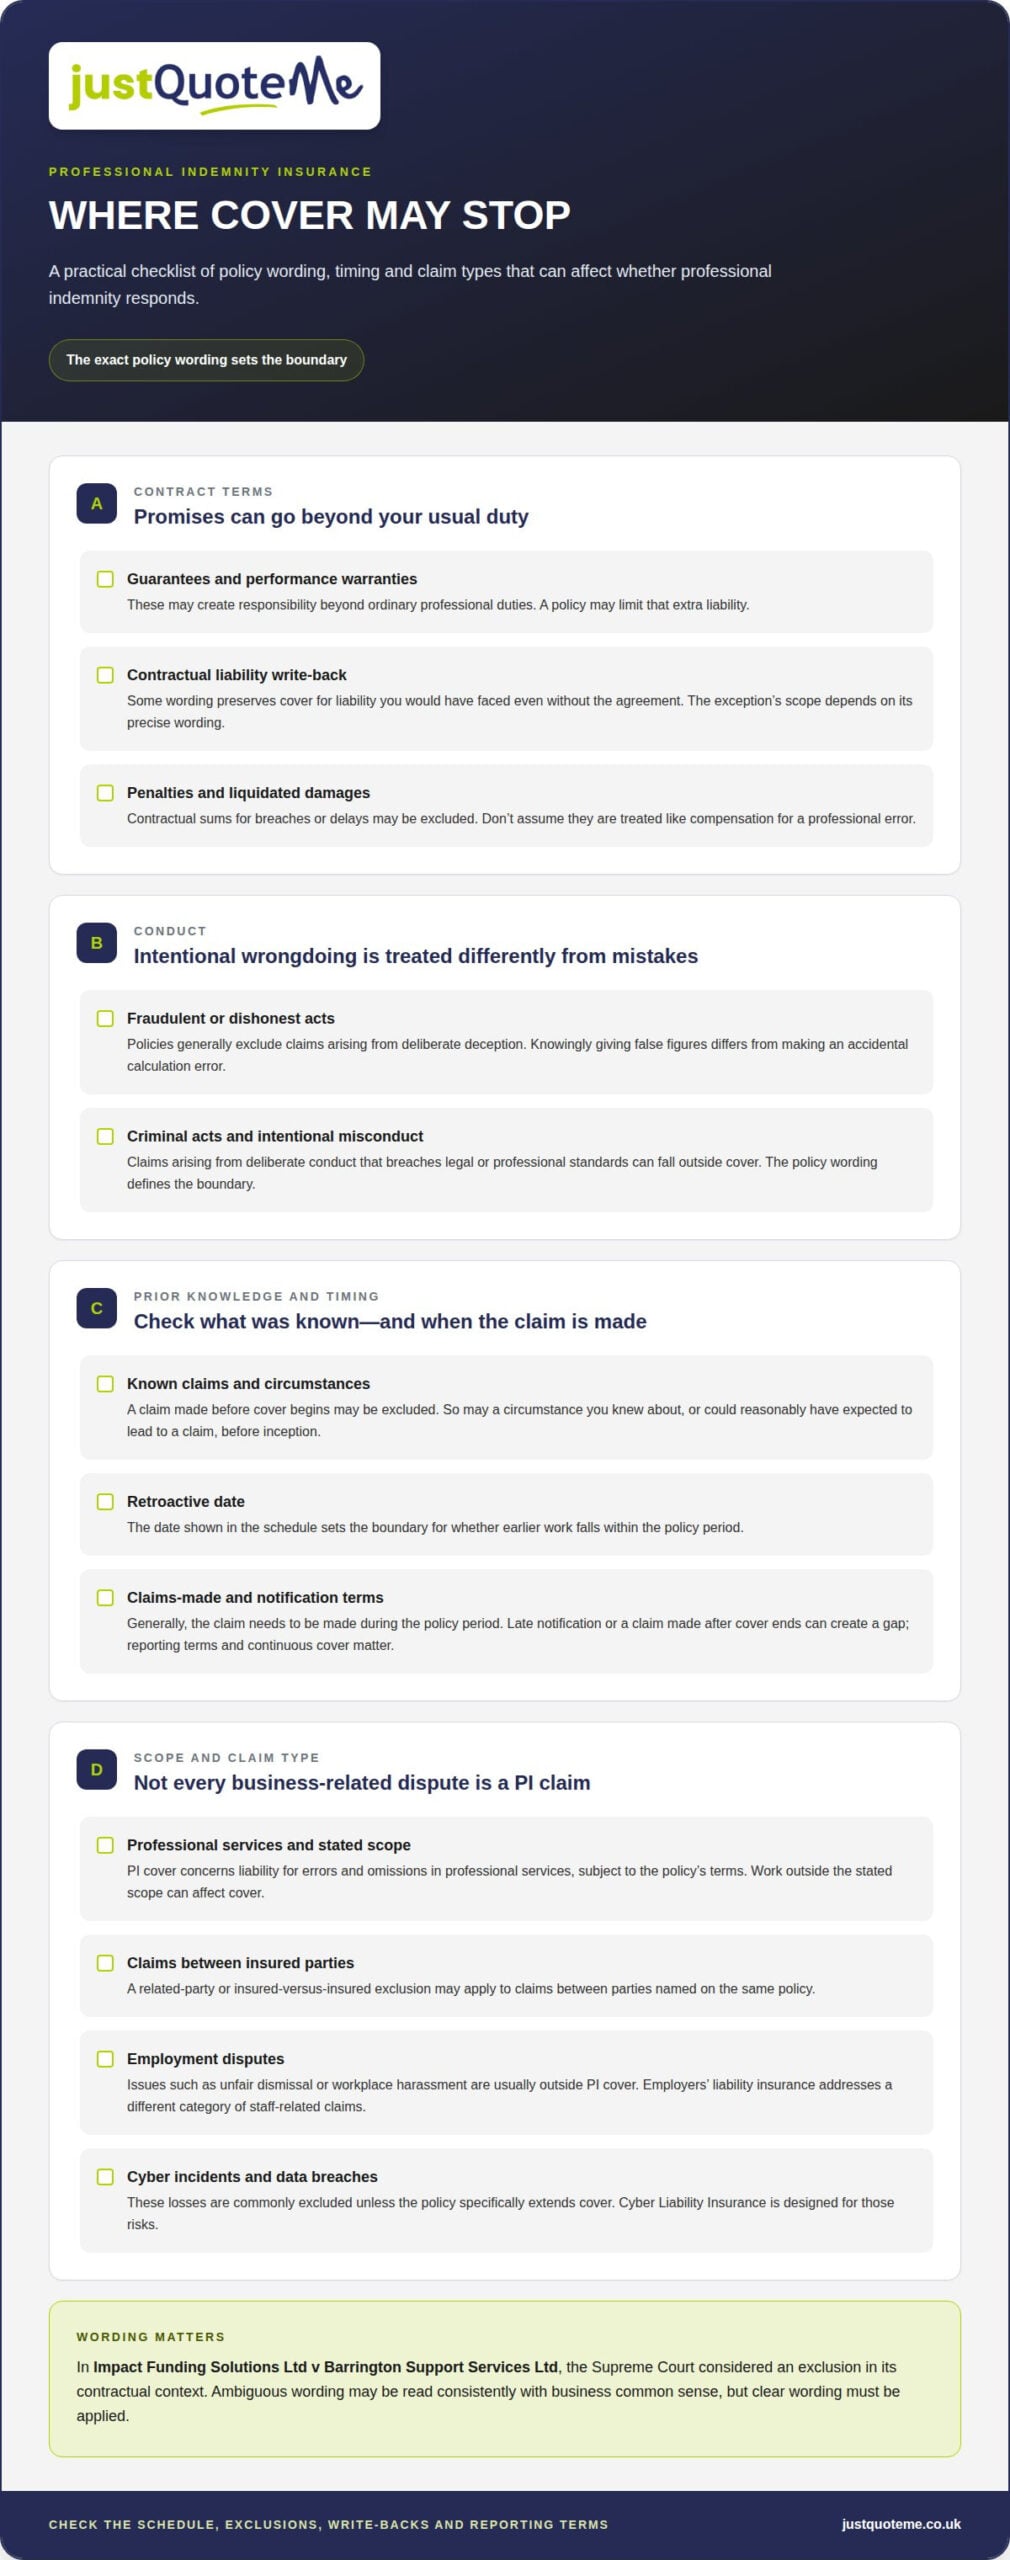
A contract may make you responsible for more than negligence under your usual professional duty. Guarantees, performance warranties and other promises can therefore create liabilities that a professional indemnity policy treats differently.
Assumed Contractual Liabilities
Assumed contractual liability is responsibility accepted through an agreement that would not otherwise arise under ordinary duties. A policy may limit cover for this additional responsibility, even when the same work could otherwise lead to a negligence claim. Some policy wordings include a contractual-liability write-back, preserving cover for liability you would have faced without the agreement. The precise wording determines the scope of that exception.
Penalties and Liquidated Damages
Contractual penalties and liquidated damages are sums specified in an agreement for particular breaches or delays. Professional indemnity policies may exclude these amounts, so do not assume they are treated like compensation for a professional error. For example, a clause requiring a fixed payment when a project misses a deadline may create a contractual obligation beyond the usual duty of care. The policy wording determines how that liability is treated.
Are contractual liability, guarantees and performance warranties excluded from professional indemnity insurance? They may be excluded to the extent they impose liability beyond your usual professional duty, but some policies write back cover for liability that would exist without the contract. For example, a consultant who guarantees a 50% revenue increase may not have cover for that additional promise if the target is missed.
Ambiguous wording does not automatically mean broader cover applies. In Impact Funding Solutions Ltd v Barrington Support Services Ltd, the Supreme Court considered how an exclusion should be interpreted in its contractual context. A court may favour a reading consistent with business common sense when wording is ambiguous, but must apply clear wording. This distinction matters when a contractual promise appears to expand the insured’s liability beyond negligence or regulatory obligations.
What is Professional indemnity insurance?
Professional indemnity insurance covers liability to pay compensation for errors and omissions in professional services. A client might allege that an architect’s design error caused financial losses, or that an accountant gave negligent advice. Subject to the policy’s terms and exclusions, cover can include the costs of defending a claim.
Claims often concern advice, designs, reports or other work delivered to a client. The alleged loss may be financial rather than physical: for example, a client may say an inaccurate assessment led to a costly business decision. Professional indemnity responds to alleged professional failings, not every dispute connected with a business relationship.
Known claims and circumstances can affect whether a policy responds. A known-claim exclusion generally applies to claims made before cover begins. A known-circumstance exclusion may apply when, before inception, you knew or could reasonably have expected that an issue might lead to a claim. Matters disclosed to the insurer before cover starts may also be excluded. The retroactive date in the schedule sets the boundary for earlier work.
Most professional indemnity cover operates on a claims-made basis. The claim generally needs to be made during the policy period, and late notification or a claim made after cover ends can create a gap. For example, a client may complain about advice near renewal but issue a formal claim later. Continuous cover and the policy’s reporting terms therefore matter.
Claims between parties named on the same policy may fall under a related-party or insured-versus-insured exclusion. Employment disputes, such as unfair dismissal or workplace harassment, are also usually outside professional indemnity cover. Employers’ liability insurance addresses a different category of staff-related claims.
How do professional indemnity policies treat claims arising from cyber incidents and data breaches? These losses are commonly excluded unless the policy specifically extends cover. Cyber Liability Insurance is designed for those risks.
To consider cover in light of your services and the claims you face, Request a Call back for free Expert advice.
Fraud, dishonesty and deliberate wrongdoing
Professional indemnity policies generally exclude claims arising from fraudulent, dishonest or criminal acts. The wording matters because an allegation of poor work differs from deliberate deception.
Fraudulent and Dishonest Acts
A dishonest act involves deliberate deception, while fraud is dishonest conduct intended to gain an advantage or cause loss. Policies generally exclude claims arising from these acts, even when they occur during professional work. For example, knowingly giving a client false figures differs from making an accidental calculation error. The exclusion focuses on the conduct behind the claim, not simply the fact that a client suffered losses.
Consider a consultant who knowingly alters a report to secure a contract. If the client later claims financial loss arising from that deception, the fraud exclusion may apply. By contrast, a mistaken figure could give rise to a negligence claim rather than deliberate dishonesty. The policy wording sets the relevant boundary, so the distinction between an error and intentional conduct can affect how the claim is assessed.
Criminal Acts and Intentional Misconduct
Criminal acts and intentional misconduct are deliberate actions that breach legal or professional standards. A policy exclusion can leave claims arising from such conduct outside cover. For example, deliberately misusing a client’s funds differs from an administrative mistake that causes financial loss. Professional indemnity is not protection for intentional wrongdoing.
The retroactive date addresses when insured work began, but it does not turn deliberate conduct into covered negligence. Likewise, an injury or property damage claim may engage separate policy exclusions, so the cause and wording remain central. A client alleging fraud does not, by itself, establish whether the conduct was deliberate. The policy’s definitions, the alleged facts and the established circumstances all inform how the exclusion applies.
Keep records showing how advice was prepared and communicated. Dated client instructions, working papers and report versions, for example, can help distinguish an unintended error from a deliberate alteration. Clear documentation does not remove an exclusion, but it can provide a factual account of the professional conduct at issue.
Common professional indemnity exclusions
Professional indemnity insurance focuses on liability for professional errors and omissions, not every business loss. Common exclusions can cover physical injury, property damage, penalties, cyber incidents, employment disputes, trading debts and pollution. Exact wording varies with the profession, the risk and the insurer’s underwriting approach.
Are bodily injury and property damage excluded from professional indemnity cover in the UK? Many policies exclude these claims, although some include a write-back for injury or damage arising from a breach of professional duty during professional services. A client injured by a design error may therefore raise different issues from damage caused during ordinary business operations.
Public Liability Insurance generally addresses third-party injury and property damage, rather than errors in professional advice. Professional indemnity policies may also exclude fines and penalties, even where they cover the cost of defending a claim. A regulatory penalty and a client’s compensation claim are distinct liabilities, so the wording can lead to different outcomes.
How do pollution, asbestos and environmental damage exclusions apply to professional indemnity policies? Policies may exclude claims arising from pollution or environmental damage and commonly include asbestos exclusions. For example, a claim alleging that professional advice caused contamination may engage specific exclusion wording, while an asbestos-related claim may be excluded because of associated health risks and long disease latency.
Other exclusions can remove cover for refunds of professional fees, unpaid trading debts or loan repayments. A client seeking repayment of fees after dissatisfaction may therefore bring a different claim from one seeking compensation for negligent advice. Claims brought in a United States court may also be excluded, as may product liability claims and employment disputes such as unfair dismissal.
Use the policy schedule and wording to identify declared services, territorial limits and exclusions. A newly added service outside the declared work can create a gap, while a cyberattack may require separate cyber cover. Matching the policy to your actual activities is a practical way to clarify which claims are covered.
For help considering cover against your professional risks, Request a Call back for free Expert advice.
Just Quote Me: Professional Indemnity Insurance
Just Quote Me can help you consider Professional Indemnity Insurance in relation to your professional services and the exclusions discussed above. This can be useful when your work changes, you take on new contractual responsibilities, or you need to understand how declared activities and policy wording affect cover. The aim is to identify relevant cover considerations, not to assume every claim will be insured.
Different risks may call for different types of cover. Public Liability Insurance relates to third-party injury or property damage, while Employers Liability Insurance concerns staff-related risks. Just Quote Me can help you consider these alongside professional indemnity, where they fit your business needs.
Request a Call back for free Expert advice from Just Quote Me.
Make your next cover review purposeful
Use your next renewal or contract review to consider how your insurance fits the work you plan to take on. New clients, changing responsibilities and expanded services can alter the risks your business faces. A clear view of those changes helps you discuss cover in practical terms rather than rely on assumptions about what a policy includes.
The common exclusions in professional indemnity policies are one part of that review. Consider how Professional Indemnity Insurance relates to your professional work, and whether Public Liability Insurance or Employers Liability Insurance addresses other risks your business may face. Each policy serves a different purpose, so understanding how they fit together can support informed decisions.
Just Quote Me can help you consider these business insurance needs. For support with your next step, Request a Call back for free Expert advice from Just Quote Me. A considered review can make it easier to move forward with clarity.
Frequently Asked Questions
What are the common exclusions in UK professional indemnity insurance policies?
Common exclusions in professional indemnity policies include claims involving fraud, penalties, bodily injury or property damage, cyber incidents, employment disputes, trading debts and pollution. Policies may also restrict cover for work outside declared services, certain territories or the retroactive date. For a practical review, group exclusions by the risks your business faces: client advice, staff matters, physical damage and digital incidents. Then read the schedule alongside the policy wording.
Do professional indemnity policies exclude fraud, dishonesty or deliberate wrongdoing?
Generally, yes. Claims arising from fraudulent, dishonest or criminal acts are usually excluded. An allegation alone does not establish what happened, so the policy wording and facts of the claim matter. For example, a client disputing an inaccurate report raises different issues from evidence that someone knowingly altered figures. Keep dated instructions and report versions to help establish how the work was prepared and communicated.
Do UK PI policies exclude known claims, prior circumstances or work completed before the retroactive date?
They can. A known-claim exclusion generally concerns claims made before the policy starts; a known-circumstance exclusion can apply to an earlier issue that could reasonably lead to a claim. Work before the retroactive date may also fall outside cover. For example, a complaint disclosed before inception or an earlier project named in a dispute may need close attention to the application, schedule and notification terms.
Are fines, penalties, punitive damages and taxes covered by UK professional indemnity insurance?
Fines and penalties are typically excluded, including civil or criminal penalties and punitive, aggravated or exemplary damages. A policy may cover defence costs for a claim without covering a penalty imposed by law. Tax-related demands depend on their nature and the wording: repayment of a tax amount differs from compensation claimed for negligent tax advice. Separate those elements when assessing what the claim seeks.
What exclusions commonly apply to employee claims, insolvency and related-party disputes under PI policies?
Employment disputes such as unfair dismissal, workplace harassment and staff complaints are usually outside professional indemnity cover. Some policies also exclude insolvency-related claims, including trading debts or losses directly caused by a client’s or insured’s collapse. A related-party exclusion may prevent a claim by another party named on the same policy. For instance, a co-insured business generally cannot rely on that policy to claim against another insured party.
How do professional indemnity exclusions vary by profession, insurer and policy wording in the UK?
The common exclusions in professional indemnity policies vary with the profession, work performed, risk presented and insurer’s underwriting approach. A management consultant may face restrictions around investment advice or business valuations, while a healthcare professional may see an exclusion for experimental treatment. Financial services cover may treat pension transfer advice differently. Compare declared activities and specific exclusions with the actual services, contracts and territories involved in your work.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Nov 10, 2026 | Insurance
A soft insurance market doesn’t guarantee a cheaper hospitality renewal. It may create more opportunity to secure competitive terms, but the outcome still depends on your business’s needs and the risks insurers assess. A hospitality insurance broker in Newcastle-under-Lyme can help you understand the policy options and terms.
It’s reasonable to look for savings when the market softens, but price is only part of the decision. The cover should reflect your operation, whether you run a pub, restaurant, hotel or another hospitality business.
This article explains how market conditions may affect premiums, what can shape cover and cost, and how a local broker can help. It also outlines what to consider when arranging or reviewing hospitality insurance, so you can make an informed decision.
Key Takeaways
- A soft insurance market may create opportunities for competitive terms, but your business’s risks and cover needs still shape the renewal.
- Tailor protection to your hospitality operation, considering liabilities and potential interruption to income.
- Buildings, contents, machinery and stock may all need consideration when arranging commercial cover.
- Local broker support can help you understand suitable options, including Public Liability Insurance and Employers Liability Insurance.
Tailored insurance programmes for hospitality businesses
A suitable insurance programme starts with your operation, premises and the risks involved in serving guests or handling food. A hotel, pub, restaurant or catering business may need different cover, even if each serves food and drink.
Required cover and policy exclusions
For UK hospitality businesses, employers’ liability is the key cover to consider when people work for the business, while public liability addresses a different exposure. Legal requirements depend on employment arrangements, so distinguish cover for staff from protection against claims involving customers. Review exclusions relating to stock spoilage, equipment failure and business interruption, and check the conditions that apply to each event.
Business interruption cover may help with lost income and operating expenses after physical or material loss, and may include temporary relocation. For a restaurant or caterer, spoiled ingredients can create a separate financial concern, so check how the policy treats stock loss and which circumstances are covered. A pub or hotel should also consider buildings, contents, machinery and stock as distinct parts of its risk profile.
Broker options and liability cover
Choose a Newcastle-under-Lyme broker with experience arranging cover for hospitality operations, rather than relying on a policy designed for a different trade. Public Liability Insurance and Employers Liability Insurance address different exposures; a broker can help establish which risks each policy responds to and how limits and exclusions fit the business. No named local broker is identified here.
For UK hospitality businesses, cover should reflect the services provided and the risks involving customers, suppliers and day-to-day operations. Risk management can also help identify practical measures for staff safety, theft and business interruption. Review your policy alongside those measures, especially when you add a location or change how you serve customers.
Commercial insurance brokers near Newcastle-under-Lyme
A commercial broker can help shape cover around your premises, stock and trading activity. A hotel may need buildings, contents and machinery considered separately, while a restaurant’s commercial kitchen creates distinct equipment and stock exposures. A pub holding wine or spirits should consider how its stock is treated, including the terms that apply if goods are damaged or spoiled. Your broker should explain these distinctions clearly, rather than treating every business as identical.
FCA authorisation applies to individual firms, not to every broker in Newcastle-under-Lyme. You can check a firm’s status by searching its legal name or reference number on the Financial Conduct Authority’s Register, then confirming the result relates to the service you’re considering.
Commercial cover extends beyond hospitality. A shop has different property, stock and customer risks from a bar, so its policy should reflect its actual activities and premises. If you have both a home and a trading location, personal and commercial insurance address different needs and are not interchangeable. Before discussing cover, make a clear list of locations, equipment and stock.
Ask how the proposed wording treats kitchen equipment, refrigerated goods and wine stock, and whether exclusions or conditions affect those items. For example, damage to a fridge and spoilage of its contents may involve separate policy terms. A broker can explain the relevant sections and identify where cover needs to match the business’s operations. For advice about commercial and personal insurance options, speak with an insurance broker about the risks you need to address.
Personal service from a local agency
A conversation with a broker can help connect business decisions with your personal circumstances. For example, a pub director may want to discuss how an injury could affect daily operations, while keeping personal protection separate from the business policy. Clear advice should explain which policy applies to each situation, rather than treating every concern as one insurance need.
Personal accident cover is different from liability insurance. An individual may consider it for financial support following an injury caused by an accident, but its scope depends on the policy wording. Check the events covered, exclusions, benefit terms and definition of an eligible injury. Don’t assume this cover protects staff, customers or business income.
Personal insurance also serves a different purpose from commercial cover. A restaurant owner’s home and household belongings face different risks from the restaurant’s premises, kitchen equipment and stock. Discuss each requirement separately, and make sure the information used for a quote reflects the right person, property and activity. This helps keep business and personal arrangements clear.
Claims support is another practical part of a broker’s service. If a burst pipe damages a guest house, the owner may need to explain the damage, affected rooms and resulting interruption. Keep relevant records together, such as photographs, repair details and evidence of how the business was affected. A broker can help clarify the claims process and liaise with insurers, while the policy wording determines what the cover responds to. Ask who will handle updates and what information is needed at each stage, so responsibilities are clear during a stressful event.
Local insurance brokerage in Newcastle-under-Lyme
For a hospitality business in Newcastle-under-Lyme, useful brokerage means advice shaped around the operation, not just its postcode. A town-centre café, a pub with rooms and a guest house face different property, customer and trading exposures. Start by mapping each activity, premises and key asset to the cover you’re considering.
A soft market may make insurers more willing to consider particular risks, but it doesn’t automatically make every business cheaper to insure. Premiums and terms still reflect factors such as premises, claims history, risk controls and selected cover. For example, a restaurant with updated fire precautions presents a different risk picture from one with unresolved maintenance issues. A broker can explain how these details shape the options.
Use a simple renewal process. First, outline changes since the last policy, such as new rooms, extended opening or added equipment. Next, identify the value and use of buildings, contents, machinery and stock. Then discuss exclusions, conditions, excesses and how a claim would be handled. This gives your broker a clearer picture and helps you understand what the policy does and doesn’t address.
Local support can also make policy discussions more practical: a broker can explain unfamiliar wording using examples from a hotel, bar or catering operation. That clarity can bring peace of mind, provided the chosen cover matches the risks and the policy terms. To discuss the details of your hospitality operation and possible cover, request insurance support.
Just Quote Me
Just Quote Me helps hospitality operators review their business risks and insurance options. When your renewal approaches, you open a venue, change services or add premises, a broker can assess how those changes affect your cover. Just Quote Me can explain policy terms and help identify suitable options through access to a broad network of UK insurers.
A soft insurance market can create room for competitive terms, but price alone doesn’t show whether a policy fits. Just Quote Me can help you consider relevant exposures, including Public Liability Insurance and Employers Liability Insurance. For a hospitality business serving guests or employing staff, the discussion should distinguish customer-facing risks from employment-related responsibilities.
To make a review useful, provide a concise account of your activities, premises, staffing arrangements and recent changes. A restaurant adding takeaway service, for example, may need its business description and policy details reviewed. Your broker can explain relevant limits, exclusions and conditions, and outline how Professional Indemnity Insurance or Landlord Insurance may relate to particular responsibilities. This keeps the discussion focused on your circumstances rather than generic policy labels.
If you already have cover, your policy schedule and renewal information can help frame the discussion. Just Quote Me can explain how options relate to your hospitality business and what details affect the arrangement, without presenting a softer market as a promise of a lower premium. This can be useful when circumstances have changed or policy wording feels unclear.
For a straightforward discussion, contact Just Quote Me.
Make your next renewal a clear decision
Use your next renewal to align your policy with how your hospitality business operates now. A hospitality insurance broker in Newcastle-under-Lyme can help you discuss changes, understand relevant terms and consider whether the cover still fits your priorities. The value of a soft market lies in reviewing the details, not assuming every renewal will cost less.
Just Quote Me offers Public Liability Insurance, Employers Liability Insurance and Professional Indemnity Insurance. These policies address different business exposures, and a broker can explain how they relate to your circumstances. Start with your operation, the risks you want to address and the applicable policy wording.
You don’t need to make a sales decision before you understand your options. A practical conversation can help identify what to discuss at renewal and what information would clarify the cover. Get Your Free Business Insurance Quote now, or Request a Call back for free Expert advice from Just Quote Me.
Frequently Asked Questions
What hospitality insurance cover do pubs, restaurants, cafés and hotels need in the UK?
Cover depends on your business’s activities, premises and staffing arrangements. Employers’ liability is the policy to discuss when employees work for the business, while public liability addresses claims involving third parties. A café serving takeaway food may also need to consider product-related exposures. For a hotel, the discussion may include guest areas and property. A broker can map each risk to the relevant policy and clarify legal requirements for your circumstances.
How much does hospitality business insurance cost in Newcastle-under-Lyme?
The cost depends on your business and is provided after a quote request. Factors include the type of venue, its activities and premises, the cover selected, claims history and risk controls. A café with limited seating has a different profile from a hotel with guest rooms and a bar. A soft market may influence insurers’ appetite, but it doesn’t establish a standard premium or guarantee a lower renewal.
How can I compare quotes from hospitality insurance brokers in Newcastle-under-Lyme?
Compare the cover, not just the headline premium. For each quote, review insured activities, policy limits, excesses, exclusions and conditions, then check that the same business details appear throughout. For example, a quote should reflect both restaurant dining and takeaway operations if both apply. A hospitality insurance broker in Newcastle-under-Lyme can explain differences in wording and help you understand what each option covers.
Does hospitality insurance cover food poisoning, customer injury and property damage?
These incidents may involve different sections of a policy, and cover depends on the wording and circumstances. A customer injury claim may relate to public liability, while a food poisoning allegation could involve product liability. Damage to business property is a separate consideration. Report incidents promptly in line with the policy’s claims process and keep relevant records, such as incident details, correspondence and receipts.
What cover is available for business interruption, equipment breakdown and stock spoilage?
Business interruption cover may help with lost income and operating expenses after physical or material loss. Cover for equipment breakdown and spoiled stock depends on the policy’s insured events, exclusions and conditions. For example, refrigeration failure may affect stock, but the wording determines whether that cause of loss is covered. Ask how each section responds and whether interruption cover requires damage to insured property first.
How do I get a hospitality insurance quote from a Newcastle-under-Lyme broker?
Prepare details of your trading activities, premises, staffing, claims history and the cover you need. Include changes such as new services or alterations to the venue, so the quote reflects your current operations. Just Quote Me provides free, no-obligation insurance quotes. Get Your Free Business Insurance Quote now, or Request a Call back for free Expert advice.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Nov 9, 2026 | Insurance
A commercial property’s rebuild cost can differ greatly from its market value. Calculating the rebuild cost of a commercial property means estimating what it would cost to reconstruct the building from the ground up, not using its sale price or investment value.
It’s easy to focus on the structure, but the total may also include demolition, site clearance, labour, materials and professional fees. The estimate should account for current building regulations and energy requirements, as well as the property’s design and site conditions.
This guide explains what rebuild cost means and what a commercial reinstatement estimate should include. It covers demolition and clearance, professional fees, regulatory standards and energy efficiency, and explains why an accurate figure matters when arranging commercial property insurance.
Key Takeaways
- Separate rebuild cost from market value: it estimates the cost of reinstating the building, not its sale or investment value.
- Use a calculator as an initial estimate, then consider a professional reinstatement valuation for the property’s specific features and constraints.
- Allow for current building requirements and energy-efficiency standards, which can affect the materials, design and work involved.
- Include demolition, debris removal and site clearance alongside construction, labour and professional fees when assessing the full rebuild scope.
What is commercial property rebuild cost?
A commercial rebuild cost estimates the expense of reconstructing a building from the ground up. The Association of British Insurers defines it by the cost of rebuilding, not by the property’s market value.
Rebuild assessments and estimation methods
Calculating the rebuild cost of a commercial property means estimating reinstatement costs, not its sale price. A calculator can apply construction rates to gross internal area, then adjust for complexity, specification and scale. Its result is indicative. A professional assessment can account for the building’s characteristics, condition and site constraints to produce a figure tailored to the property for an insurance declaration.
Fees and additional rebuild requirements
A complete estimate includes costs beyond construction, including architects’ and other professional fees, demolition, site clearance and external works. It should also account for planning requirements and compliance with current building regulations. Commercial reconstructions typically attract the UK standard VAT rate of 20%. These items matter because leaving them out can make the insured rebuild figure lower than the total reinstatement cost.
Reviewing insurance rebuild estimates
Review a commercial property’s rebuild estimate regularly, as building and labour costs can change. A formal RICS Insurance Reinstatement Valuation considers the building’s characteristics, condition and constraints. Waiting more than three years for a professional survey significantly increases the risk of a valuation gap. Regular reviews help keep the insured figure aligned with the work needed to reinstate the property.
Underinsurance and overinsurance risks
Underinsurance can reduce a claim payment under the average clause, a standard feature in most commercial property insurance policies. For example, a building with a £1,000,000 rebuild cost insured for £700,000 is covered for 70% of its rebuild cost. A £300,000 fire claim could then be paid at 70%, leaving the policyholder to cover £90,000. Overinsurance means insuring above the estimated rebuild cost, which can mean paying for more cover than the reinstatement figure requires.
Building regulations and energy-efficiency requirements
Building standards, energy performance and heritage constraints can change the work involved in reinstatement. These factors also affect how a valuer assesses construction complexity across commercial buildings.
Energy-efficiency expectations can influence the specifications considered for new commercial builds. Rebuilding an older property may therefore involve energy-efficiency requirements that differ from simply replacing its damaged structure. The materials and specification needed to meet current expectations can affect the estimate. The assessment should reflect the work required for the particular building, rather than assume an identical replacement.
Owners of Grade I and Grade II listed buildings need to allow for like-for-like replacement using specialist heritage materials and labour. For example, reinstating a listed façade may require matching its original materials and detailing. These constraints can make the work more complex than rebuilding a modern commercial unit. A valuation should reflect the property’s heritage status and the specialist construction methods required for reinstatement.
Rebuild rates per square metre vary by property type because buildings differ in size, layout, construction and specification. A straightforward industrial unit and a complex commercial building won’t necessarily have the same rate. Assessments apply building cost rates to gross internal area, then adjust for complexity, specification and scale. A larger floor area does not automatically mean a proportionally higher total, as size adjustments may account for economies of scale.
Valuers consider features that affect the work, including the building’s construction type, configuration and condition. Access restrictions and specialist plant machinery can also affect the base construction rate, particularly if they make reinstatement more difficult. For a listed building, heritage materials and specialist labour are relevant; for a modern commercial building, its design and energy-performance requirements shape the assessment.
These factors help define the reinstatement figure used for insurance, rather than the building’s market value. A considered commercial property insurance arrangement should reflect the specific building and its rebuild requirements.
Demolition and site-clearance costs
Demolition and site clearance are part of reinstating a commercial building after a total loss. The estimate needs to include removing the damaged structure and clearing debris before reconstruction begins. Treating these as separate from construction can leave the insured rebuild figure short of the full cost of the work. The property’s market value doesn’t show what demolition, clearance and rebuilding the site would involve.
Site conditions affect the work. Restricted access can limit how demolition equipment and materials reach the building, while specialist plant machinery may be needed for particular structures. Restricted access or specialist plant machinery can increase a commercial property’s base construction rate by 10% or more. Location matters through these practical constraints: a site that is difficult to reach or work on can require a different allowance from one with straightforward access.
Clearance also includes the work needed to prepare the site for rebuilding. An assessment should consider debris removal and any external works connected with reinstatement, not just the building’s internal structure. For example, if the insured property includes external areas affected by the loss, the estimate should reflect their reinstatement too. The scope depends on the site and the damage being assessed.
Labour is involved in both demolition and clearance and the subsequent construction. The estimate should reflect the work involved in taking down the damaged building, removing materials and preparing the site. These tasks contribute to the total even though they don’t add floor area to the finished property. Listing them separately in the assessment helps show how the rebuild figure covers the complete reinstatement process.
In the UK, access restrictions and site conditions influence commercial rebuild estimates because they can change the construction rate and the work required. A professional assessment considers these constraints alongside demolition, debris removal and external works. This ties the insured figure more closely to the actual site, rather than treating every commercial property as an uncomplicated, accessible plot.
What a commercial property rebuild cost includes
A useful rebuild figure captures all the work needed to reinstate the property, not just the new building’s walls and roof. It combines construction, labour, materials and associated work in one insurance assessment. Treat every component as part of the total: omitting a stage can leave the figure below the cost of completing the rebuild.
Start with the building itself. The assessment reflects the materials and labour required to reconstruct its structure and internal areas. A commercial kitchen, for example, has a different specification from an open-plan office. Size, layout and construction type help determine the work involved. Residential rebuild figures aren’t a reliable substitute, as commercial buildings may have different layouts and uses.
Then include the work needed to make construction possible. Demolition and debris removal clear the damaged structure; architects’ and planning costs support the design and approvals process. The estimate should also account for current building regulations, VAT and any external works. These items form part of the reinstatement total, even though they don’t appear in the finished building’s floor area.
Site conditions can change the scope. Restricted access, specialist plant machinery and external works may affect the work required and the construction rate. A property with difficult access, for instance, may need a different allowance from a similar building on an open site. Professional fees should also be included in the figure, rather than treated as an optional extra after the main construction estimate.
A calculator may present one headline figure, but its usefulness depends on the components behind that average estimate. The practical takeaway is to assess the building, clearance, fees, compliance and associated works together. This gives a clearer basis for the insured amount than relying on market value or a residential comparison. To explore cover for your premises, get help with commercial property insurance.
Just Quote Me: Commercial Property Insurance
Once you’ve worked out your property’s rebuild figure, Just Quote Me can help you consider Commercial Property Insurance. This is a useful next step when arranging cover or reviewing an existing insurance declaration, particularly if the building’s specification, condition or site constraints have changed.
The assessment gives you a clearer basis for discussing the property’s insurance needs. Just Quote Me also offers Public Liability Insurance, Employers Liability Insurance and Professional Indemnity Insurance for businesses considering these alongside property cover. Each addresses a different exposure, so the right combination depends on your business and its activities.
Request a Call back for free Expert advice.
Make your next insurance decision with confidence
Use the rebuild figure as a practical reference for property decisions, not a number to file away. When ownership, occupancy or planned works change, revisit the assumptions behind the insurance declaration. Keeping a clear record of how the figure was reached can make future discussions more focused and help everyone involved understand what the cover is intended to protect.
A considered approach to calculating the rebuild cost of a commercial property gives you a clearer starting point for discussing cover. Just Quote Me can help you consider insurance options for your business and premises, so you can move forward with greater clarity.
Get Your Free Business Insurance Quote now, and take the next step at your pace.
Frequently Asked Questions
What’s often missed?
Fixed features connected with how a business operates can be overlooked. A commercial kitchen, rooftop plant, mezzanine or specialist internal fit-out may not be apparent in a basic floor-area estimate. For example, a warehouse valuation based only on its shell could miss substantial internal installations. Record these features separately in the building information so the assessment reflects the actual premises and reinstatement scope.
How is the rebuild cost of a commercial property calculated in the UK?
A UK estimate generally starts with the building’s measured gross internal area and applies a construction rate suited to its type and specification. The figure is then adjusted for complexity, scale and site constraints. A calculator can provide an initial indication, while a formal insurance valuation can consider property-specific details. Use consistent area measurements and a clear building description so the inputs accurately represent the premises being insured.
What information is needed to estimate a commercial property’s rebuild cost?
Useful information includes measured floor area, building plans, use, construction type, condition and specification. Include details about restricted access, listed status, external areas, outbuildings and substantial tenant alterations. For example, plans showing a mezzanine or specialised fit-out can distinguish the premises from a basic unit of similar size. Clear records make it easier to identify the building features that affect its reinstatement scope.
Where can I find current UK commercial construction cost data and price indices?
Published UK construction cost ranges and indices provide useful context for changing costs. The Turner Building Cost Index reached 1530 in the first quarter of 2026, up 4.87% from the previous year. The Producer Price Index for construction materials reached 354.99 in March 2026. These measures track broader movements; they don’t replace a property-specific assessment of construction type, condition and site constraints.
How should demolition, site clearance and professional fees be included in rebuild cost?
List demolition, debris removal, site preparation and professional fees as identifiable parts of the reinstatement estimate. This makes the scope easier to understand and helps reveal whether a cost has been omitted or counted twice. For example, clearance and waste removal can be listed as separate tasks, while architects’ and planning costs relate to preparing and progressing the rebuild. Link each item to the work required at that property.
Should a commercial property rebuild valuation include external works, outbuildings and tenant improvements?
Yes, assess them if they form part of the property’s reinstatement scope. An external store, access area or fixed tenant improvement may need a separate description so it isn’t missed within the main building figure. Identify who owns or maintains each improvement and how it relates to the premises. This can help prevent the assessment from overlooking relevant features or duplicating items recorded elsewhere.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Nov 8, 2026 | Insurance
A workplace injury doesn’t automatically make an employer liable. If you’re asking who may be liable when an employee is injured at work, it depends on what caused the injury. An employer may be responsible for its own negligence or for a worker’s wrongful act closely connected to their job; in other cases, a third party may be liable.
It’s reasonable to expect an employer to take responsibility for workplace safety, but liability depends on the evidence and the connection between the injury and work duties. An employer may also be responsible for harm caused by a former employee if it occurred during their employment and was connected to their work.
This article explains employers’ safety responsibilities, how vicarious liability and the connection to job duties affect a claim, and when an employee may seek compensation. It also covers the role of third parties and employers’ liability insurance. UK employers are legally required to hold this insurance under the Employers’ Liability (Compulsory Insurance) Act 1969, according to UK Parliament.
Key Takeaways
- Liability can depend on whether an employee’s actions or omissions were connected to their work, including when the person responsible has since left the job.
- The Health and Safety at Work Act 1974 sets out employers’ duty of care towards employees, according to UK Parliament.
- A compensation claim may turn on whether the employer owed and breached a duty of care, and whether that breach caused the injury.
- Employers’ liability insurance is a legal requirement for UK employers under the Employers’ Liability (Compulsory Insurance) Act 1969, according to UK Parliament.
What is vicarious liability?
Vicarious liability can make an employer responsible for an employee’s wrongful act or omission in the course of their work. Whether it applies depends on the working relationship and how closely the conduct was connected to the job.
Employee Acts and Omissions
Vicarious liability means an employer may be held responsible for certain harm caused by an employee acting in the course of their employment. An omission can also matter, such as a worker failing to follow a work procedure while carrying out assigned duties. For a claim against an employer, the key issue is whether the act or omission was sufficiently connected to the employee’s role, not simply where it happened.
An independent contractor is generally treated differently from an employee, so an employer is usually not vicariously liable for a contractor’s wrongdoing. The employer’s own conduct may still be relevant if it contributed to the injury. The nature of the working relationship and the employer’s control over the work help distinguish these situations.
Co-worker Negligence
If a co-worker’s negligence causes an injury while they are doing their job, vicarious liability may make the employer responsible. For example, a worker could be injured because a colleague failed to use equipment safely during an assigned task. The injured worker’s claim may therefore be against the employer, rather than only the colleague who caused the accident.
An employer is not automatically liable for every incident involving staff. The conduct must be sufficiently connected to the employee’s work. Details recorded after the accident, such as what the colleague was doing and whether the task was work-related, can help establish that connection.
Third-Party Liability for Employee Negligence
A third party may be liable if someone outside the employer and its workforce caused the workplace accident. For instance, a visitor or another organisation’s worker might create a hazard that injures an employee. Responsibility depends on whose conduct caused the harm and whether an employer or employee also contributed.
An employee’s own negligence does not necessarily prevent a claim. If a worker’s actions contributed to the injury, responsibility may be shared and compensation may be reduced for contributory negligence. An employer may also be vicariously liable for a former employee if the harmful act happened during their employment and was connected to their role. Leaving the job later does not, by itself, remove that connection.
How can employers help to ensure the safety of their employees?
UK employers must take reasonable steps to protect staff, and workers also have health and safety responsibilities. Appropriate precautions depend on workplace hazards, equipment and the tasks employees perform.
Employer Health, Safety, and Welfare Duties
The Health and Safety at Work Act 1974 sets out employers’ duty of care towards employees, according to UK Parliament. Employers must take reasonable steps to protect staff’s health, safety and welfare so far as reasonably practicable. This means identifying workplace risks and taking proportionate action, not guaranteeing that injuries can never happen.
For example, a workshop using machinery should assess how workers could be injured and put suitable controls in place. Risk assessments help identify hazards, while training, safe equipment, protective gear and clear warnings can reduce exposure. Measures should reflect the work being done and be reviewed when tasks, equipment or conditions change.
Employer Health and Safety Responsibilities
Employers are responsible for making safety arrangements work in practice, not just writing policies. They should train staff to identify hazards, use equipment correctly and follow emergency procedures. Someone using machinery, for example, needs instruction suited to that equipment and their role.
Employers should also provide necessary first aid, arrange medical attention after an injury and record the incident promptly. A record of the date, time, location and circumstances can help clarify what happened. If a preventable failure caused harm, those details may be relevant to an injury or compensation claim.
Employees must follow workplace rules, use safety equipment as instructed and take reasonable care of their own health and safety. Promptly reporting a damaged guard or spill gives the employer a chance to address the hazard before someone else is hurt. Ignoring instructions or acting recklessly can contribute to an accident and affect how responsibility is assessed.
Health and safety failures can include inadequate training, unsafe machinery or hazards left unaddressed. An employer’s conduct is assessed against the risks and precautions reasonably available in that situation. Meeting safety duties can reduce negligence risks, but a breach alone does not establish every element of a civil claim. For employers reviewing how insurance fits alongside risk controls, employers’ liability cover may form part of their planning.
Close connection between wrongdoing and job duties
Vicarious liability depends on a clear link between an employee’s wrongful actions and their role. The UK Supreme Court confirmed a two-stage test on 26 April 2023. The first stage considers whether the relationship is one that can give rise to vicarious liability. The rule generally concerns an employer and employee, rather than an independent contractor. That distinction matters when establishing who may be responsible for a work accident.
The next question is whether the wrongdoing was sufficiently connected to the employee’s duties. A worker carrying out an assigned task might act carelessly or misuse their position. The employer may be liable if the connection is close enough. By contrast, personal conduct entirely unrelated to the job may fall outside the course of employment. What the person was doing and why are therefore central to assessing a claim.
The two-stage approach followed the 2020 judgment in Various Claimants v Wm Morrison Supermarkets Plc. It helps distinguish workplace wrongdoing from an incident that merely happened at work. For example, if a staff member causes an accident while performing a work duty, the job connection may be relevant. If the same member of staff acts for a personal reason unrelated to their role, the employer may not be vicariously liable.
The circumstances of the conduct may matter when assessing whether it falls within the scope of employment. The nature of the conduct and its connection to assigned duties still matter. A former employee may also create liability for a former employer if the harmful act occurred during employment and remained closely connected to the role. Leaving the workplace later does not, by itself, settle whether that connection existed.
When an employee is injured at work, the practical question is whether the evidence establishes both the relevant relationship and the connection to the job. The task being performed, the employee’s role and the circumstances of the accident can help clarify those points. These details shape whether a claim may be brought against the employer, the individual or another responsible party.
Can an employee claim compensation from their employer for a work injury?
Yes, an employee may claim compensation if the employer’s negligence caused an injury or work-related illness. The claim generally needs to establish that the employer owed a duty of care, breached it and caused the harm. For example, evidence that unsafe machinery was used despite a known hazard may help show how the breach resulted in injury. Who may be liable when an employee is injured at work depends on the facts.
Responsibility can still be assessed if the worker contributed to the accident. Failing to follow safety instructions or use required equipment may amount to contributory negligence, reducing compensation rather than automatically preventing a claim. The circumstances matter: a worker who made a mistake after inadequate training may be assessed differently from someone who ignored clear instructions. This can affect who is liable when an employee is injured at work.
UK employers are legally required to hold employers’ liability insurance under the Employers’ Liability (Compulsory Insurance) Act 1969, according to UK Parliament. Most employers in England and Wales must hold Employers’ Liability insurance with at least £5 million of cover, according to the Health and Safety Executive. This insurance helps address compensation claims for employee injury or illness connected with work.
After an accident, the incident record, photographs, witness details and medical records can help establish what happened and the injury’s effects. For example, a report noting a damaged safety guard may support an account of how machinery caused harm. An employer should refer a compensation claim to its employers’ liability insurer, which handles the claim on the employer’s behalf.
In the UK, the time limit to make an accident-at-work compensation claim is usually three years from the accident date, according to UK Parliament. Keep the date in view while gathering relevant records and considering the next step. A civil compensation judgment awards damages for injury-related pain, suffering and losses; it is not a criminal conviction.
Employers reviewing cover alongside these responsibilities can Request a Call back for free Expert advice.
Just Quote Me
Just Quote Me helps employers consider business insurance alongside their workplace responsibilities. If you’re reviewing protection after an accident or as your business changes, an independent broker can help you understand how cover options relate to your circumstances. Employers’ Liability Insurance and Public Liability Insurance address different business risks, so the relevant option depends on who may be affected and the nature of the work.
Insurance does not determine who is legally liable for an injury or replace advice about a compensation claim. It can, however, form part of a business’s wider approach to managing financial risks. Just Quote Me provides tailored insurance solutions, including Employers’ Liability Insurance, Public Liability Insurance, Professional Indemnity Insurance and Landlord Insurance.
Contact Just Quote Me to request a call back for free expert advice.
Make workplace protection part of ongoing planning
If you’re asking who may be liable when an employee is injured at work, consider how your business manages changing risks. New equipment, different tasks or changes to a worksite can affect the hazards employees face. Reviewing how these changes are managed helps keep safety arrangements practical, rather than relying on procedures that no longer fit the work.
Insurance is a separate part of business planning, not a decision about legal responsibility for an accident. Just Quote Me offers Public Liability Insurance, Employers Liability Insurance and Professional Indemnity Insurance. The relevant cover depends on your business activities and exposures, so consider whether your current arrangements still reflect the work you do and the risks your business faces.
For help considering your business insurance needs, contact Just Quote Me. Taking a considered next step can help you plan with greater clarity and confidence.
Frequently Asked Questions
What responsibilities do employers have for their employees?
Employers must take reasonable steps to protect employees’ health, safety and welfare at work. In practice, precautions should reflect the risks of each role, such as providing suitable instruction before a worker operates unfamiliar machinery. Employers should also make appropriate first aid available and arrange medical attention after an injury. Employees, in turn, must follow workplace instructions and take reasonable care.
What should I do if my employer is at fault for my accident at work?
Report the accident promptly to your employer or usual workplace contact, and explain clearly what happened. If there is no accident book, write down the details, send them to your manager or usual contact, and keep a copy. Seek medical attention so your injury is treated and recorded. Legal advice can help you understand whether the evidence supports a claim.
If an accident occurs in the workplace, who is at fault?
Fault depends on what caused the accident and whether someone’s conduct contributed to it. For example, a delivery company may be responsible if its worker leaves a hazard that injures a member of staff. An employer or employee may also share responsibility if their own negligence contributed. The location alone does not establish fault; what led to the injury matters.
Can I still claim if the accident was caused by an independent contractor?
Yes, a claim may still be possible if an independent contractor caused the accident. An employer is generally not vicariously liable for an independent contractor’s wrongdoing, but the contractor’s conduct may be relevant to a claim. The employer’s own actions also matter, particularly if it controlled the work or contributed to the hazard. The working arrangement and cause of the injury help distinguish responsibility.
Is an employer always liable for accidents in the workplace?
No. An accident at work does not automatically make an employer liable. The circumstances must establish a basis for responsibility, such as the employer’s negligence or an employee’s wrongful act sufficiently connected to work. The employee’s own conduct may also affect the outcome. A civil compensation claim is separate from criminal proceedings, so a compensation decision does not itself mean anyone has been convicted of an offence.
What compensation can you claim for a work accident?
A successful claim may result in damages for the injury’s pain and suffering and the losses it caused. Relevant losses depend on the consequences of the accident, including its effect on the injured person. If the worker was partly responsible, contributory negligence may reduce compensation. Some benefits received because of the accident may also be recovered from compensation under Compensation Recovery Unit rules.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Nov 7, 2026 | Insurance
Using a broker can make it easier to find suitable insurance, but it doesn’t guarantee the lowest premium. The pros and cons of using an insurance broker depend on the value of the advice and support you receive, as well as which insurers the broker can access and how it is paid. Brokers may receive commission, charge a separate fee, or both.
Weigh any costs against the time and effort of arranging cover yourself. A broker can compare policies from insurers on its panel and explain key differences, but the panel may not include every insurer.
This guide explains how broker remuneration works, what access to multiple insurers means in practice, and how policy guidance can help you spot gaps or overlapping cover. It also looks at support with renewals, policy changes and claims, so you can decide whether that help suits your needs.
You’ll find a practical way to compare using a broker with arranging insurance directly or choosing another route. The right option depends on how much guidance you need, how complex your cover is and what support you want after purchase.
Key Takeaways
- Understand how commission and administration fees can affect the overall value of a policy.
- Use a broker’s guidance to spot potential gaps, overlapping cover and important policy terms.
- Know what help may be available when your business changes, your policy renews or you need to make a claim.
- Weigh the convenience of access to several insurers against the limits of a broker’s panel.
Broker commissions and administration fees
Broker remuneration can affect the cost of a policy, but it doesn’t automatically make broker-arranged cover more expensive. Distinguish between commission paid by an insurer and any fee charged directly to you.
Broker Commissions
An insurer may pay a broker commission for arranging a policy. This is commonly built into the premium rather than shown as a separate charge on your bill. The amount and structure can vary between insurers and policies, so two quotes may reflect different remuneration as well as different cover. Buying directly doesn’t necessarily remove this cost or result in a lower premium.
Compare the total premium and policy terms, not just whether commission applies. Ask how the broker is paid and whether commission affects the options it recommends.
Administration Fees
A broker or insurer may charge an administration fee when a policy is purchased. Unlike insurer-paid commission, this is a separate charge to you and may appear alongside the premium. A broker may receive commission and charge an additional fee, so ask for both amounts and when they are payable before proceeding.
For example, a quote could include a premium, an administration fee and insurer-paid commission. These are different costs, so ask for a clear breakdown and whether any fee is refundable if the policy is cancelled.
Commission-Related Bias
Some insurers may offer brokers bonuses for placing business with them. If remuneration varies between insurers, recommendations could favour an option that pays more. That doesn’t mean every recommendation is biased, but it makes a clear explanation important.
Ask the broker to explain why a policy suits your needs, which alternatives it considered and whether commission or bonuses differ. Focus on cover, exclusions and total cost. Expert advice can help you understand a recommendation, but it is not a substitute for understanding it yourself.
| Option |
Who pays |
Cost to compare |
Key consideration |
| Broker commission |
Insurer |
Premium |
May vary by insurer |
| Administration fee |
Customer |
Separate charge |
Ask when it applies |
| Direct purchase |
Insurer pays no broker |
Premium and fees |
Doesn’t guarantee savings |
Choose by comparing the full amount payable, the cover provided and the broker’s explanation of its remuneration.
Expert guidance on policy terms and underwriting
A broker acts as an intermediary, helping you understand policy wording and how insurers assess risk. This guidance can save time, especially when your business activities make suitable cover less straightforward to find.
Broker Expertise
A broker’s industry knowledge can help connect your circumstances with relevant insurance policies. For example, a business planning to hire staff or expand can explain those changes when discussing its insurance needs. The broker can then consider potential risks and identify gaps in existing cover. This differs from buying directly, where you assess the fit of one insurer’s products yourself.
Advice and Recommendations
A broker can explain exclusions, conditions and optional benefits, then recommend cover based on your demands and needs. Ask how a policy would respond to a realistic event, such as damage to business property, and which exclusions could affect a claim. Clear explanations can help you make a more informed decision without having to interpret all the wording alone. Advice can also help you understand how the premium, cover and underwriting information relate.
Buying directly gives you policies from one insurer, while a comparison website shows options from participating providers. A broker can compare insurers on its panel, offer advice and explain policy details.
UK business insurance brokers are FCA-authorised and can offer general financial advice and recommendations. FCA authorisation provides regulatory oversight, while customer protections depend on the applicable rules and the activity involved.
To check a broker’s authorisation, search its name on the Financial Services Register. Customers can check a broker’s registration with the British Insurance Brokers Association and the Financial Conduct Authority to help avoid ghost brokers. These checks help establish the firm’s status.
A UK insurance broker assesses your needs, compares relevant policies and helps arrange suitable cover. It can explain terms and recommend options, rather than simply presenting one insurer’s products.
Before choosing a broker, ask which insurers it considers, how it is paid and what advice it provides. Also ask who handles policy questions and what support is available if your circumstances change.
Renewals, adjustments and claims support
A broker’s work can continue after arranging cover. Renewal reviews, policy changes and claims assistance can help keep your protection aligned with your business.
Claims Assistance
At renewal, a broker can review changes in your business and help assess whether your current level of cover still fits. Hiring staff, buying equipment or changing services may affect the risks insurers assess. A broker can help you consider renewing or exploring alternatives, then obtain quotes from insurers on its panel.
Mid-term adjustments matter too. Tell your broker about material changes, such as moving premises or adding a business activity. It can explain how the change affects your policy and help communicate relevant details to the insurer. This support focuses on keeping policy information and cover current before a loss occurs, rather than advocating during a claim.
If you need to make a claim, a broker can explain the process, help organise information and guide communications with the insurer. For example, after damage to business equipment, you may need to describe what happened and provide supporting documents. The broker can clarify what the insurer needs and help you understand the next steps.
Claims Advocacy
Claims advocacy means the broker acts as an intermediary between you and the insurer during a claim. It can help present your circumstances, explain relevant policy terms and follow up on questions. This goes beyond process guidance: advocacy focuses on representing your position in discussions with the insurer.
If a claim is disputed or delayed, a broker may help you communicate your case and negotiate with the insurer. It can explain the insurer’s response in relation to the policy wording, while the insurer makes the claim decision. Keep records of correspondence, dates and documents shared so the broker has a clear timeline to work from.
An independent broker can remain a point of contact for renewals, adjustments and claims, rather than helping only with the initial purchase. Ask what ongoing support is available and who handles each stage, from renewal quotes to claim-related questions. This helps you judge whether the support suits the complexity of your business cover.
Access to multiple insurers
A broker can approach several insurance companies on your behalf, but access usually depends on its panel. This can widen your options while leaving some insurers outside the comparison. The pros and cons of using an insurance broker are clearer when you know which markets it can approach.
Independent brokers work with more than one insurer, unlike agents who sell their employer’s products. Buying directly shows you one insurer’s policies, while a broker can compare options from insurers it works with. A comparison website also presents multiple quotes, but its results depend on participating providers and the information you enter.
Panel access has drawbacks. A broker may not approach every insurer, so a suitable policy could be outside its available options. Ask which insurers it considers and whether its recommendation reflects a comparison across its panel. This gives you a clearer view of the broker’s role as an intermediary.
Specialist access can matter when standard policies don’t fit a particular risk. Some brokers focus on niche insurance and may connect clients with specialist insurers that don’t usually sell directly to the public. For example, classic-car or kit-car cover may require a specialist market. The broker’s ability to arrange cover still depends on the insurers and products available through its panel.
Additional products can also help when a business needs several types of protection. A broker can consider related needs together, such as property and liability risks, and help identify where a policy may already include cover. This can make the overall arrangement easier to understand, rather than treating each purchase as unrelated.
A broker may be most useful for business or specialist insurance when your activities, property or risks need tailored consideration. For straightforward home or car cover, buying directly may suit you. A broker can add value when you want help comparing terms or accessing specialist markets. For businesses weighing the pros and cons of using an insurance broker, the deciding factor is whether its access and guidance address a real need.
Before proceeding, ask which insurers the broker approached, what options fell outside its panel and why its recommendation suits your needs. Get Your Free Business Insurance Quote now to explore options for your business.
Just Quote Me: Construction and Tradesman Insurance
Just Quote Me helps construction businesses and tradespeople explore cover suited to their work and circumstances. Its Construction and Tradesman Insurance can be considered alongside Public Liability Insurance, Employers Liability Insurance and Professional Indemnity Insurance.
Turn to Just Quote Me when you need help understanding which types of cover may suit your work, or when your business activities, staffing or professional responsibilities change. The aim is to make your options clearer and help you consider relevant protection, recognising that trades have different needs.
If you’re weighing broker support against arranging cover yourself, discuss the work you do, the risks you want to address and the guidance you need. Contact Just Quote Me to talk through your insurance requirements.
Make your next cover decision with confidence
Before arranging cover, write down the work your business does, the changes you expect and the risks you most need to manage. This gives your next insurance conversation a practical starting point.
Assessing the pros and cons of using an insurance broker is ultimately about choosing the level of support that suits your business. Just Quote Me offers Public Liability Insurance, Employers Liability Insurance and Professional Indemnity Insurance for businesses considering protection for different responsibilities.
Use your next conversation to explain your activities and what you want your cover to address. You can then consider relevant options with a clearer understanding of how they relate to your business needs.
Explore your options with Just Quote Me: Get Your Free Business Insurance Quote now or Request a Call back for free Expert advice. Take the next step at a pace that feels right for your business.
Frequently Asked Questions
What are the benefits of using a broker?
A broker can help match insurance to your circumstances and reduce the work of researching policies yourself. For example, a business adding a new service can discuss how the activity affects its risks before arranging cover. A broker can also explain unfamiliar terms and help identify relevant options. This is most useful when your needs involve several risks or don’t fit a standard policy neatly.
What are the disadvantages of using a broker?
A broker’s insurer panel may not include every provider, so your choices can be limited. You may also pay a separate administration or arrangement fee, depending on the broker’s charging approach. For example, someone with straightforward needs may prefer to compare a few direct quotes themselves. Consider whether the broker’s support and available options justify any additional charge.
What are the main advantages of using an insurance broker?
The main advantages are help interpreting policy details, access to more than one insurer and support tailored to your circumstances. This can be valuable if a business has several activities, such as selling products and providing advice, as these may create different risks. A broker can help organise the questions and cover options to consider, giving you a clearer basis for making a decision.
What are the disadvantages of using an insurance broker?
The main drawbacks are possible fees, a limited insurer panel and the potential for commission arrangements to influence recommendations. These are reasons to understand how the broker is paid and which insurers it approached. For instance, a quote may not represent the whole market if some providers are outside the panel. Compare the reasoning behind the recommendation and the policy terms, not just the premium.
How do UK insurance brokers get paid, and what fees or commission do they charge?
UK brokers may receive commission from an insurer, charge you a separate fee, or use both methods. Commission is often included in the premium, while an administration charge may appear separately. The amount depends on the policy and the broker’s terms. Before buying, ask for a breakdown of commission and fees, when charges apply and whether cancellation affects any fee.
Can an insurance broker help with claims, renewals and policy changes?
Yes, a broker may support you at each stage, although the help available depends on the service provided. For a claim, it can explain what information the insurer needs and assist with communications. At renewal, it can review changed circumstances, such as new premises or equipment. Tell the broker promptly about changes so it can explain whether your existing policy needs updating.
To take the next step, choose Get Your Free Business Insurance Quote now or Request a Call back for free Expert advice.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Nov 6, 2026 | Insurance
A Statement of Fact for insurance is a record of key information about you or your business and the risk being insured. To understand what a Statement of Fact for insurance means in practice, think of it as the information the insurer uses to assess the cover and set its terms. You usually don’t need to sign it physically or digitally; asking the insurer to put the cover in place is treated as accepting the facts recorded.
Check each detail carefully: inaccurate or outdated information can affect your cover and a later claim. Disclose relevant information when arranging insurance, at renewal and when circumstances change during the policy. This guide explains what the document does, when to report new or corrected information, and how non-disclosure or misrepresentation may affect a policy or claim. It also explains what accepting the recorded facts means before cover begins.
Key Takeaways
- Understand what information a Statement of Fact records and how it helps an insurer assess a risk.
- Know when to disclose relevant details, including when arranging cover, renewing it and when circumstances change.
- Learn how inaccurate or missing information may affect your policy or a future claim.
- See how Just Quote Me can help businesses looking for Factory insurance.
Consequences of non-disclosure or misrepresentation
An inaccurate Statement of Fact can affect the insurance contract and a later claim. In the United Kingdom, non-disclosure or misrepresentation may lead an insurer to reduce a claim payment, decline the claim or void the policy. For example, leaving out a relevant business activity could mean the insurer assesses a claim without a complete picture of the risk. The outcome depends on what information was missing and how it influenced the insurer’s decision.
For consumers, the Consumer Insurance (Disclosure and Representations) Act 2012 sets out a duty to take reasonable care not to make a misrepresentation. Deliberate or reckless misrepresentation can allow an insurer to avoid the policy and refuse claims. For careless misrepresentation, the remedy reflects what the insurer would have done with the correct details. If it would have charged a higher premium, it may reduce a claim payment proportionately.
An honest mistake differs from deliberately giving a false answer, but any incorrect answer still needs attention. The Consumer Insurance Act’s reasonable-care test is central: an honest error is not automatically treated as reckless conduct. If you discover that an answer was wrong, tell the insurer promptly and provide the correct information. The insurer can update the record and explain any changes to the cover.
If a Statement of Fact contains incorrect information, contact the insurer or your insurance adviser promptly. Explain the error, supply the correct details and, where possible, do this before proceeding with cover. Keep a record of the correction. This helps ensure an inaccurate answer does not remain part of the insurance contract.
If you do not check the document, errors may go unnoticed until a claim is made. For example, a business might miss an incorrect description of its activities or claims history. The insurer may then consider whether that information would have affected its decision to insure or the terms it offered. Possible outcomes include changed terms, a reduced settlement, a declined claim or an invalidated policy.
Commercial policies also carry a duty of fair presentation before a policy begins, at renewal or when certain variations are made. According to The National Archives (legislation.gov.uk), a business must disclose material circumstances it knows or ought to know, or give enough information to prompt an insurer to ask further questions. That makes reviewing the Statement of Fact and raising conflicts with previous information important before the contract is agreed.
Disclosure at policy inception, renewal and during the policy
Disclosure matters when cover begins, at renewal and whenever circumstances change. The Statement of Fact records details the insurer uses to assess the risk and set policy terms.
Information in the Statement
A Statement of Fact can record the insured activities, property, cover, drivers, excesses and policy dates. It may also include claims history, risk controls and information about the business’s finances. These details help show what the insurer understood when setting the terms. For example, a commercial policy may record whether a property is normally left unoccupied for more than 60 consecutive days.
Material Changes and Declarations
A material change is a new or altered circumstance that could affect the insurer’s assessment of the risk. Examples include a decommissioned sprinkler system, a faulty intruder alarm, or an extension or change of use at insured premises. A policyholder declaration confirms the information submitted for the insurer’s assessment. Accurate declarations help keep the policy record aligned with the actual risk.
Before cover begins, review the recorded facts and raise any inaccuracies or conflicts with a proposal form. For UK commercial insurance, the duty of fair presentation applies before entering into a policy, at renewal and before certain variations. According to The National Archives (legislation.gov.uk), a business must disclose material circumstances it knows or ought to know, or provide enough information to prompt a prudent insurer to ask further questions.
At renewal, consider what has changed since the previous policy period, including any claims or incidents. If your business has added an activity or changed premises, disclose this rather than assuming the previous details still apply. The insurer may change policy terms or conditions, decline the risk or charge a higher premium.
If information changes after cover starts, tell the insurer promptly and explain the correct details. For example, report an alarm fault or a change in how insured premises are used. The insurer may amend the premium or policy terms during the period of insurance.
A Statement of Fact usually does not require a physical or digital signature. Instructing the insurer to bind cover is treated as accepting the recorded facts. Correct errors before cover starts and report relevant changes afterwards.
Definition and purpose of a Statement of Facts
A Statement of Facts is a concise record of key information an insurer uses to assess an insured risk. It brings together details supplied by the applicant or adviser, such as the business’s activities, premises, claims history and requested cover. For example, a manufacturer’s activities and the equipment at its premises help describe the risk being insured. The document records the factual basis on which the insurer considers the policy.
The purpose is to help the insurer decide whether to accept the risk and on what terms. A business’s activities or past claims may affect the cover offered, its conditions or the premium. If the insurer and policyholder agree with the facts, the insurer uses them as a basis for the insurance contract. So the statement is more than a quote summary: it helps define the risk the insurer has agreed to consider.
A Statement of Fact differs from a proposal form in who prepares it and how the information is presented. A Statement of Fact usually sets out details gathered through an insurer’s system, a telephone conversation or an adviser. The applicant completes a proposal form by answering the insurer’s questions. Both documents can record information used to assess insurance, but they are not interchangeable.
For example, an insurer may use a Statement of Fact for a standard business package, while requiring a proposal form for a non-standard risk or when a business reaches a turnover threshold. A proposal form may allow broader declarations about processes and controls. A Statement of Fact route may instead include more restrictions and exclusions, so the questions and terms can differ.
Read the Statement of Fact alongside the proposed policy wording. For example, if the business description leaves out an activity, the stated risk may not match the work the business actually does. Raise any conflict with a proposal form before cover is bound. The insurer can then consider the correct information before the contract is agreed, rather than relying on documents that describe different risks.
Meaning and purpose of an insurance statement of fact
A Statement of Fact records information about the insured risk and what was disclosed to the insurer. Its purpose is to show the factual basis used to arrange cover, not to replace the policy wording. It may describe a business’s activities, premises, claims history or risk controls. Read it alongside the policy, which sets out the applicable cover, conditions and exclusions.
Statements of Fact can be used with car, home and business insurance, but their questions depend on the risk and policy. A motor insurance statement may ask about drivers and motoring history; a home statement may record facts about the property. A business example might include whether premises are normally unoccupied for more than 60 consecutive days, or whether the policyholder reported losses or incidents during the previous 5 years. These are examples, not universal questions for every policy.
The document can also help clarify what the insurer knew if questions arise during a later claim. It records information presented when cover began and the factual basis on which the insurance contract was formed. However, it may not include every material fact relevant to the policy. For example, a statement describing a workshop may not detail every activity carried out there, so wider disclosures and the policy terms also matter.
If you believe an insurer has handled a Statement of Fact unfairly, make a formal complaint through the insurer’s complaints process. Identify the disputed entry, provide the correct information and explain how the issue affected your cover or claim. Keep copies of the statement, relevant correspondence and the response so your complaint clearly sets out what happened.
The key distinction is that a Statement of Fact records disclosed information, while the policy explains the agreed cover. An accurate record helps both sides understand the risk being insured. For example, if a business’s activities change, its previous description may no longer reflect the current risk. Read the statement alongside the policy and any proposal form, rather than treating it as a complete account of every term.
Just Quote Me: Factory insurance
Just Quote Me helps businesses arrange Factory Insurance and present the information insurers need to assess their risk. This can be useful when insuring factory premises, machinery or business activities and you want support providing accurate details.
A clear Statement of Fact helps ensure the insurer’s record reflects the risk being insured. Relevant details may include the factory’s activities, premises and claims history. Tell the insurer about changes so the information remains accurate. Just Quote Me also offers Public Liability Insurance and Employers Liability Insurance for businesses that need these types of cover.
Request a Call back for free Expert advice about your Factory insurance requirements.
Make your next insurance decision with confidence
Use the Statement of Fact as a prompt for a practical conversation about the cover you need. Consider whether the information still reflects your circumstances and what you want the policy to protect. When deciding what a statement of fact for insurance means for your next policy, focus on how clearly the record describes your particular risk, not just whether the paperwork is complete.
For business cover, the relevant questions depend on the activity and exposure. Just Quote Me offers Public Liability Insurance, Employers Liability Insurance and Professional Indemnity Insurance. You can discuss which type of cover relates to your business and what information may matter to the insurer’s assessment.
Take the next step at a pace that suits you: Get Your Free Business Insurance Quote now, or Request a Call back for free Expert advice to discuss your insurance needs and understand your options.
Frequently Asked Questions
Do I need to sign a Statement of Fact to make it legally binding?
A physical or digital signature usually isn’t required. Instructing the insurer to bind cover is treated as acceptance of the recorded facts, so correct errors before asking the insurer to start the policy. For example, if the document names the wrong premises, raise the discrepancy before cover is arranged. The policy wording and the insurer’s terms remain important parts of the insurance contract.
Why does Statement of Facts (SoF) exist?
A SoF gives the insurer a record of information used to assess an application and decide policy terms. It can help clarify what was disclosed if a later claim raises questions about the risk. For instance, a record of a business’s activities can show what work the insurer considered. It also gives the policyholder a chance to spot mismatches before cover proceeds.
What happens if I do not disclose one?
If you leave out relevant information, the insurer’s response may depend on the circumstances and type of policy. For example, a business that omits a significant change in its operations could face a claim decision based on an incomplete picture of the risk. Possible outcomes include changed terms, a reduced payment, a declined claim or an avoided policy. Deliberate or reckless misrepresentation can have serious consequences.
What is a “material fact” and why is it so important?
A material fact is information that could influence a prudent insurer’s decision to insure a risk or the terms offered. For a business, a change in premises use or relevant claims history could affect that assessment. Materiality matters because the insurer may have priced, limited or excluded cover differently if it had known the information. Disclose relevant facts clearly instead of relying on assumptions.
What is considered “Material Information” when checking these documents?
Material information is detail that could affect the insurer’s view of the risk. Depending on the policy, it may include business activities, claims or incidents, security arrangements, property use, or relevant information about directors or partners. For example, an alarm fault or a new activity at insured premises may change the risk picture. Review the questions asked and raise relevant details that need clarification.
What is a statement of fact in UK insurance?
A statement of fact for insurance in the UK records information about an insured risk for the insurer’s assessment. The format and questions vary by policy: a motor policy might record named drivers, while a business policy describes its operations. It does not replace the full policy wording. Read both documents together to understand the recorded information and the cover terms.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.