by jqm | Jul 31, 2026 | Insurance
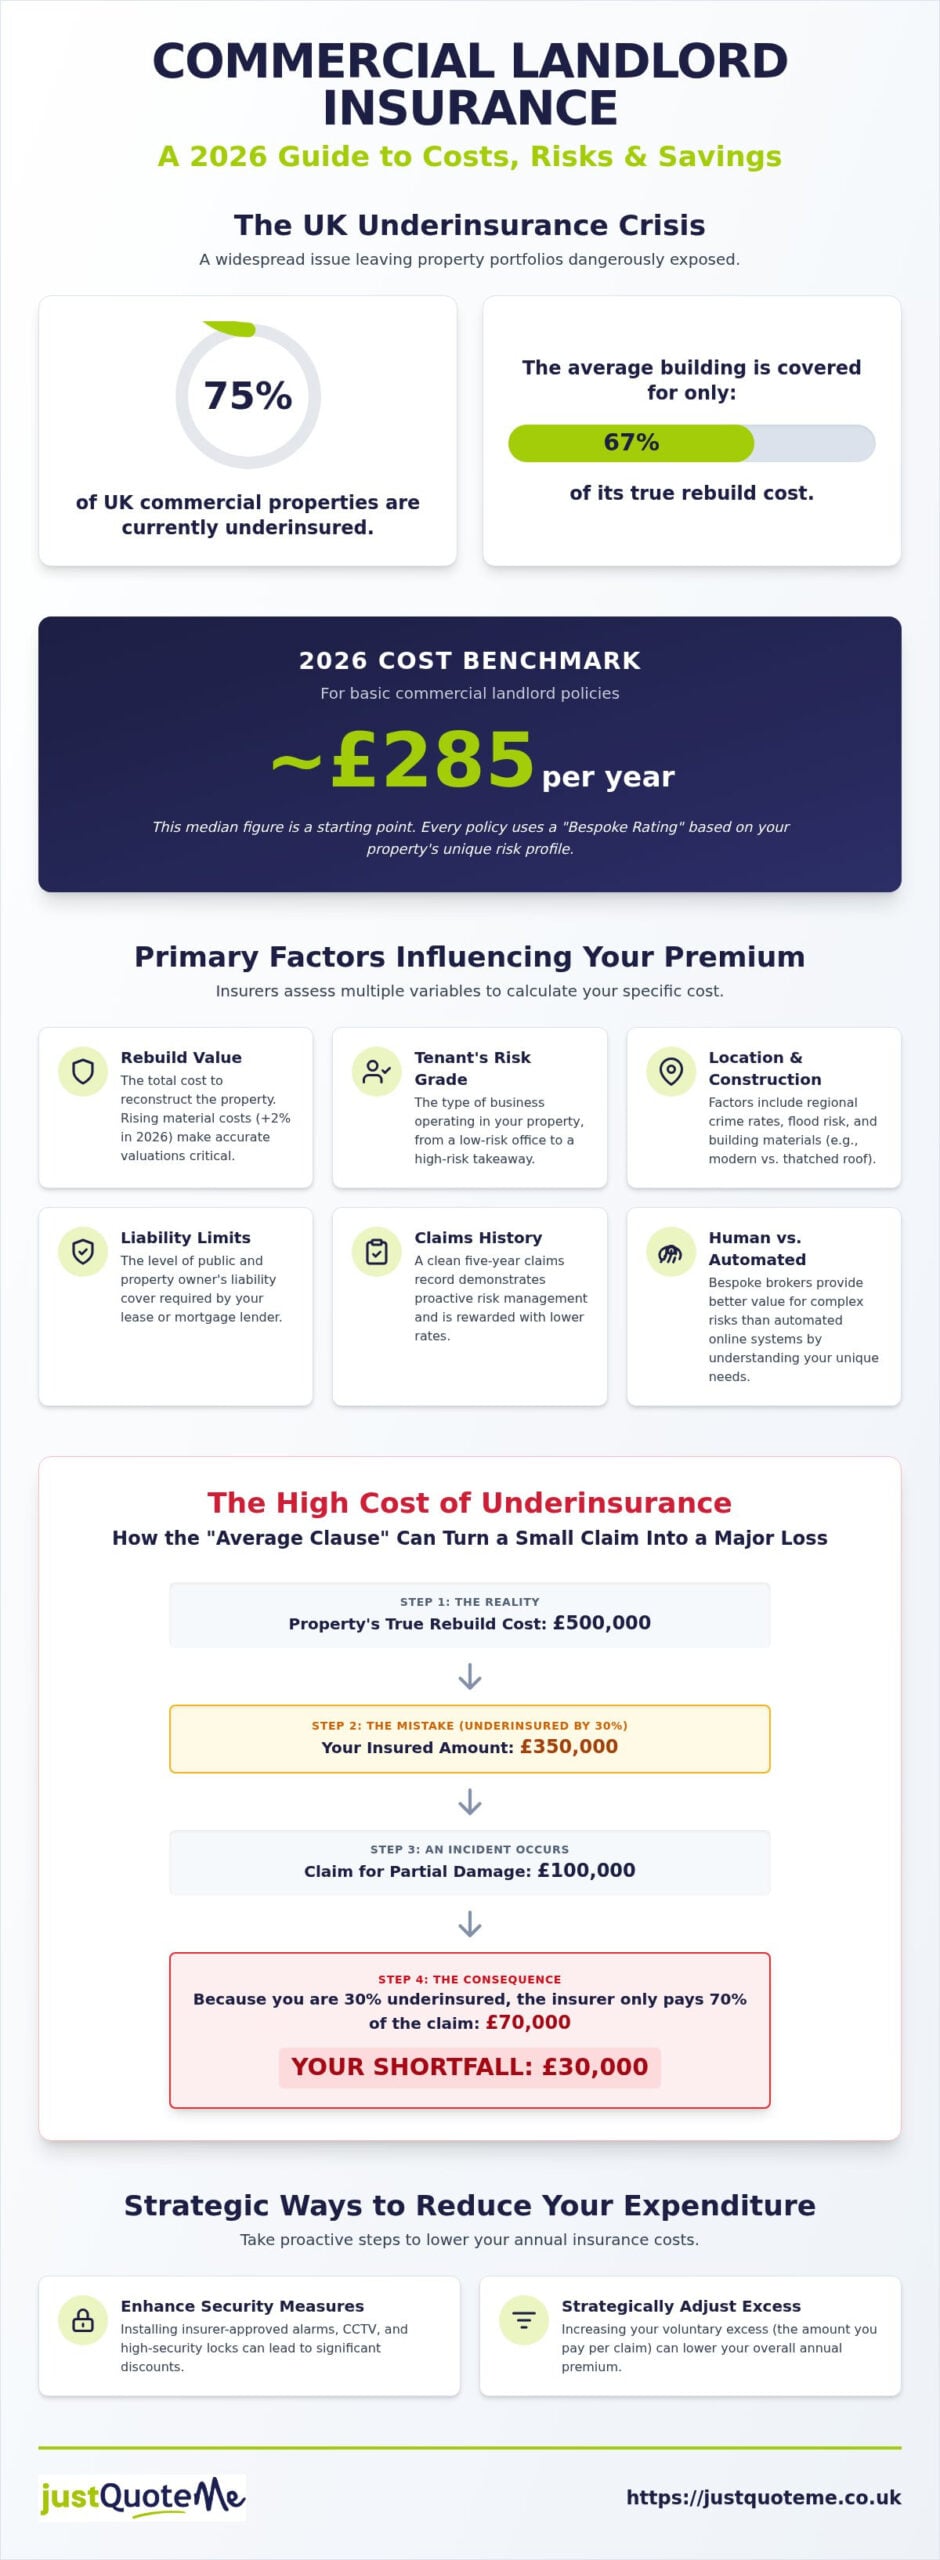
Did you know that an estimated 75% of UK commercial properties are currently underinsured, with the average building covered for only 67% of its true rebuild cost? In a landscape where construction material prices remain volatile and the Renters’ Rights Act 2025 has introduced new complexities for property owners, managing your commercial landlord insurance cost requires more than just a quick comparison search. You’ve likely felt the pressure of rising premiums and the confusion that comes when a simple change in tenant type, like moving from a retail unit to a takeaway, drastically alters your risk profile.
It’s a challenge to maintain a profitable portfolio while ensuring you aren’t left vulnerable to a significant financial shortfall. This guide provides a straightforward look at the factors driving 2026 pricing and offers pragmatic advice on how to secure bespoke coverage. We’ll examine the impact of current legislative changes, explain why accurate reinstatement values are vital, and show you how to find an expert broker who understands the nuances of your specific sector without relying on automated, impersonal systems. By the end of this article, you’ll have a clear strategy for protecting your investment while keeping your overheads under control.
Key Takeaways
- Understand the 2026 price benchmarks and why commercial premiums are structured differently than standard residential policies.
- Identify how specific tenant activities and property construction types, such as thatched roofs or takeaways, influence your commercial landlord insurance cost.
- Learn to balance essential buildings cover with appropriate liability limits to protect your portfolio against evolving legal requirements.
- Discover actionable methods to reduce your annual expenditure through enhanced security measures and strategic excess adjustments.
- Explore why a human-centric, bespoke brokerage approach provides better value for complex property risks than automated online systems.
Understanding Commercial Landlord Insurance & 2026 Cost Benchmarks
Commercial landlord insurance acts as a bespoke shield for non-residential assets, protecting your investment from risks that standard policies simply aren’t built to handle. Unlike residential cover, these policies are tailored to the specific operational demands of business premises. When calculating the commercial landlord insurance cost, insurers move away from generic formulas. Instead, they apply a “Bespoke Rating” where every property is treated as a unique risk profile based on its use, construction, and location. In 2026, the median cost for a basic policy with no optional extras is averaging approximately £285 per year. However, this figure is a broad benchmark; your actual premium depends heavily on your sector and the specific activities occurring within your property.
Understanding property insurance fundamentals is essential for any portfolio owner. While some basic policies start as low as £14.25 per month for simple building and liability cover, most professional landlords require more comprehensive protection. If you are managing a diverse portfolio, exploring commercial property insurance options with an independent broker helps clarify these bespoke ratings.
While the £285 median sits as a general guide, several factors shift this benchmark for 2026:
- The total rebuild value of the structure.
- The specific trade or “Risk Grade” of the tenant.
- The regional crime rate and environmental risks like flooding.
- The level of property owner’s liability required by your mortgage lender or lease.
Commercial vs. Residential: The Pricing Gap
The price difference between residential and commercial cover is driven primarily by risk exposure. A private home has predictable, low footfall. A retail shop or office block, however, sees a constant stream of employees, customers, and delivery drivers, which significantly increases liability risks. Commercial leases are also more complex, often involving Full Repairing and Insuring (FRI) terms. While these terms allow you to recover premiums from tenants, the legal responsibility for the structure remains with you. It’s also vital to remember that standard residential policies strictly exclude any commercial activity. Using the wrong policy won’t just lead to a rejected claim; it leaves your entire asset exposed.
The Cost of Underinsurance in 2026
The Primary Factors Influencing Your 2026 Premiums
While industry benchmarks provide a starting point, your specific commercial landlord insurance cost is determined by a combination of physical and operational variables. Insurers don’t just look at the building; they evaluate the likelihood of a claim based on how the property is constructed and who occupies it. For example, a modern office block built with fire-resistant materials presents a much lower risk than a thatched pub. In regions like Staffordshire, Victorian period features are common. While these add character and value, they often require specialist materials and heritage-skilled labour for repairs, which naturally increases the premium. A “clean” five-year claims record is your strongest asset here; it demonstrates a proactive approach to maintenance and risk management that underwriters reward with lower rates.
The relationship between landlord and tenant also dictates how costs are allocated. The RICS Code for Leasing Business Premises outlines best practices for these negotiations, including insurance responsibilities. Even if you recover the premium from your tenant, the “Risk Grade” assigned to their specific trade remains the primary pricing driver. If you’re managing multiple units, you can consolidate your risks into a single portfolio policy to simplify administration and potentially secure bulk discounts.
Tenant Profiles: From Low to High Risk
Insurers categorise tenants based on “Hazard Grades.” An accountancy firm or a low-footfall office is a low hazard. Conversely, “High Hazard” tenants like restaurants, workshops, or businesses using heavy machinery carry higher premiums due to fire and liability risks. Shop Insurance rates reflect high public footfall, which increases the chance of a liability claim. Additionally, unoccupancy is a major factor. If a property sits empty for more than 30 to 60 consecutive days, standard cover is often restricted, and premiums can rise by 30% to 80% to account for the increased risk of vandalism or undetected damage.
Regional Insights: Staffordshire and the West Midlands
Local geography and economic factors in Stafford, Stone, or Newcastle-under-Lyme directly influence your quote. Insurers analyse regional crime statistics and flood maps to determine the baseline risk for your postcode. In the West Midlands, rebuild labour costs are currently influenced by a 2% rise in construction material prices as of early 2026. Using a Commercial Insurance Broker in Staffordshire gives you an advantage, as local experts understand these regional price fluctuations better than a generic online aggregator. This regional knowledge ensures your rebuild value is accurate, protecting you from the “Average Clause” penalties mentioned earlier.
Essential vs. Optional Cover: Building Your Policy
Constructing a robust policy starts with buildings insurance, which covers the physical structure and permanent fixtures against risks like fire, flood, and subsidence. Given that construction material costs were 2% higher in early 2026 compared to the previous year, ensuring your sum insured reflects current prices is vital. Beyond the bricks and mortar, you should consider contents insurance if you provide furniture or equipment within the premises. While your tenants are responsible for their own stock, your assets remain your financial burden. Property owners’ liability is another cornerstone, providing a safety net if a third party is injured on your premises. While £2 million or £5 million limits are common, many modern commercial contracts now require £10 million to meet corporate compliance standards.
If you employ anyone directly to manage your portfolio, such as cleaners, gardeners, or maintenance contractors, employers liability insurance is a strict legal requirement. The statutory minimum is £5 million, though most policies provide £10 million as standard. Failing to have this cover in place can result in fines of up to £2,500 for every single day you operate without it. These core protections form the basis of your commercial landlord insurance cost, but the true value of a policy often lies in the optional extensions that safeguard your cash flow.
Loss of Rent and Business Interruption
Loss of rent cover is essential if a claim makes your building untenantable. It ensures you continue to receive income while repairs are underway. In 2026, the “Indemnity Period”—the duration the insurer will pay out—is more critical than ever. With ongoing labour shortages and planning delays, a standard 12-month period is often insufficient for major reconstructions. Opting for 24 or 36 months provides the necessary breathing room to restore your asset without losing your primary revenue stream. You can find more detail on these financial safeguards within our guide to commercial property insurance.
Specialist Add-ons: Cyber and Legal Expenses
Modern risks require modern solutions. Many landlords now include cyber insurance to protect sensitive digital records and rental payment systems from data breaches. Furthermore, the Renters’ Rights Act 2025, which took effect in May 2026, has abolished “no-fault” evictions. This makes legal expenses cover a pragmatic addition to handle the increased complexity of tenant disputes or eviction proceedings. While these add-ons increase your initial premium, they prevent catastrophic out-of-pocket expenses that far outweigh the modest increase in your annual outlay.
Strategic Ways to Reduce Your Commercial Insurance Expenditure
Controlling your commercial landlord insurance cost doesn’t have to be a passive process. While market rates fluctuate, you have several practical levers to pull that can significantly lower your annual premiums. One of the most effective methods is improving physical security. Installing locks that meet British Standard BS3621 or fitting LPCB-approved alarm systems reduces your risk rating in the eyes of underwriters. Another immediate tactic is adjusting your voluntary excess. By agreeing to pay a larger share of a smaller claim, you reduce the insurer’s potential payout and administrative burden, which they often reward with a lower base rate. It’s a simple trade-off that benefits landlords with a strong cash reserve.
Accuracy in your property data also prevents wasted expenditure. Professional rebuild valuations should be conducted every three years to ensure your sum insured matches current market realities. This prevents you from over-insuring and paying for coverage you don’t need, while also protecting you from the underinsurance penalties discussed in earlier sections. If you manage several units, consolidating your portfolio into a single “Multi-Property” policy is often more cost-effective than holding individual contracts. This approach triggers bulk discounts and significantly reduces the time you spend on administrative tasks. To find the most competitive rates for your specific property mix, get a bespoke quote from our specialist team today.
Proactive Risk Management
Insurers prefer “quality risks” that demonstrate active management. Documenting your regular maintenance schedules, such as annual roof inspections or gutter cleaning, proves you are preventing minor issues from escalating into major claims. Partnering with a professional team like Shellmar Construction Ltd for routine maintenance and structural repairs ensures your property remains in peak condition. Documented health and safety checks make your property much more attractive to underwriters during the negotiation phase. Rigorous fire safety compliance and up-to-date electrical testing certificates directly lead to lower insurance costs by minimising the probability of a total loss. A well-maintained property isn’t just a better asset; it’s a cheaper one to protect.
The Power of Choice: Reviewing Your Renewal
Auto-renewal is often the most expensive way to insure a commercial property. It’s a passive choice that rarely accounts for new market entries or changing risk appetites among insurers. You should start the quote process at least 30 days before your current policy expires. This window gives a broker enough time to “market” your risk to a broad network of underwriters, creating competition for your business. Unlike automated systems that use rigid algorithms, a human broker can highlight the specific improvements you’ve made to your property, ensuring you aren’t penalised by generic sector ratings. This personalised approach is the most reliable way to secure a deal that reflects the true value of your portfolio in 2026.
Finding the Best Value with a Bespoke Broker Quote
Automated quote engines are built for speed, not nuance. While they provide a quick number for a standard house, they often struggle to calculate a precise commercial landlord insurance cost for complex business assets. If your property features a non-standard construction or houses a high-hazard tenant, an algorithm will often default to a higher premium to cover its own uncertainty. An independent broker can present your risk directly to specialist underwriters who don’t deal with the general public. These “broker-only” markets are where the most competitive rates are found, as they allow for manual adjustments based on the specific risk-management steps you have taken.
Just Quote Me brings 30 years of industry experience to your property portfolio. We don’t just input data into a system; we advocate for your investment. By managing the complex administrative burdens, we ensure you’re protected without being overcharged by generic pricing models. This human-centric approach is vital in a market where 75% of properties are currently underinsured. We help you verify your data so that your policy is accurate and your claims are paid in full. Having a steady hand to manage these nuances means you can focus on managing your tenants while we handle the fine print.
The Just Quote Me Difference
Being an independent broker means we work for you, not the insurance companies. We have deep roots in Staffordshire, providing regional expertise across Stone, Stafford, and Newcastle-under-Lyme. This local knowledge is a mark of quality that national call centres can’t replicate. As an FCA-authorised firm, we maintain the highest professional standards, ensuring your commercial property insurance is handled with integrity and precision. We understand the local economy and the specific challenges facing West Midlands landlords in 2026, from fluctuating rebuild costs to evolving tenant demands.
Next Steps: Securing Your 2026 Protection
Securing your portfolio doesn’t have to be a slow or frustrating process. To get started, gather your most recent rebuild valuations and details of your current tenant activities. Knowing exactly what your tenants do on-site allows us to categorise your “Risk Grade” accurately, which is the most effective way to lower your commercial landlord insurance cost from the outset. Once you have this information, our specialist team can quickly market your risk to our broad network of top UK insurers. This proactive approach ensures you’re ready for renewal well before your current policy expires.
Get Your Free Business Insurance Quote now
Securing Your Portfolio for 2026 and Beyond
Managing your commercial property assets involves balancing robust protection with sustainable profitability. Achieving a competitive commercial landlord insurance cost depends on precise risk assessment and proactive maintenance. Whether you’re navigating the complexities of the Renters’ Rights Act 2025 or accounting for the 2% rise in material costs seen in early 2026, accuracy remains your best defense against financial shortfall. Relying on automated systems often leads to generic pricing; a bespoke approach ensures you pay only for the protection you actually need.
Just Quote Me provides the human-centric expertise required to navigate these market shifts. With over 30 years of industry experience, we act as your dedicated advisor in Staffordshire and beyond. Our independent status allows us to access a broad network of top UK insurers to find the specific cover your portfolio requires. We manage the administrative heavy lifting so you can focus on your business. Protecting your investment with reliable, FCA-authorised advice ensures your long-term success in an evolving market. Take the first step toward better protection by choosing Just Quote Me for your insurance needs.
Get Your Free Business Insurance Quote now
Request a Call back for free Expert advice
Frequently Asked Questions
Is commercial landlord insurance a legal requirement in the UK?
No, commercial landlord insurance isn’t a statutory legal requirement in the UK, but it’s almost always a contractual necessity. Most commercial mortgage lenders insist on comprehensive cover as a condition of your loan to protect their financial interest. Additionally, standard Full Repairing and Insuring (FRI) leases usually require the landlord to maintain buildings insurance for the protection of the asset.
How is the rebuild cost of a commercial property calculated in 2026?
The rebuild cost is calculated by estimating the total expense of reconstructing the building from scratch using current labour rates and material prices. In early 2026, this must account for a 2% rise in construction material costs compared to the previous year. This figure must include debris removal, professional fees, and compliance with modern building regulations rather than the market value of the property.
Does commercial landlord insurance cover my tenants’ belongings?
No, your policy won’t cover the furniture, stock, or equipment owned by your tenants. Tenants are responsible for securing their own contents insurance to protect their business assets. Your policy focuses on the building structure, landlord-owned fixtures, and your specific liability as a property owner.
What happens if my commercial property is left unoccupied?
Standard cover is usually restricted after a property has been empty for 30 to 60 consecutive days. During this period, you may need specialist unoccupied property insurance, which can increase your commercial landlord insurance cost by 30% to 80%. These policies often require regular inspections and specific security measures to manage the increased risk of vandalism or undetected damage.
How much does property owners’ liability insurance cost on its own?
Liability insurance is rarely sold as a standalone product for commercial landlords and is typically bundled into a comprehensive policy. The price is influenced by the required indemnity limit, which usually ranges from £2 million to £10 million. Higher limits are often mandated by corporate tenants or specific local authority contracts to meet their compliance standards.
Can I get a discount for insuring multiple commercial properties?
Yes, consolidating your portfolio into a single multi-property policy often results in significant discounts. Insurers prefer the reduced administrative burden of a single contract and often apply bulk rate reductions. This approach also simplifies your renewals and ensures there are no gaps in coverage across your different assets.
Does landlord insurance cover legal fees for tenant evictions?
Legal expenses cover can be added to your policy to handle the costs of eviction proceedings. This has become increasingly important following the Renters’ Rights Act 2025, which abolished “no-fault” evictions in May 2026. Having this protection helps manage the complex legal requirements and potential court costs associated with modern tenant disputes.
Why has my commercial insurance premium increased so much this year?
Several economic factors are driving up the commercial landlord insurance cost in 2026. Claims inflation, driven by higher labour costs and a 2% increase in construction materials, means insurers must charge more to cover potential rebuilds. Additionally, the new regulatory landscape and the high rate of underinsurance across the UK have led underwriters to adjust their pricing models to reflect increased risk.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Jul 30, 2026 | Insurance
Did you know that an estimated 400,000 UK landlords are currently operating without any insurance? In a year defined by the most significant rental reforms in three decades, including the abolition of Section 21 and the launch of the mandatory Private Rented Sector Landlord Ombudsman, this lack of protection is a high-stakes gamble. We understand that 52% of landlords now cite these legislative changes as their biggest challenge, often leading to valid concerns about rising premiums and the increased risk of legal claims.
It’s easy to feel overwhelmed by the transition to periodic tenancies and the new Housing Health and Safety Rating System standards. This guide provides landlord liability insurance explained in clear, pragmatic terms to help you navigate these shifts. You’ll master the essentials to protect your property portfolio from costly legal claims and negligence suits while learning to distinguish between basic buildings cover and vital liability protection. We will show you how to choose the right cover limits and implement risk-lowering strategies to keep your 2026 costs manageable. If the administrative burden of new regulations feels heavy, let Just Quote Me simplify your protection so you can focus on your tenants with confidence.
Key Takeaways
- Master your statutory obligations under the Occupiers’ Liability Act to understand exactly when you are legally at fault for an accident on your property.
- Identify the primary causes of third-party claims, such as slips and falling masonry, to build a more resilient risk management strategy for your portfolio.
- Get landlord liability insurance explained so you can confidently distinguish between essential liability cover and standard buildings insurance.
- Learn why professional advice and staff-related risks require specific add-ons that standard liability policies typically exclude.
- Discover why a bespoke policy from an independent broker offers more reliable security for your property assets than a generic, automated quote.
What is Landlord Liability Insurance? UK Definitions and Essentials
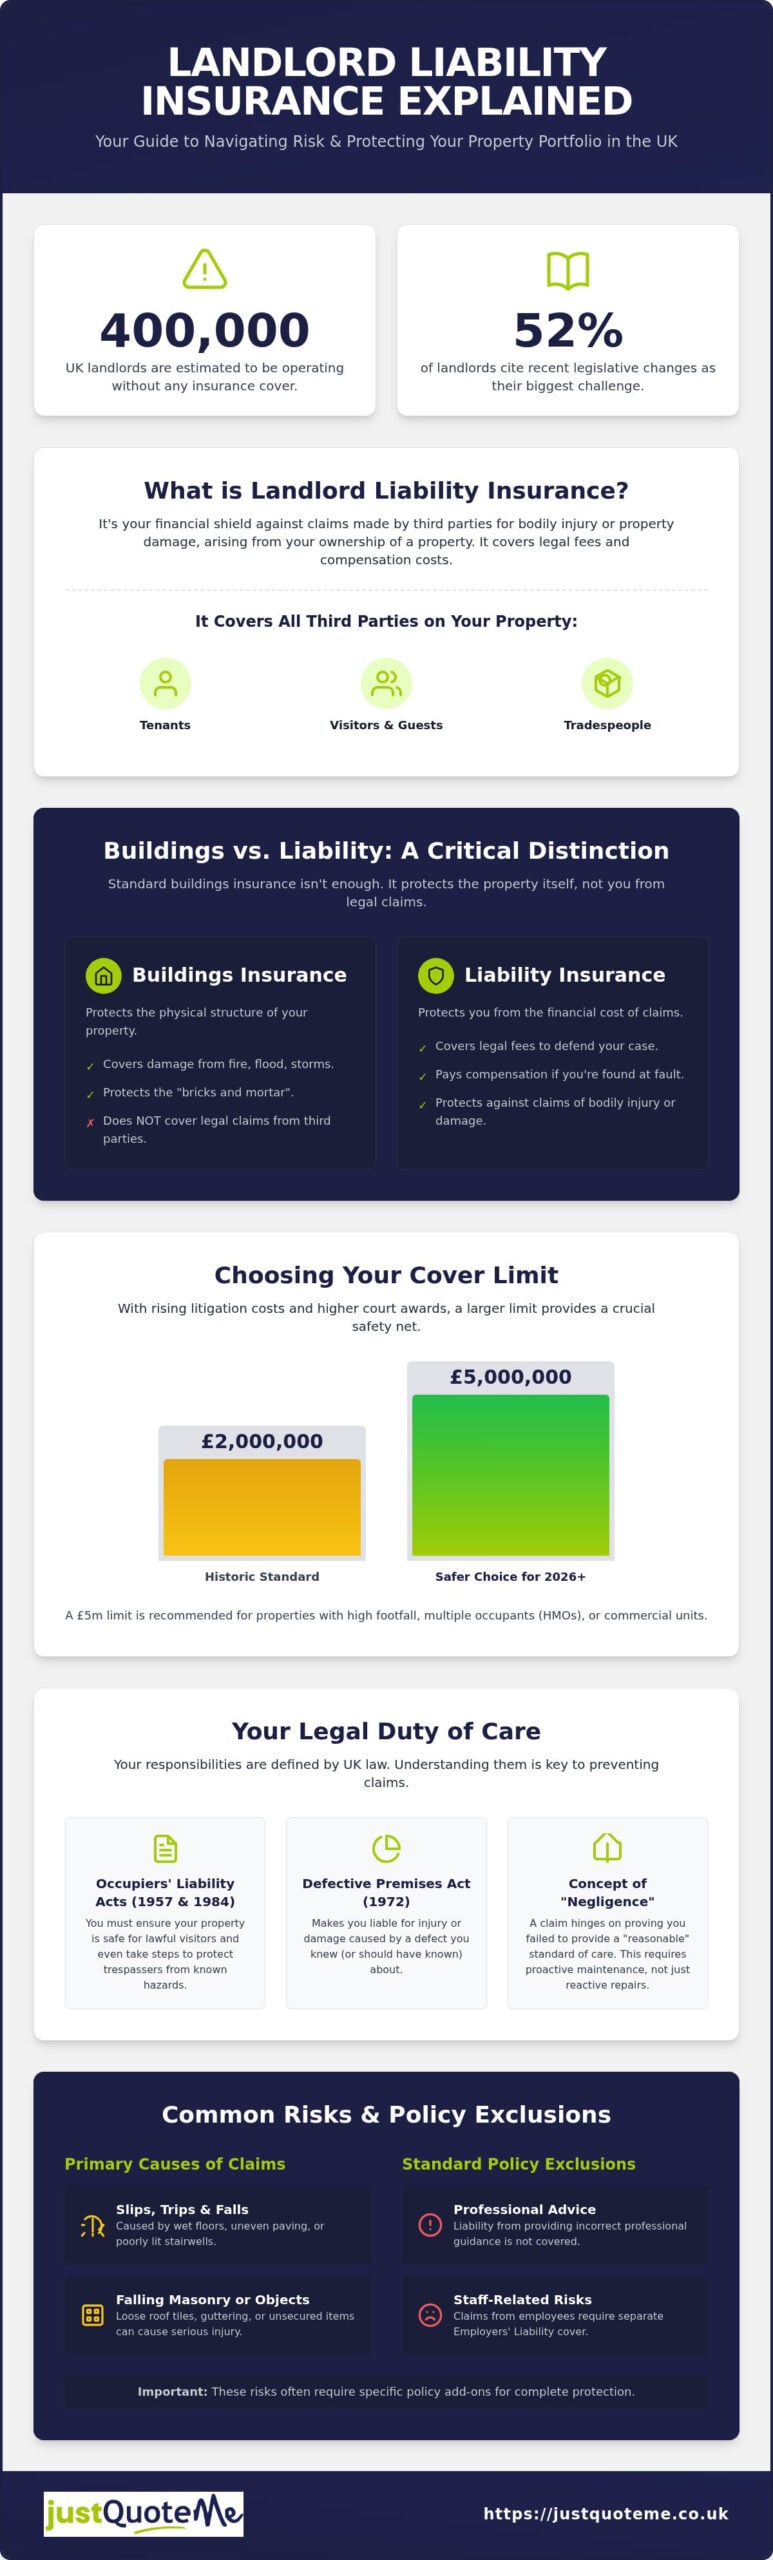
Getting landlord liability insurance explained is the first step toward a secure property portfolio. This cover is your financial shield against claims made by third parties for bodily injury or property damage. While many people think only of their tenants, a “third party” actually includes anyone who steps foot on your property. This means visitors, tradespeople, and even random passers-by are covered if your building causes them harm.
You have a legal duty of care to keep your premises safe. If you fail in this duty, the costs can be devastating. Many property owners mistakenly believe their standard buildings insurance is enough. It isn’t. Buildings insurance protects the bricks and mortar from fire or flood, but it won’t pay for a solicitor or a compensation settlement if a tenant sues you for a slip. A robust residential letting insurance policy should include liability cover to bridge this gap. Even if a claim is eventually dropped, the legal fees to defend your reputation can reach thousands of pounds; your policy covers these costs so you don’t have to.
Property Owners’ Liability vs. Public Liability
In the insurance industry, we typically refer to this as Property Owners’ Liability. It’s a specific form of public liability insurance designed for the unique risks of landlords. While a shop needs cover for customers tripping over stock, a landlord needs cover for structural failures or maintenance issues. If you own a freehold property, you’re responsible for the whole site. If you own a leasehold flat, you’re responsible for everything inside your front door. Just Quote Me to find a policy that matches your specific ownership structure.
Minimum Cover Limits: £2m vs. £5m
The Legal Framework: Understanding Negligence and Your Duty of Care
When we have landlord liability insurance explained, the conversation often centers on policy documents, but the true foundation is built on UK statutory law. As a property owner, your legal responsibilities are primarily governed by the Occupiers’ Liability Act 1957 and the Occupiers’ Liability Act 1984. These acts dictate that you must take reasonable care to ensure your property is safe for anyone entering it. While the 1957 Act covers lawful visitors like tenants and delivery drivers, the 1984 Act surprisingly extends a limited duty of care even to trespassers. If a hazard is known to you and you fail to provide adequate warnings or repairs, you could be held liable for injuries sustained by someone who shouldn’t even be on the premises.
Negligence is the pivot point of any liability claim. In the eyes of the law, negligence is not merely an accident; it is a demonstrable failure to maintain the standard of care that a “reasonable” person would provide. This concept of reasonable care is what keeps many landlords awake at night. It requires you to be proactive rather than reactive. If you’re unsure how these legal standards apply to your specific portfolio, seeking professional landlord insurance advice can help clarify your individual risk profile.
Statutory Duties and the Landlord’s Responsibility
The Defective Premises Act 1972, specifically Section 4, places a heavy burden on landlords who have a duty to repair or maintain a property. If a defect results in injury or damage, and you knew (or ought to have known) about it, the law sits firmly on the side of the claimant. This is why administrative compliance is inseparable from legal safety. For instance, annual gas safety checks are a cornerstone of UK government legislation regarding rental properties. If a landlord neglects to perform a mandatory inspection and a tenant suffers harm from a faulty boiler, that missed paperwork serves as primary evidence to prove negligence in court.
Proving Negligence: The Three-Step Test
For a compensation claim to succeed against you, the claimant’s legal team must satisfy a three-step test. This framework determines if you are financially responsible for the incident:
- Duty of Care: It must be established that you owed a duty to the person involved. For landlords, this is almost always a given regarding tenants and visitors.
- Breach of Duty: The claimant must prove you failed to uphold that duty through action or, more commonly, inaction.
- Causation: It must be proven that your specific breach of duty directly caused the injury or loss.
Understanding this framework is essential when having landlord liability insurance explained because your policy is designed to defend you against these specific legal hurdles. Whether a claim is legitimate or frivolous, the legal framework requires a robust defense to protect your assets from the high costs of UK litigation.
Common Liability Claims and Risk Management for Landlords
When you have landlord liability insurance explained, you quickly realize that most claims aren’t the result of catastrophic structural failures. Instead, they usually stem from small, overlooked maintenance issues that spiral into expensive legal battles. Slips, trips, and falls remain the most frequent cause of liability claims in the UK. A loose carpet on a staircase or an uneven paving slab in the garden can lead to serious injury. If a court decides you failed to address these hazards, the compensation payouts for medical care and loss of earnings can be substantial.
External hazards are equally risky. Falling objects, such as loose roof tiles or crumbling chimney stacks, pose a direct threat to passers-by and neighbours. Similarly, faulty wiring and poor fire safety measures are major triggers for litigation. Keeping your Electrical Installation Condition Report (EICR) up to date is your best defense. These certificates prove you’ve taken proactive steps to ensure the property is safe, making it much harder for a claimant to prove negligence. You must also manage “silent killers” like carbon monoxide and Legionella. Failing to install required detectors or neglecting Legionella risk assessments can lead to criminal prosecution as well as civil liability claims.
Mitigating Risk to Protect Your Premiums
Your best defense against a negligence suit is a meticulous paper trail. Under the Defective Premises Act 1972, you’re responsible for defects you ought to have known about. Documented regular property inspections are essential. By keeping a log of every repair, from the date the issue was reported to the moment it was fixed, you create evidence of “reasonable care.” Integrating a robust maintenance plan with comprehensive residential letting insurance ensures that you’re protected both physically and financially. This proactive approach doesn’t just lower your risk; it helps keep your insurance premiums competitive by demonstrating to insurers that you’re a low-risk client.
What to Do if a Claim is Made Against You
If an accident occurs on your property, your natural instinct might be to apologize. However, you must follow the “No Admission of Liability” rule. Apologizing or admitting fault at the scene can prejudice your insurer’s ability to defend you later. Instead, focus on gathering evidence immediately. Take clear photos of the area, the hazard, and any relevant signage. Secure witness statements and record the incident in your own logs. In the UK, a typical liability claim begins with a “Letter of Claim” from the claimant’s solicitor. Once you receive this, don’t respond yourself. Forward it immediately to your broker so their legal team can take over the communication. This structured response is a vital part of having landlord liability insurance explained, as it ensures your policy remains valid throughout the litigation process.
Standard Exclusions: What Landlord Liability Does Not Cover
Having landlord liability insurance explained involves more than just listing what it covers; you must also understand the boundaries. While this policy is vital for accidents and injury claims, it isn’t a universal safety net for every risk associated with property management. For instance, liability cover focuses on physical harm or property damage. If you provide professional advice to a tenant that leads to their financial loss, you’d need Professional Indemnity Insurance instead. Additionally, no policy will protect you from the consequences of your own intentional acts or criminal behaviour. If a landlord is found to have deliberately caused harm or ignored safety laws with malicious intent, the insurer will void the claim.
Another critical distinction is the difference between sudden accidental damage and gradual wear and tear. If a roof tile falls and hits a visitor because of a freak storm, your liability cover typically responds. However, if that same tile falls because the roof has been neglected for twenty years, the insurer may argue that the incident was preventable through basic maintenance. Wear and tear is a standard exclusion across the industry because insurance is designed to cover the unforeseen, not the inevitable results of aging buildings. To ensure your policy aligns with your property’s actual condition, you can compare landlord insurance options with our expert team.
The Employers’ Liability Trap
Many landlords fall into a legal trap when they hire help for their properties. If you employ a regular gardener, cleaner, or maintenance person, you are likely legally required to hold Employers’ Liability Insurance. Standard landlord liability only covers third parties, not people working under your direction. The penalties for failing to have this cover are severe, with the Health and Safety Executive (HSE) able to fine you up to £2,500 for every day you are uninsured. In a domestic property setting, the threshold for employment is typically met when you exert control over how, when, and where the work is performed, even if the individual only works a few hours a week.
Liability for Commercial Landlords
If your portfolio includes retail units or office spaces, your risk profile changes significantly. High footfall areas naturally increase the statistical likelihood of a claim. When you arrange Commercial Property Insurance, the liability element must account for the specific use of the building. Commercial leases also introduce the concept of “Contractual Liability.” This means you might be held responsible for certain risks based on the specific wording of your lease agreement with the tenant. Understanding these nuances is where landlord liability insurance explained by a human broker adds real value, as automated systems often miss the specific clauses that could leave a commercial landlord exposed.
Why Choosing a Specialist Broker Secures Better Property Protection
Choosing the right protection shouldn’t feel like a transaction with a machine. While automated comparison sites offer speed, they often lack the nuance required for complex property portfolios. Having landlord liability insurance explained by a human expert ensures that your specific risks, from the age of your building to the nature of your tenancies, are fully understood. As an independent broker with 30 years of industry experience, Just Quote Me provides access to a broad network of top UK insurers. We aren’t tied to a single brand, which allows us to find the most competitive pricing without compromising on the quality of your cover.
The value of a broker is most apparent when things go wrong. If a tenant or visitor makes a claim against you, you need a steady hand to manage the administrative burden. We act as your advocate, working directly with insurers to ensure fair settlements and clear communication. This human-centric approach transforms insurance from a grudging necessity into a genuine partnership. We handle the complex legal and administrative details so you can focus on managing your assets with confidence.
Local Expertise in Stone and Stafford
Regional knowledge is a significant marker of quality in the insurance market. Our deep roots in Staffordshire and the West Midlands mean we understand the local property landscape in areas like Newcastle-under-Lyme, Stone, and Stafford. Whether you’re letting out a Victorian terrace or a modern commercial unit, our regional expertise allows for more accurate risk assessments than a “one-size-fits-all” online form. We understand the specific challenges facing landlords in this part of the UK, providing tailored advice that generic national providers simply cannot match.
Consolidating Your Portfolio
If you manage multiple properties, administrative simplicity is vital. We can help you consolidate your entire portfolio under a single, simplified policy, reducing paperwork and ensuring there are no gaps in your protection. For those who manage properties for others, we also provide Professional Indemnity Insurance to protect against errors in professional advice or service delivery. This holistic view of your business ensures every angle is covered. To move beyond general information and get landlord liability insurance explained in the context of your specific properties, the next step is a direct consultation with our expert team.
Secure Your Property Portfolio for the Future
Protecting your rental assets in 2026 requires more than a basic buildings policy. We have explored how the legal landscape under the Occupiers’ Liability Act and the Defective Premises Act is increasingly complex; a single overlooked maintenance issue can result in life-altering legal expenses and compensation claims. Having landlord liability insurance explained by a specialist ensures you aren’t just buying a generic policy, but securing a robust legal defense tailored to your unique property risks.
Just Quote Me brings 30+ years of expert brokerage experience to your side, offering a human-centric alternative to impersonal automated systems. As an FCA authorised and regulated firm, we provide direct access to top-tier UK insurers, ensuring your cover is as reliable as it is competitive. You don’t have to navigate these administrative burdens or rising premiums alone. Just Quote Me to secure your tailored landlord insurance today and rest easy knowing your property portfolio is protected by local experts who understand the Staffordshire market. We are here to help you build a safer, more resilient future for your rental business.
Frequently Asked Questions
Is landlord liability insurance a legal requirement in the UK?
No, landlord liability insurance isn’t a legal requirement under UK law, but it’s a standard requirement for most buy-to-let mortgage agreements. Without this protection, you are personally responsible for any compensation claims or legal fees arising from injuries on your property. Given that 52% of landlords cite legislative changes as their biggest challenge in 2026, having this safety net is more critical than ever.
Does landlord liability cover my tenants’ personal belongings?
No, your policy does not cover the personal property of your tenants. Tenants are responsible for securing their own contents insurance to protect their furniture, electronics, and clothing. Your liability cover only triggers if your negligence, such as failing to repair a known structural defect, directly results in damage to their possessions or causes them physical harm.
How much does landlord liability insurance cost on average in 2026?
In 2026, the average cost for landlord insurance typically ranges between £200 and £750 per year. Basic buildings-only policies sit at the lower end, while comprehensive cover including high liability limits can exceed £600. Factors such as the property’s age, location, and whether you rent to students or professionals will significantly influence your final premium.
Can I get liability cover if I only own the leasehold of a property?
Yes, leaseholders definitely need their own liability protection. While the freeholder’s insurance usually covers the external structure and communal areas, you are responsible for everything inside your specific unit. If a visitor trips on a loose floorboard inside your flat, the claim will be directed at you rather than the freeholder.
What is the difference between public liability and property owners’ liability?
Property owners’ liability is a specialized subset of public liability designed specifically for the risks associated with owning land or buildings. While getting landlord liability insurance explained, it’s important to note that this cover focuses on hazards like falling masonry or faulty wiring, whereas general public liability usually covers broader business activities and off-site incidents.
Does my policy cover me if a tradesman is injured while working on the house?
Yes, your policy can cover you if a tradesman is injured due to a hazard you failed to manage, such as a broken step you didn’t warn them about. However, if the injury is caused by the tradesman’s own tools or poor working practices, their own business insurance should handle the claim. Always ensure any contractors you hire have their own valid public liability cover; for help finding reputable professionals, you can visit TradeLink-Hub to connect with verified service providers.
How much cover do I need if I have a large portfolio of properties?
For large portfolios in 2026, we generally recommend a minimum of £5,000,000 in cover. Rising litigation costs and claims inflation mean that lower limits may not provide a sufficient cushion for serious injury claims. If you manage multiple high-occupancy buildings or commercial units, higher indemnity limits are often a requirement for full financial security.
What happens if I don’t have liability insurance and a tenant sues me?
If you are uninsured and lose a negligence case, you must pay the compensation and all legal fees from your own pocket. This can result in costs totalling hundreds of thousands of pounds, often leading to the forced sale of property assets or personal bankruptcy. Having landlord liability insurance explained by a broker ensures you understand how to avoid these catastrophic financial risks.
Get Your Free Business Insurance Quote now
Request a Call back for free Expert advice
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Jul 29, 2026 | Insurance
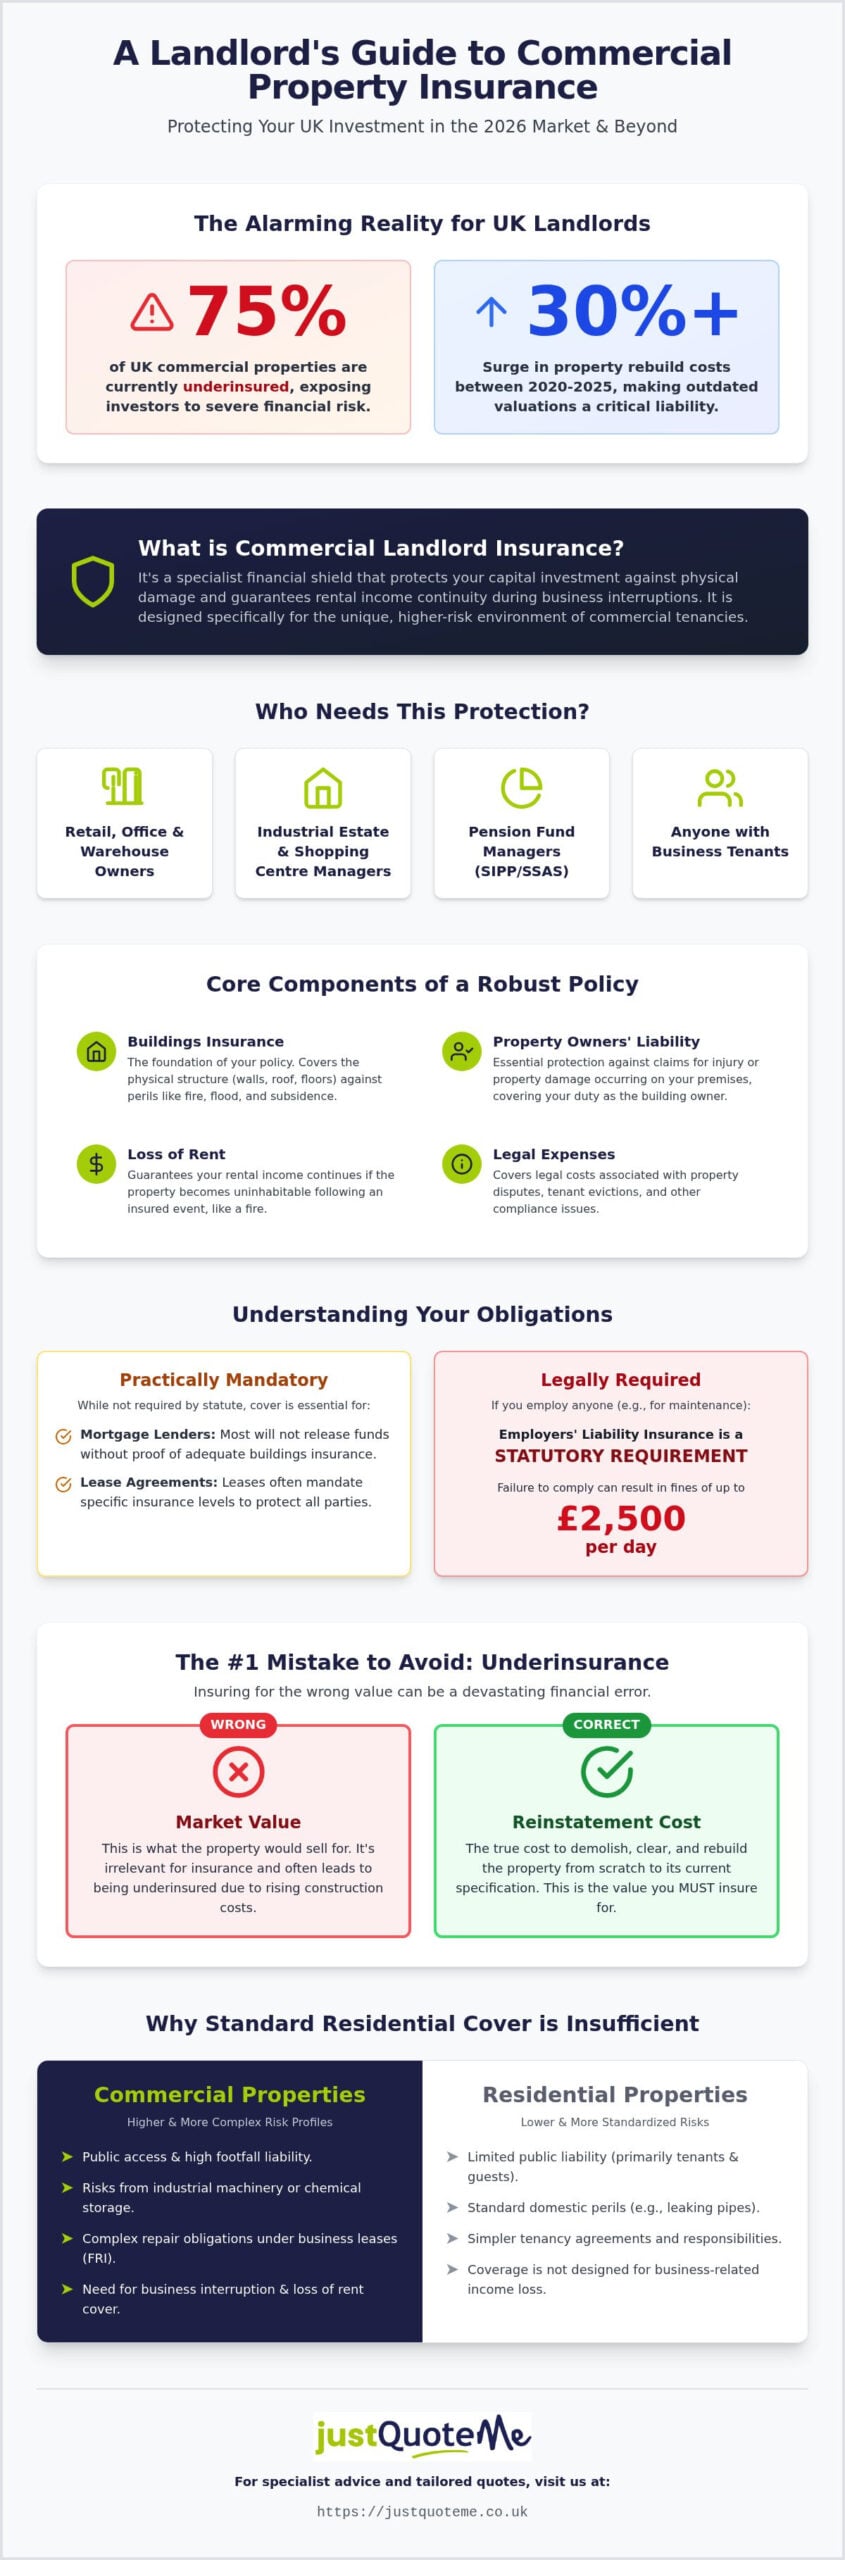
An estimated 75% of UK commercial properties are currently underinsured, leaving thousands of investors exposed to devastating financial gaps if a claim arises. With rebuild costs having surged by over 30% between 2020 and 2025, many landlords are unknowingly risking their entire portfolio on outdated valuations. Securing the right commercial landlord insurance uk is no longer just a box-ticking exercise for your mortgage lender; it’s a critical shield against the evolving risks of the 2026 property market.
We understand that the complexities of modern lease agreements and the recent Renters’ Rights Act can feel overwhelming. You want to ensure your income remains uninterrupted, even during tenant failures or long void periods, without getting lost in corporate jargon. This guide provides a straightforward roadmap to full legal compliance and asset protection. You’ll discover how to structure your coverage to mitigate tenant risks, satisfy strict lender requirements, and safeguard your yield against unforeseen accidents. Just Quote Me to simplify your administrative burden and gain the expert regional insight your investment deserves.
Key Takeaways
- Understand the essential core components of commercial landlord insurance uk, including protection for the building fabric and critical property owners’ liability.
- Learn how “Full Repairing and Insuring” (FRI) leases impact your legal obligations and how to align your policy with your tenant’s specific responsibilities.
- Discover why you must insure based on a professional reinstatement cost assessment rather than market value to avoid the financial penalties of underinsurance.
- Identify the unique risk profiles associated with different business sectors and why standard residential cover is insufficient for commercial tenancies.
- Find out how specialist brokers provide access to exclusive underwriters and bespoke coverage options for complex or multi-tenant property investments.
What is Commercial Landlord Insurance in the UK?
A commercial landlord policy is a specialist insurance framework designed for owners of buildings let for business purposes. It isn’t just a standard property policy; it’s a targeted solution that addresses the unique risks inherent in commercial tenancies. Commercial Landlord Insurance is a specialist financial framework that secures a property owner’s capital investment against physical damage while guaranteeing rental income continuity during periods of business interruption. While a residential landlord might worry about a leaking tap, a commercial landlord must consider the implications of industrial machinery, high-footfall retail spaces, or chemical storage on their premises.
Standard residential landlord insurance is insufficient for commercial tenancies because the risk profiles are fundamentally different. Residential insurers don’t account for the liability risks associated with public access or the complex repair obligations found in business leases. A key distinction exists between basic Property Owners’ insurance and comprehensive commercial landlord packages. While Property Owners’ cover primarily focuses on public liability, a full commercial package integrates buildings insurance, loss of rent, and legal expenses. These Core Components of a Commercial Landlord Policy follow the basic principles of indemnity, ensuring you’re returned to the same financial position after a loss as you were before it.
Who needs this type of cover?
Is it a legal requirement in the UK?
Commercial landlord insurance uk isn’t a statutory legal requirement like motor insurance, but it’s practically mandatory in the professional world. Most mortgage lenders won’t release funds without proof of adequate buildings insurance. Your lease agreement often mandates specific insurance levels to protect both parties’ interests. If you employ anyone to manage or maintain your properties, you’re legally required to have employers liability insurance. Failing to have this statutory cover can result in fines of up to £2,500 per day. Just Quote Me to ensure your policy meets every legal and contractual obligation without unnecessary complexity.
Core Components of a Commercial Landlord Policy
A robust policy for a business property isn’t a single product but a combination of specific protections tailored to your asset. When building your framework for commercial landlord insurance uk, you must prioritize the physical structure while accounting for the complex legal obligations that come with business tenancies. Understanding these Commercial vs. Residential Landlord Insurance: Key Differences is vital, especially since commercial tenants often make significant modifications to the premises. Buildings insurance serves as the foundation, protecting the fabric of the property against fire, flood, and subsidence. You must also clarify who is responsible for tenant improvements, such as bespoke shop fit-outs or specialized mezzanine floors, to avoid expensive gaps in coverage.
Rebuild costs in the UK increased by approximately 30-35% between 2020 and 2025. This inflation means that insuring for market value instead of actual reinstatement costs is a dangerous mistake. If you’re unsure which limit is right for your portfolio, you can speak with a specialist broker to review your current exposure and ensure your valuations are accurate for 2026.
Understanding Property Owners Liability
Property owners liability is a non-negotiable component that protects you against claims for injury or damage occurring on your premises. While it shares similarities with standard public liability insurance, it specifically covers your responsibilities as the building owner rather than the business operations of the tenant. This is critical for common areas like stairwells, car parks, and the external structural elements of the building. In 2026, standard indemnity limits for UK commercial landlords typically range from £2 million to £10 million, depending on the footfall and nature of the business occupying the space.
The ‘Loss of Rent’ safety net
Loss of rent cover is your primary cash flow protection. If a fire or major flood makes the property untenantable, your tenant will likely stop paying rent under a standard lease cessation clause. This cover replaces that lost income, helping you maintain mortgage payments and ongoing management costs during repairs. Choosing the right indemnity period is a strategic decision. While 12 months might seem sufficient, major rebuilds in the UK often face planning delays and material shortages. Opting for a 24 or 36-month period provides a more realistic safety net for significant structural restorations, ensuring your investment remains viable even during a total loss scenario.
Commercial vs. Residential Landlord Insurance: Key Differences
The risk profile of a business property is fundamentally different from a domestic home. While a residential claim might involve a burst pipe or minor kitchen fire, a commercial claim often involves high-footfall public access, industrial machinery, or hazardous materials. A restaurant, for instance, carries significantly higher fire and liability risks than a three-bedroom semi-detached house. This increased complexity is why a standard commercial landlord insurance uk policy is structured around the specific trade of the occupant rather than just the building’s size. If your tenant changes from a quiet accounting office to a high-heat catering business, your insurer must know immediately to ensure your protection remains valid.
Lease structures also create a major divide in how insurance is managed. In the commercial sector, the ‘Full Repairing and Insuring’ (FRI) lease is the industry standard. FRI leases shift the financial burden of the premium to the tenant, but the ultimate legal risk of underinsurance remains with the landlord. Under this arrangement, you as the landlord typically source and manage the policy to ensure your asset is fully protected, then recharge the premium cost to the tenant. When recharging these costs, you should consult official government guidance on insurance to ensure you’re following the latest transparency and fee regulations.
The FRI Lease: What landlords must know
In an FRI lease, the tenant is responsible for all repairs and the cost of insurance. However, you must maintain control over the policy selection. Relying on a tenant to insure your building is a dangerous gamble; if they let the policy lapse, your capital investment is completely exposed. You must also ensure the lease contains a robust ‘Loss of Rent’ clause. This allows you to recover lost income if the building becomes unusable. It’s vital to remember that a standard residential letting insurance policy won’t cover these commercial lease obligations and will likely be voided if used for a business unit.
Tenant activity and its impact on premiums
Every tenant trade carries a unique risk rating. High-risk activities, such as chemical storage or woodworking, will naturally drive up the premium for the entire building. You have a ‘Duty of Disclosure’ to inform your insurer about any change in your tenant’s business operations. Even if your tenant has their own shop insurance, that policy only covers their stock, contents, and specific business liabilities. It does not protect the building’s structure or your liability as the property owner. Mixed-use properties, such as high-street shops with residential flats above, require even more specialized handling to ensure both the commercial and residential elements are correctly rated within a single, cohesive policy.
How to Choose the Right Policy for Your Investment
Selecting the right commercial landlord insurance uk requires a systematic approach that looks beyond the annual premium. Start by conducting a full rebuild cost assessment. This figure represents the actual cost to reconstruct your building from the ground up and is entirely separate from its market value. Next, review every active lease agreement to identify specific insurance obligations. While you likely use an FRI lease, the exact wording regarding premium recovery and loss of rent indemnity must be mirrored in your policy. You should also analyze location-specific risks, such as flood history or local crime rates, and factor in the specific trade of your tenants. Finally, consult an independent broker who can access the whole of the market rather than relying on the limited options provided by automated quote engines.
A specialist broker understands that a warehouse in Staffordshire has different risk requirements than a retail unit in the West Midlands. You can speak with our team for a tailored portfolio review to ensure your coverage is as efficient as it is comprehensive.
Calculating the ‘Reinstatement Value’
Using the purchase price or current market value for your sum insured is a common path to underinsurance. The average underinsured commercial building in the UK is currently covered for only 67% of its actual rebuild cost. To avoid this, you should engage a RICS surveyor to provide a professional reinstatement valuation. This assessment must include the cost of modern construction materials, which were 2% higher in January 2026 than the previous year, as well as professional fees for architects and the substantial costs of debris removal after a total loss.
Evaluating ‘Unoccupied Property’ risks
Most standard policies include a 30-day rule, meaning coverage significantly reduces or ceases if a property remains empty for more than a month. If a tenant moves out, you must notify your insurer immediately to arrange specialist unoccupied property cover. This protects you against the increased risks of arson, vandalism, and squatting during void periods. For a deeper look at protecting your physical assets during transitions, see our dedicated guide to commercial property insurance. Just Quote Me to manage these complex transitions so your investment is never left vulnerable between tenancies.
Why Use a Specialist Broker for Commercial Landlord Cover?
Choosing a specialist broker for your commercial landlord insurance uk provides a layer of security that automated comparison sites simply cannot replicate. Algorithms often struggle with the nuances of business tenancies, leading to generic policies that may contain restrictive exclusions. By contrast, an independent broker offers direct access to ‘broker-only’ underwriters. These specialist insurers don’t deal with the general public and often provide more flexible terms and competitive pricing for complex or high-value assets. We manage the administrative heavy lifting, from conducting initial risk assessments to finalizing policy documents, ensuring your protection remains seamless as your portfolio grows.
Our role extends far beyond the initial transaction. When you face a claim, having a dedicated advisor who understands your property’s history is invaluable. We act as your advocate, managing communication with insurers and streamlining the settlement process to minimize your downtime. This regional expertise, particularly across Staffordshire and the West Midlands, allows us to provide pragmatic advice based on local market conditions and specific construction trends. Just Quote Me to simplify your management process and gain the peace of mind that comes from professional, human-led oversight.
Bespoke vs. Off-the-shelf policies
Generic policies often fail to account for the specific risks associated with certain commercial uses, such as high-heat catering or industrial manufacturing. If your building is listed or features non-standard construction, an off-the-shelf policy might leave you dangerously exposed. The Just Quote Me approach leverages over 30 years of experience to build bespoke frameworks. We ensure every endorsement is tailored to your specific building and tenant profile, eliminating the gaps that often plague standard insurance products.
Next Steps: Securing your quote
Securing a quote that actually protects your investment is a straightforward process. You’ll need to gather your latest rebuild values, tenant trade history, and the insurance clauses from your active lease agreements. Having this information ready allows us to move quickly and find the most efficient coverage for your needs. For complex portfolios or multi-use sites, a personalized consultation is often the most effective way to ensure every risk is addressed.
Future-Proofing Your Commercial Property Portfolio
Protecting a commercial asset in 2026 requires a proactive stance on risk management. We’ve detailed how aligning your policy with the specific trade of your tenants and the precise obligations of your lease prevents costly legal and financial gaps. By moving away from generic valuations and embracing professional reinstatement assessments, you safeguard not just the bricks and mortar, but the long-term viability of your rental income. A robust commercial landlord insurance uk framework is the foundation of a resilient investment strategy, allowing you to manage market fluctuations with confidence.
Just Quote Me acts as your strategic partner, bringing over 30 years of independent brokerage experience to your portfolio. We bridge the gap between complex underwriting requirements and your need for straightforward, efficient protection. Our FCA-authorised team provides the human-centric advice that automated systems lack, ensuring your assets are covered by top UK insurers under terms that make sense for your business. Take the next step in securing your property’s future with our direct support.
Frequently Asked Questions
Is commercial landlord insurance tax-deductible in the UK?
Yes, the premiums you pay for your commercial property are a fully allowable business expense. You can deduct the total cost of your policy from your rental income before calculating your final tax liability. This applies to buildings cover, property owners liability, and even the specialized legal expenses extensions required for commercial landlord insurance uk compliance.
What happens to my insurance if my commercial property becomes vacant?
Standard cover typically reduces to “Fire, Lightning, Explosion, and Aircraft” (FLEA) perils after a property has been empty for 30 consecutive days. You must notify your broker as soon as a tenant vacates to ensure you maintain adequate protection. We can often arrange extensions that cover a broader range of risks during these void periods, provided specific security measures are met.
Does the tenant’s insurance cover damage to my building?
No, a tenant’s policy only protects their own business assets, stock, and specific liabilities. They do not have an “insurable interest” in the building’s structure itself. As the landlord, you must maintain your own buildings insurance to protect your capital investment, regardless of what business insurance your tenant holds for their daily operations.
How is the rebuild cost different from the market value of the property?
Rebuild cost is the total price of labor, materials, and professional fees required to reconstruct the building from the foundations up. Market value includes the land value and the desirability of the location, which are irrelevant for insurance purposes. Insuring for market value is a common mistake that leads to significant underinsurance, especially in areas where property prices have stagnated but construction costs have risen.
Can I have one policy for a portfolio of commercial properties?
Yes, consolidating your assets into a single portfolio policy is an efficient way to manage multiple properties. This approach provides a common renewal date and often qualifies for bulk discounts from underwriters. Whether you own high-street shops or industrial units, we can build a cohesive commercial landlord insurance uk framework that covers every location under one administrative umbrella.
What is ‘Loss of Rent’ cover and is it essential?
Loss of rent cover replaces the income you lose if a major insured event, like a flood or fire, makes the property unusable. Since most commercial leases include a “rent cessation” clause that relieves the tenant of payment during repairs, this cover is essential for maintaining your cash flow. It ensures you can continue to meet mortgage payments and management fees while the building is being restored.
Do I need terrorism cover for my commercial property?
While not a statutory requirement, terrorism cover is a common mandate from commercial mortgage lenders. Standard property policies almost always exclude damage resulting from acts of terrorism, which could leave you with a total loss and a remaining mortgage debt. We can provide this as a specific extension to ensure your asset is fully protected against all potential threats.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Jul 28, 2026 | Insurance
The high yields of the student rental market are often wiped out by the “risk tax” hidden in generic insurance policies. You’re likely aware that securing the right landlord insurance for student lets often feels like a trade-off between profitability and the fear of a rejected claim. It’s a common frustration for property owners who manage Houses in Multiple Occupation (HMOs) and find themselves navigating a maze of regulations that automated quote engines simply aren’t built to handle.
We believe that managing a student property should be straightforward and secure. This 2026 guide shows you how to obtain bespoke coverage that protects against accidental damage while ensuring full compliance with the latest HMO licensing requirements. You’ll discover how the implementation of the Renters’ Rights Act 2025 affects your liability and how a specialist broker can source competitive pricing that reflects your actual risk. We’ll provide the expert clarity you need to move from uncertainty to a fully protected investment.
Key Takeaways
- Understand why standard buy-to-let policies often exclude student tenants and how to secure a specialist subset of cover designed for this market.
- Identify the essential buildings and contents protections needed to safeguard furnished properties against student-specific accidental damage.
- Learn how to maintain insurance validity by aligning your policy with mandatory HMO licensing and fire safety regulations.
- Discover the specific location and property age factors that influence the cost of landlord insurance for student lets in 2026.
- Recognize the value of human-centric brokerage expertise over automated algorithms when managing complex student property portfolios.
Student Let Landlord Insurance: What Makes It Different?
Student let insurance is a specialist subset of residential letting insurance designed to address the specific complexities of the university housing market. While standard buy-to-let policies are built for single families or professional couples, landlord insurance for student lets accounts for the higher footfall and administrative demands of shared households. It functions as a critical risk-mitigation tool specifically engineered for high-turnover rentals where multiple unrelated individuals live under one roof. Unlike a traditional tenancy, these arrangements often involve individual contracts for each room or a joint tenancy where the occupants change entirely every twelve months.
Standard buy-to-let policies often contain “no student” clauses by default. Insurers generally prefer stable, long-term tenants who they believe are more likely to treat the property as a permanent home. When you introduce three, four, or five students, the risk profile shifts. You aren’t just managing one tenancy; you’re managing a dynamic environment where occupants may be on individual or joint contracts. Without a policy that explicitly permits Student accommodation, a single accidental leak or minor fire could lead to a total claim rejection because the tenant type wasn’t disclosed at the start of the policy.
The Student Risk Factor: Why Insurers View Student Lets Differently
Insurers view students through a lens of increased risk, primarily due to a perceived lack of property maintenance experience and a higher probability of accidental damage. It’s not necessarily about malice. It is about the reality of several young adults living together for the first time. Shorter 12-month tenancies also contribute to this perception, as frequent move-ins and move-outs increase wear and tear on the building’s fabric. Additionally, communal areas like kitchens and living rooms see constant use, which heightens the risk of liability claims if an injury occurs in a shared space. These factors combined mean that a general landlord policy simply isn’t robust enough to cover the unique exposures of a student house.
Student Lets vs. Standard Buy-to-Let: Key Policy Differences
The key policy differences often hinge on the specific type of student you house. Undergraduates are typically seen as higher risk than postgraduates or mature students, and your premium may reflect this distinction. Another critical area is unoccupancy. Standard policies might only allow a property to be empty for 30 consecutive days. However, student properties often sit empty during the summer or Easter breaks. You need the necessity of residential letting insurance that explicitly permits students to ensure you remain covered even when the term ends and the students head home. Specialist landlord insurance for student lets provides extended unoccupancy periods, ensuring your investment stays protected during university holiday cycles.
Essential Coverage: Protecting Against Unique Student Rental Risks
A basic policy won’t suffice when housing multiple students. To protect your investment, you need a multi-layered approach that addresses both the physical structure and the financial risks of shared occupancy. Comprehensive landlord insurance for student lets should start with buildings insurance as the foundation, protecting against fire, flood, and subsidence. However, it must also account for the increased frequency of minor incidents, such as kitchen fires or water damage from communal bathrooms. These structural protections ensure that the core of your investment remains secure against the high footfall typical of university housing.
Contents insurance is equally vital. Most student properties are let fully furnished. You aren’t just insuring a sofa; you are protecting appliances, beds, and carpets across multiple rooms. To help maintain these assets and avoid unnecessary replacement costs, you can find out more about professional upholstery care. Without this specific inclusion, replacing high-use items after a single academic year can significantly erode your margins. Loss of rent cover provides an additional safety net. If a fire or major leak makes the property uninhabitable, this cover ensures your cash flow continues while repairs are underway. For landlords who rely on term-time income to cover mortgages, this protection is often the difference between a minor setback and a financial crisis.
Accidental vs. Malicious Damage: What You Need to Know
Distinguishing between accidental and malicious damage is a common point of confusion. Accidental damage cover is a non-negotiable extension for anyone seeking landlord insurance for student lets. It covers unintentional mishaps, like a spilled drink on a carpet or a cracked window. Malicious damage, however, involves intent. Most insurers exclude damage caused by the tenants themselves unless specifically added to the policy. To protect your position, you must document the property’s condition with a professional inventory at the start of every tenancy. This evidence is crucial if you need to support a claim or resolve a dispute regarding renting rights for students and deposit deductions.
Liability Protection for Shared Accommodation
Property Owners Liability is the most critical safeguard for landlords of shared houses. When three or more unrelated people share facilities, the risk of a slip, trip, or injury increases. If a tenant or their guest is injured due to a loose floorboard or faulty wiring, you could face a substantial legal claim. This protection covers both the compensation and your legal defense costs. You can learn more about how this works by reviewing our guide on Public Liability Insurance. Ensuring your policy includes high indemnity limits is essential for managing the unique risks of shared living environments. If you are unsure about your current liability levels, you can speak with a specialist broker to review your coverage.
HMO Compliance: Ensuring Your Insurance Remains Valid
Compliance isn’t just a box-ticking exercise for the local council; it’s the bedrock of your financial protection. If you file a claim for fire damage or a structural issue and can’t produce the required documentation, your insurer will likely refuse to pay. Failure to possess a valid HMO licence can void most UK landlord policies. This direct link between legal adherence and policy validity is why we emphasize paperwork as much as premiums. When you apply for landlord insurance for student lets, you’re essentially declaring that your property meets every legal standard required for shared occupancy.
Beyond the license itself, your insurer expects you to meet all landlord safety responsibilities as a condition of your cover. This includes maintaining up-to-date gas safety records and Electrical Installation Condition Reports (EICR). During a claim investigation, these certificates are often the first items an underwriter will request. If a fault in the electrical system causes a fire and your EICR is expired, you’re essentially self-insuring the damage. Keeping a digital vault of these documents ensures you’re always ready to prove your compliance if the worst happens.
Mandatory vs. Additional HMO Licensing Requirements
In 2026, any property housing five or more people from two or more separate households who share facilities requires a mandatory HMO license. However, local authorities in Stafford and across the West Midlands often implement selective licensing schemes that catch smaller properties with only three occupants. You must verify the specific requirements for your postcode, including mandatory bedroom sizes like 6.51m² for single occupants. Proving due diligence to an underwriter means showing you’ve checked these local rules and secured the necessary permissions before the first student moves in. This level of detail is exactly what we look for when placing your risk with a specialist insurer.
Fire Safety and Security Standards for Students
Fire safety is a primary concern for providers of landlord insurance for student lets. Missing smoke alarms or wedged-open fire doors are common reasons for claim rejection. Your property must have mains-wired smoke detectors, heat sensors in kitchens, and fire doors on all risk rooms. Security is equally important to maintain your residential letting insurance validity. Most specialist policies require 5-lever mortice deadlocks on external doors and key-operated locks on ground-floor windows. Implementing these robust measures doesn’t just keep your tenants safe; it projects an image of a managed, low-risk property that can help secure more favorable insurance terms.
Calculating the Cost: What Influences Student Rental Premiums in 2026?
Calculating the cost of landlord insurance for student lets in 2026 involves more than just a quick online form. Location is the most immediate factor. For landlords in Staffordshire and the West Midlands, proximity to major institutions like Keele or Staffordshire University creates high demand, but it also places properties in high-density areas. Insurers often categorize these postcodes as higher risk for theft or accidental damage. Regional crime statistics and local flood data are baked into your premium before you even provide specific property details.
The age of your building plays a significant role. Many student rentals are Victorian terraces, which are prized for their room sizes but carry higher insurance costs due to aging infrastructure and traditional construction methods. Insurers also weigh the number of tenants, known as the density of occupation. A house with six students has a higher fire and liability risk profile than one with three, simply due to the increased activity and shared use of facilities. Finally, your claims history remains a critical metric. A pattern of previous water damage or theft claims suggests a higher future risk, which can lead to loaded premiums or restrictive terms.
Strategies to Lower Your Student Insurance Costs
You can manage these costs through several proactive steps. Increasing your voluntary excess is a direct way to lower your annual premium, provided you have the cash reserves to cover it if a claim arises. Installing smart leak detectors and enhanced security systems also demonstrates a commitment to risk management that some underwriters reward with lower rates. For those managing several units, moving away from individual policies and securing a single commercial property insurance policy often provides better value and simplified administration. If you want to see how these factors apply to your specific portfolio, you can request a tailored quote to compare your options.
The Hidden Cost of Underinsurance
Accuracy is vital when setting your sums insured. With construction costs rising significantly by 2026, many landlords rely on outdated rebuild estimates. If you underinsure, you trigger the “Average Clause.” This legal principle allows an insurer to reduce your payout proportionally if the property is insured for less than its true rebuild value. For example, insuring a property for 75% of its value means you might only receive 75% of a claim payout, even for minor damage. Consulting a specialist broker ensures your figures are realistic for current market prices, protecting you from a catastrophic financial shortfall after a loss.
Securing Bespoke Cover with Just Quote Me
Finding reliable landlord insurance for student lets shouldn’t feel like a battle against an uncompromising computer algorithm. While automated quote engines often apply generic risk loadings to any property housing students, Just Quote Me offers a human-centric alternative that focuses on the specifics of your investment. With over 30 years of experience as an independent, Stafford-based broker, we understand that a well-managed HMO in the West Midlands is a different prospect than the high-risk labels software might apply. We leverage our local expertise and long-standing relationships with a broad network of UK insurers to find bespoke terms that align with your actual property management standards.
Our role is to manage the administrative burden so you don’t have to. We don’t just provide a price; we ensure the policy structure is robust enough to withstand the scrutiny of a claim. This involves accessing specialist insurer panels that aren’t available on standard comparison sites. These insurers understand the nuances of the student market and are willing to provide more flexible coverage for those who can demonstrate a commitment to safety and compliance. Just Quote Me to secure a steady hand in a complex market, ensuring your administrative requirements are met with precision and speed.
Our Approach to Student Landlord Insurance
We tailor every policy to include specific extensions that protect your cash flow and assets. This involves ensuring your unoccupancy clauses are realistic for university holiday cycles and that your accidental damage limits are sufficient for a furnished let. If your portfolio is large enough that you employ maintenance staff or cleaners, we provide expert advice on employers liability insurance to ensure you meet your legal obligations as an employer. Our regional knowledge of the Staffordshire rental market allows us to present your risk to underwriters in the most favourable light, often securing better rates than generalist providers.
Get Your Quote and Expert Advice
Starting your search is simple. We conduct a bespoke market search based on your property details, comparing options from across our network to find the most competitive fit for your landlord insurance for student lets. For landlords dealing with complex HMO licensing or multi-property portfolios, our callback service provides a direct line to a knowledgeable advisor. This ensures you aren’t just buying a policy, but securing a partnership with a broker who understands the complexities of the 2026 rental market. Provide your details today to see how a specialist approach can improve your coverage and your bottom line.
Get Your Free Business Insurance Quote now
Request a Call back for free Expert advice
Securing Your Student Rental Investment for 2026
Protecting a student property requires more than a standard policy. You need to ensure your coverage aligns perfectly with HMO licensing requirements and accounts for the high footfall of shared living. The key to success is moving beyond automated quotes and focusing on bespoke protection that covers accidental damage and liability risks. By prioritizing compliance and structural safety, you don’t just protect your building; you safeguard your long-term rental yields.
Just Quote Me is an FCA-authorised independent broker with over 30 years of industry experience. We provide the specialist knowledge of the UK student rental market needed to navigate complex regulations and find competitive terms. Don’t leave your investment to chance with generic algorithms. Our team is here to manage the paperwork and provide the steady hand you need in a changing market.
Take the next step toward secure property management:
Get Your Free Business Insurance Quote now
Request a Call back for free Expert advice
We look forward to helping you find the right landlord insurance for student lets to keep your business moving forward with confidence.
Frequently Asked Questions
Do I need a different type of insurance if I rent to students?
Yes, you must have a policy that explicitly permits student tenants to ensure your cover remains valid. Standard buy-to-let insurance often excludes students because shared households represent a different risk profile than single families. If you don’t disclose the tenant type correctly, you risk having your claims rejected. A specialist broker can help you navigate these distinctions to find a policy that recognizes the unique nature of student rentals.
Is accidental damage by student tenants covered as standard?
Accidental damage is rarely included as standard and usually requires a specific policy extension. You must check your policy schedule to confirm this cover is active, as it protects your investment from unintentional incidents like cracked tiles or stained carpets. Including this in your landlord insurance for student lets is a pragmatic way to manage the inevitable wear and tear associated with shared student living.
What happens to my insurance if my student property is empty over summer?
Most policies have unoccupancy limits, often 30 or 60 days, which can be exceeded during long university summer breaks. You must inform your broker if the property will be empty for extended periods. We can source specialist policies that offer extended unoccupancy terms, ensuring your building remains protected against fire, theft, and water damage while the students are away from the property.
Does my landlord insurance cover the students personal belongings?
No, your policy only covers the building and the contents you own, such as provided furniture and appliances. Students are responsible for insuring their own laptops, clothes, and gadgets through their own contents insurance. It’s good practice to advise your tenants of this at the start of the academic year to avoid confusion or financial loss for the students if a theft or fire occurs.
How does an HMO licence affect my student landlord insurance?
Your insurance validity is directly tied to your legal compliance with HMO licensing rules. If your property requires a licence and you don’t have one, your insurer will likely void your policy in the event of a claim. You must ensure your policy documents explicitly state that the property is an HMO and that you’re meeting all local authority safety standards to maintain your financial protection.
Can I get one policy for a portfolio of multiple student properties?
Yes, we can arrange a single portfolio policy that covers multiple student lets under one renewal date and one premium. This approach simplifies your administration and often provides better value than managing several individual policies. It also ensures consistent coverage levels across your entire investment portfolio, making it much easier to manage your annual insurance requirements and administrative burdens efficiently.
What security measures do insurers require for student lets?
Specialist insurers typically require 5-lever mortice deadlocks on all external doors and key-operated locks on accessible windows. These requirements are designed to mitigate the higher theft risk often associated with student-heavy areas. To ensure your hardware meets these specific insurance criteria, you can consult experts such as London Locks – Locksmiths Keys and Fobs. for professional advice and installation. You should also ensure that any communal entrances have robust self-closing mechanisms. Implementing these security standards is a straightforward way to protect your property and satisfy the mandatory conditions of your landlord insurance for student lets.
Will my insurance be void if I don’t have a gas safety certificate?
Yes, failing to maintain a valid gas safety certificate is a breach of your legal obligations and your insurance conditions. If a fire or explosion occurs and you can’t provide a current certificate, your claim will almost certainly be rejected. Your insurer expects you to follow all statutory safety requirements to ensure the property remains a safe environment for your tenants at all times.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Jul 27, 2026 | Insurance
Did you know that relying on a standard landlord policy for your multi-occupancy property could leave you facing a £30,000 fine and a completely voided claim? It’s a common trap for owners who assume all property cover is created equal. Securing reliable HMO landlord insurance online has become more challenging as regulations tighten and tenant types like students or those on DSS are often unfairly flagged as high risk.
We understand that the 2026 shift to rolling periodic tenancies and new EPC requirements adds layers of administrative stress you don’t need. You want comprehensive protection for your buildings and liability without the headache of complex licensing jargon. This guide helps you navigate these multi-occupancy complexities with an expert approach to finding the best cover available.
We’ll explore how to ensure your policy remains compliant with local authority rules while keeping your premiums competitive. Instead of wrestling with rigid forms, you can Just Quote Me to bypass automated algorithms and secure a bespoke policy that actually fits your portfolio’s specific needs.
Key Takeaways
- Understand why standard buy-to-let policies are inadequate for multi-occupancy properties and how specialist cover prevents voided claims and legal fines.
- Identify the essential core protections your investment needs, from structural buildings insurance to covering landlord-owned furniture in shared spaces.
- Learn how to navigate the challenges of securing HMO landlord insurance online when housing perceived high-risk tenant groups like students or DSS.
- Discover the critical fire safety and certification requirements you must meet to ensure your policy remains valid and your tenants stay safe.
- See how 30 years of brokerage experience can help you secure competitive, tailored pricing that standard automated underwriting systems often cannot offer.
What is HMO Landlord Insurance and Why is it Essential?
A property is legally classified as a House in Multiple Occupation (HMO) if it is let to three or more tenants from two or more households who share facilities like a kitchen or bathroom. Standard landlord insurance covers a single family or a couple; it doesn’t account for the unique risks of multiple unrelated adults living under one roof. If you try to secure HMO landlord insurance online through a standard portal, you might find that your property doesn’t fit their rigid criteria. This mismatch often leads to landlords purchasing the wrong cover, which can have devastating financial consequences.
Most buy-to-let mortgage lenders insist on specialized buildings cover as a condition of the loan. If you have an HMO mortgage but only hold standard residential letting insurance, you’re likely breaching your mortgage terms. This breach could lead to the lender calling in the loan or refusing to provide further financing. Beyond the bank, the financial risks include personal liability for accidents in communal areas, which a standard policy will almost certainly exclude.
HMO vs. Standard Buy-to-Let: Key Differences
The household rule is the biggest differentiator. A household usually consists of members of the same family living together. When you mix different households, the risk profile changes significantly. Higher footfall leads to more rapid wear and tear on the structure. Shared kitchens increase the statistical chance of accidental fires, and communal living areas can lead to higher liability claims. Insurers view these properties as higher risk because there’s less shared responsibility for communal areas compared to a single-family home. This is why a standard policy often becomes void the moment three unrelated people move in.
Large HMOs and Mandatory Licensing
Properties with five or more tenants from two or more households are considered Large HMOs. These require a mandatory license from the local authority. Operating without one can lead to fines starting from £30,000. Insurers will check for this license during a claim; if it’s missing, they won’t pay out. Some councils also use Article 4 directions to limit HMO density, which can affect property value and insurance availability. Finding HMO landlord insurance online for these larger risks requires a broker who understands local licensing nuances. For example, licensing fees in areas like Tower Hamlets can reach over £1,300, and insurers expect your management standards to reflect that level of professional oversight.
Core Coverage: Protecting Your Multi-Occupancy Investment in 2026
Protecting a multi-occupancy asset in 2026 requires more than a generic policy. It demands a suite of covers designed for the unique pressures of shared living. While buildings insurance remains the foundation, protecting against fire, flood, and subsidence, the scope of your policy must reflect the higher density of tenants. According to official UK government guidance, landlords are strictly responsible for repairs to communal areas and the structure itself. Failing to maintain these standards can lead to significant liability claims if a tenant is injured. With all rental properties expected to require an EPC rating of at least ‘C’ by 2026, your buildings cover should also account for the increased value of energy-efficient upgrades.
HMOs are frequently let as furnished or part-furnished properties. This makes contents insurance essential for protecting landlord-owned appliances, sofas, and dining sets in shared spaces. When searching for HMO landlord insurance online, ensure your policy includes loss of rent cover. If a fire in a communal kitchen renders the property uninhabitable, you lose multiple income streams simultaneously. This protection ensures your mortgage payments and overheads are covered while repairs are underway, preventing a single incident from causing a total financial collapse.
Specialist Liability Protection for HMOs
Property owners’ liability is perhaps the most critical component for multi-let landlords. In 2026, the industry standard has shifted toward £2m or £5m in cover to account for rising legal costs and compensation awards. Shared kitchens and bathrooms are high-risk zones where slips, trips, or burns are statistically more likely. If you’re unsure about the level of protection required for your specific tenant profile, you can learn more about Public Liability requirements to ensure your portfolio is fully defended against injury claims.
Optional Extras for Enhanced Security
High-turnover tenancies naturally lead to more wear and tear. Adding accidental damage cover protects your investment from the inevitable spills or breakages that occur in busy households. With the 2026 abolition of ‘no-fault’ evictions and the move to rolling periodic tenancies, legal expenses cover has become a vital safeguard. This helps manage the costs of regaining possession through specific legal grounds like rent arrears or anti-social behavior. Emergency assistance is another sensible addition; it provides fast access to contractors for urgent plumbing or heating failures, keeping your tenants happy and your property compliant with basic habitability standards. If you need to refine your current protection, you can compare specialized landlord solutions to find the right balance of cost and cover.
The Online Quote Challenge: Finding HMO Cover When Others Say No
Automated quote systems are built for simplicity. They prefer semi-detached houses with a single family and standard brick construction. When you try to secure HMO landlord insurance online for a property housing six students or asylum seekers, those same systems often return a “decline” or an inflated premium. This happens because algorithms can’t quantify the nuances of professional property management. They see a flat roof or a timber frame and apply a blanket rejection because their risk appetite is too narrow to accommodate anything non-standard.
Accurate disclosure is paramount in 2026. If you fail to mention a specific tenant type or a structural feature like a flat roof, you risk a total claim rejection later. Insurers are particularly sensitive to fire risks in multi-occupancy settings. Following a formal Fire safety risk assessment isn’t just a legal duty; it’s a piece of information that can turn a “decline” into an “accept” when presented correctly. Brokers understand how to frame these safety measures to underwriters, proving that your property is a managed risk rather than a liability.
The Broker Advantage vs. Aggregators
Just Quote Me operates differently than generic comparison sites. We have access to broker-only panels that don’t appear on standard search engines. These underwriters specialize in complex risks and value the human element of property management. You’re talking to a person who understands that a student let in a university town is a managed risk, not a disaster waiting to happen. Our 30 years of experience allows us to negotiate rates that automated bots simply can’t reach. For a deeper look at the changing market, see our Landlord Insurance in 2026: The Ultimate UK Guide.
Insuring Mixed-Use and Multi-Property Portfolios
Managing multiple HMOs across different postcodes creates a significant administrative burden. We can consolidate these into a single policy, often at a more competitive rate than individual covers. This fleet-style approach is also effective for mixed-use buildings. If your HMO sits above a shop or restaurant, you’ll need Commercial Property Insurance for mixed portfolios to ensure both the residential and commercial elements are protected. This ensures your entire investment is shielded by a single, steady hand, simplifying your renewals and claims processes.
Compliance and Risk Management: Preparing for Your Quote
Insurers don’t just want your premium; they want proof of safety. Maintaining current Gas Safety records and Electrical Installation Condition Reports (EICR) is non-negotiable for any multi-occupancy property. If a fire starts in a communal kitchen, the first thing an underwriter will ask for is your fire safety log. This includes evidence of regular alarm testing, serviced extinguishers, and correctly fitted fire doors. When you apply for HMO landlord insurance online, being able to demonstrate this proactive approach immediately positions you as a lower-risk client. It proves you’re managing the property professionally rather than just collecting rent.
HMO Licensing and Local Authority Standards
Staffordshire and West Midlands local authorities have some of the most stringent licensing requirements in the UK. Operating without a valid license is a criminal offense that carries fines starting from £30,000. It also renders your insurance policy void. We understand the regional nuances here, especially with the 2026 Decent Homes Standard updates approaching. These updates require HMOs to meet even higher benchmarks for thermal comfort and structural safety. Staying ahead of these local council rules ensures your property remains insurable and your liability is minimized.
Tenant Vetting and Management
Tenant vetting is a critical pillar of risk management. Professional referencing doesn’t just protect your rent; it’s often a policy condition for certain tenant types. Mismanaging shared spaces is a frequent cause of liability claims. Keeping communal hallways clear of obstructions and ensuring shared facilities are inspected monthly reduces the chance of a slip or trip. For those transitioning from single-family lets, our Residential Letting Insurance guide explains how these management duties differ from standard rentals.
Finding the right HMO landlord insurance online is significantly easier when you have a clear history of compliance. Documented monthly inspections and a clear maintenance schedule prove to insurers that you are an active manager. If you’ve updated your fire doors or improved your EPC rating to a ‘C’ ahead of the 2026 deadline, you should secure your compliant HMO quote now to ensure these improvements are reflected in your premium.
Securing Bespoke HMO Landlord Insurance Online with Just Quote Me
Finding reliable HMO landlord insurance online shouldn’t feel like a gamble with your property’s future. While many providers rely on rigid, automated underwriting that rejects anything slightly complex, Just Quote Me takes a different approach. We’ve spent over 30 years refining a process that combines the speed of a digital inquiry with the precision of human expertise. This ensures your multi-occupancy investment is protected by a policy that actually reflects its specific risk profile rather than a generic template.
Our process is designed for efficiency. It begins with a straightforward online form where you provide the essential details of your property and tenant mix. Instead of an algorithm making a final, potentially incorrect decision, one of our expert brokers reviews your information. We look for the nuances that automated systems miss, such as your professional management standards or specific safety upgrades. This human-centric approach is often the most cost-effective way to insure an HMO in 2026, as it allows us to negotiate directly with our panel of top UK underwriters to find a price that matches the actual risk.
Independent advice is vital in a market where regulations like the Renters’ Rights Act and changing licensing fees are constantly shifting the landscape. Settling for a generic policy might save a few pounds on the initial premium, but it often leaves you exposed to massive financial gaps during a claim. By choosing a specialist broker, you gain a partner who manages the administrative burden and ensures your cover remains compliant with both your mortgage lender and local authority requirements.
Personalised Service for Staffordshire Landlords
We take particular pride in our regional expertise. For landlords operating in Stone, Stafford, and Newcastle-under-Lyme, we offer a level of local knowledge that national aggregators simply can’t match. We understand the West Midlands rental market, from student housing demands to the specific licensing nuances of local councils. This regional focus allows us to provide more accurate advice and tailored solutions for your portfolio. For a comprehensive look at how we support local businesses, read our Commercial Insurance Broker Staffordshire Guide.
Get Started with Your HMO Quote Today
Securing the right protection is a straightforward process. Gather your property details, including your HMO license number, rebuild value, and current tenant types. Having your latest fire safety and EICR dates to hand will also help us provide the most accurate HMO landlord insurance online quote possible. Don’t leave your investment to chance with a standard policy that isn’t fit for purpose.
Protect Your Property Portfolio for the Future
Managing a multi-occupancy property in 2026 requires a proactive approach to risk and a deep understanding of local licensing. Specialist HMO cover is non-negotiable; standard buy-to-let policies simply don’t offer the structural or liability protections needed for shared households. By prioritizing compliance with fire safety standards and ensuring your licensing is up to date, you don’t just stay legal; you become a more attractive risk to top-tier underwriters.
Finding the right HMO landlord insurance online is about more than just clicking a button on a comparison site. It requires the steady hand of a partner who understands the nuances of mixed-tenant profiles and regional requirements. Just Quote Me provides this expert UK-based support, leveraging 30 years of experience as an independent, FCA Authorised & Regulated broker. We navigate the complexities so you can focus on growing your investment.
Don’t leave your assets exposed to generic underwriting that doesn’t account for your professional management standards. You can secure tailored HMO protection today and gain the peace of mind that comes with bespoke coverage. Your portfolio deserves a policy that works as hard as you do.
Frequently Asked Questions
Is HMO landlord insurance a legal requirement in the UK?
Specialist HMO insurance isn’t a legal requirement for private landlords, but it’s almost always a mandatory condition of your buy-to-let mortgage. Standard landlord policies don’t cover the risks associated with multiple unrelated tenants. If you fail to have the correct cover in place, you could be in breach of your loan agreement and find that any claim you make is rejected, leaving you personally liable for damages.
Can I get HMO insurance online for a property with more than 5 tenants?
You can certainly search for HMO landlord insurance online for larger properties, but automated systems often struggle with the increased risk profile of five or more tenants. These properties require mandatory licensing and stricter fire safety measures. A broker can help you navigate these requirements, ensuring that your larger investment is correctly underwritten by a specialist panel that understands high-occupancy risks.
Does HMO insurance cover student tenants or those on benefits?
Yes, specialist policies can cover students, professionals, and those receiving benefits, although some standard insurers may exclude these groups. We work with a panel of underwriters who understand these specific tenant profiles and can provide robust protection. It’s important to be transparent about your tenant mix from the start to ensure your policy remains valid and provides the correct level of liability cover.
What happens if I don’t have an HMO license but apply for insurance?
Applying for insurance without a required HMO license is extremely risky and will likely void your policy. Insurers require you to follow all local authority regulations as a condition of your cover. If you need to make a claim and cannot produce a valid license, the insurer can refuse to pay out. Additionally, you could face fines starting from £30,000 from your local council for unlicensed operation.
How much does HMO landlord insurance cost on average in 2026?
Premiums for HMO cover in 2026 are generally higher than standard buy-to-let policies because of the increased liability and structural risks. Factors such as your property’s location, the number of tenants, and their occupation type will influence the final figure. Seeking HMO landlord insurance online through a broker is the most effective way to compare rates from different underwriters and secure a price that reflects your specific management standards.
Does my HMO policy include public liability insurance as standard?
Most specialist HMO policies include property owners’ liability as a core component, though the level of cover can vary between £2 million and £5 million. This protection is vital in multi-occupancy settings where shared kitchens and bathrooms increase the statistical likelihood of accidents. You should always check your policy schedule to ensure the liability limit meets your specific needs and any requirements set by your mortgage lender.
Can I insure multiple HMO properties under one policy?
Yes, you can consolidate several multi-occupancy properties into a single portfolio policy. This approach simplifies your administration by giving you one renewal date and often results in a more competitive premium than insuring each property individually. It’s an efficient solution for landlords with growing portfolios across the West Midlands who want a clear, manageable overview of their total insurance coverage.
What is the difference between an HMO and a multi-unit block?
The primary difference lies in the shared facilities. An HMO involves three or more tenants from different households sharing a kitchen, bathroom, or toilet within one dwelling. In contrast, a multi-unit block consists of several entirely self-contained flats within a single building. Each flat has its own private facilities, which changes the risk profile and the type of property insurance required for the building.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Jul 26, 2026 | Insurance
What if the short gap between tenancies is the exact moment your insurance protection disappears? Most landlords assume their existing cover remains active during a void period, but many are shocked to find that standard policies often restrict or cancel protection after just 30 or 60 days of vacancy. It’s a stressful situation; you’re already managing the loss of rental income without the added anxiety of a burst pipe or vandalism occurring while the building is unattended. Securing specialist landlord insurance for unoccupied property is the only way to ensure your investment doesn’t become a financial liability during these transitions.
We understand that navigating the fine print of unoccupancy limits can feel like a minefield of potential loopholes. You need a policy that doesn’t just tick a box but actually provides robust security that satisfies your mortgage lender’s strict requirements. In this article, we’ll explain why specialist vacant property cover is essential and how to avoid the common pitfalls that lead to rejected claims. You’ll discover how to maintain full protection throughout every void period with expert advice designed to simplify your administrative burden. Just Quote Me to secure the professional, tailored protection your portfolio requires.
Key Takeaways
- Understand the strict unoccupancy clauses in standard policies that can leave your investment unprotected after just 30 days of vacancy.
- Identify the essential components of specialist cover, including structural protection and property owner’s liability for accidents on empty sites.
- Learn how to comply with mandatory inspection warranties and security standards to ensure your insurer honors any potential claims.
- Explore flexible term options for landlord insurance for unoccupied property to ensure you only pay for the specific duration your building is vacant.
- Discover why a bespoke risk assessment from an independent broker offers more security than a one-size-fits-all automated quote.
What is Landlord Insurance for Unoccupied Property?
Specialist landlord insurance for unoccupied property provides a vital safety net for buildings that sit empty for extended periods. While standard Property insurance models assume a tenant is present to monitor the premises, this specialist cover steps in when a home is left empty for more than 30 or 60 consecutive days. It’s a dedicated solution for those transitional moments in a property’s lifecycle, such as when a landlord is awaiting probate, undergoing major renovations, or experiencing an unexpectedly long void period between tenancies. Without this specific protection, you risk a total loss of cover during the times your investment is most vulnerable.
There is a technical distinction between ‘unoccupied’ and ‘vacant’ that often trips up property owners. An unoccupied property is typically one that is ready for habitation and contains enough furniture for someone to live there, even if no one is currently resident. A vacant property is often completely stripped of contents and utilities. Insurers view these risks differently; a vacant building is often seen as a higher risk for squatters or arson. Securing the correct landlord insurance for unoccupied property ensures the integrity of your investment remains intact regardless of how much furniture is inside.
The 30-Day and 60-Day Unoccupancy Rule
Most standard rental policies include an unoccupancy clause that limits coverage once a property has been empty for a set number of days. This is usually 30 or 60 days. It’s a common mistake to think that visiting the property once a week to collect post or check the taps resets this clock. Insurers define “consecutive” strictly. If a new tenancy hasn’t legally commenced, the clock keeps ticking. This rule frequently catches out landlords during summer breaks in student housing or when a chain collapses during a sale. You must notify your provider the moment you realize a void period will exceed these standard limits.
Why Standard Policies Don’t Cut It
When a property is empty, the risk profile changes dramatically. A small leak from a burst pipe can go undetected for weeks, causing thousands of pounds in structural damage. Standard policies often react to this increased risk by dropping to ‘FLEA’ cover; which stands for Fire, Lightning, Explosion, and Aircraft. This means you lose protection against theft, vandalism, and water damage exactly when you need it most. Transitioning to a policy that includes residential letting insurance features tailored for empty buildings ensures you aren’t left with a massive bill because of a technical loophole. It’s about maintaining a continuous shield of protection that adapts as your property status changes.
What Does Specialist Unoccupied Property Cover Include?
Specialist landlord insurance for unoccupied property acts as a comprehensive shield against the unique threats that target empty buildings. While fire, storm, and flood damage remain standard inclusions for the structure, the level of protection is significantly deeper than a basic policy. It’s designed to account for the lack of daily oversight, ensuring that if disaster strikes while no one is watching, the financial burden doesn’t fall solely on your shoulders. This specialist cover fills the gaps that standard policies intentionally leave open when a tenant moves out.
Malicious damage and vandalism are high-priority risks for vacant sites. Whether it’s graffiti, smashed windows, or attempted break-ins, these incidents can quickly devalue your investment and delay your ability to re-let the property. Perhaps the most critical inclusion is coverage for “Escape of Water.” A burst pipe in an empty home often leads to the costliest claims because the damage continues for days or even weeks before discovery. Specialist policies ensure you’re protected against these undetected disasters, providing peace of mind during the quietest periods of your property management cycle.
Liability Protection for Empty Properties
Even if your property is empty, you still owe a legal duty of care to anyone who enters the premises. This includes invited contractors, delivery drivers, or even uninvited trespassers. If someone is injured due to a loose floorboard, a faulty gate, or a trip hazard, you could face significant legal action and compensation claims. Property Owner’s Liability is a safeguard against third-party injury claims in 2026, providing the essential legal and financial backing required to defend your assets. Many landlords choose to integrate this with broader public liability insurance to ensure their entire portfolio is protected from every angle.
Renovations and Building Works
If you’re using a void period to update the property, you must disclose the nature of the work to your insurer. There’s a major difference between cosmetic redecoration, like painting or installing new carpets, and structural renovation, such as knocking down walls or extending the footprint. Structural changes often void standard unoccupied cover because they introduce new risks like collapse or fire from “hot works.” In these cases, you might need contractors all risk insurance to cover the works in progress. Failing to declare these works is a common “duty of disclosure” error that leads to rejected claims. If you aren’t sure which category your project falls into, it’s best to speak with a professional broker who can calibrate your policy to your specific needs.
Managing the Risks of a Void Period
Securing landlord insurance for unoccupied property is only the first step in protecting your investment. To ensure your policy remains valid, you must actively manage the physical risks associated with an empty building. Insurers view vacant properties as high-risk assets, so they attach specific conditions to the cover. Failing to meet these requirements can lead to a total rejection of your claim if an incident occurs. Managing a void period effectively means transforming the property from a target into a secure, monitored environment.
Utility management is a frequent point of contention during claims. Most specialist providers require you to turn off the water at the stopcock and drain the system entirely unless you are maintaining a specific temperature. If you choose to keep the heating on to prevent damp, you must typically keep the thermostat set between 12 and 15 degrees Celsius around the clock. Additionally, you should ensure all external doors are fitted with five-lever mortice deadlocks and that all accessible windows have key-operated locks. Simple deterrents, such as removing piles of post from the hallway and keeping the garden tidy, prevent the property from looking abandoned to potential burglars or squatters.
The Importance of Regular Inspections
The “Property Inspection Warranty” is a standard feature of landlord insurance for unoccupied property. This clause typically mandates that the landlord or a designated representative must visit the premises at least once every seven to fourteen days. During these visits, you should check for damp patches, slipped roof tiles, and any signs of attempted forced entry. Crucially, you must maintain a written log of these inspections. This log should include the date, time, and name of the person who visited, along with a brief note on the property’s condition. If you cannot prove these inspections took place, your insurer may refuse to pay out for damage that occurred between visits.
Seasonal Precautions for Landlords
Each season brings unique challenges for empty properties. In winter, the primary threat is frozen pipes that burst and flood the building. Beyond thermostat settings, you should ensure that pipes in unheated areas like lofts are properly lagged. Summer risks are often more social than environmental; overgrown lawns and weed-choked driveways are clear signals to squaters that a property is unattended. If you are employing tradesmen to board up windows or install temporary security measures, it’s vital to verify their credentials. In cases where significant security upgrades or repairs are being made, you might also need to consider builders insurance to cover the specific risks associated with on-site work and contractor activity.
Calculating the Cost of Unoccupied Landlord Insurance
Pricing for landlord insurance for unoccupied property isn’t a one-size-fits-all calculation. Insurers evaluate the specific risks of the void period, which often results in premiums that are higher than standard tenanted policies. However, specialist cover offers a level of flexibility that annual policies lack. You can often secure terms for 3, 6, or 9 months, ensuring you only pay for the exact duration the building stands empty. This is particularly efficient for landlords managing a property through probate or a defined renovation schedule, as it avoids the wasted expense of a full twelve-month commitment.
Accuracy in your property valuation is paramount to avoid the trap of under-insurance. You must base your cover on the rebuild cost of the structure rather than its current market value. If your rebuild valuation is inaccurate, insurers may apply the “Condition of Average” during a claim, which reduces your payout proportionally to the level of under-insurance. For example, if you’re only insured for 70% of the actual rebuild cost, you might only receive 70% of any claim value, even for minor incidents. Working with a broker allows you to access niche insurers who don’t appear on standard comparison sites, providing more precise pricing based on your specific asset.
Location remains one of the most significant variables in your premium calculation. Properties in Stafford, Newcastle-under-Lyme, or the wider West Midlands are assessed based on hyper-local crime statistics and environmental factors like flood risks. An automated system might treat an entire postcode with a broad brush, but a human broker can highlight the specific security measures you’ve taken to mitigate local risks. Just Quote Me to leverage our 30 years of regional expertise and find a policy that reflects the reality of your property’s location.
Factors Influencing Your Premium
Modern security enhancements can actively lower your insurance costs. Installing monitored CCTV or smart locks provides underwriters with the reassurance that the property isn’t a “soft target.” The reason for the unoccupancy also dictates the rate; a property sitting empty during a straightforward sale is viewed as a lower risk than one undergoing a high-intensity structural overhaul. Regional crime data in the West Midlands continues to fluctuate in 2026, directly impacting the base rate for empty home premiums across the county.
Avoiding the ‘Cheap Quote’ Trap
It’s tempting to opt for the lowest possible price, but this often leads to ‘FLEA’ only cover, which excludes theft, vandalism, and water damage. A slightly higher premium for ‘All Risks’ protection is a far safer investment for an unattended building where a small leak could spiral into a major structural failure. You should also evaluate the policy excess carefully; a lower monthly payment might be offset by a prohibitively high excess that makes small claims unviable. To find a policy that offers genuine value without hidden gaps, request a call back for free expert advice.
Why Use an Independent Broker for Unoccupied Cover?
Choosing the right landlord insurance for unoccupied property requires more than just an algorithm; it demands a human-centric approach to risk. While automated comparison sites are designed for high-volume, standard risks, they often struggle with the nuances of vacant buildings. A human broker understands the specific context of your investment, such as whether a property in Stone is empty due to probate or if a site in Staffordshire is undergoing a phased renovation. This bespoke risk assessment ensures that your policy reflects the reality of the situation rather than a generic postcode average.
Our access to the whole market allows us to look beyond the “big name” insurers that dominate television advertising. These large providers often have rigid criteria that lead to higher premiums or outright rejections for unoccupied risks. Instead, we tap into a network of specialist underwriters who understand the complexities of empty properties. For landlords managing diverse assets, this might involve integrating your cover with commercial property insurance to ensure there are no gaps in your mixed portfolio protection.
Perhaps the most significant advantage of working with an independent broker is claims advocacy. If you discover a leak or a break-in, you won’t be left navigating a complex automated phone system alone. Just Quote Me acts as your partner throughout the entire process, leveraging 30 years of industry experience to ensure your claim is handled fairly and efficiently. We use our authority to negotiate with insurers on your behalf, providing a steady hand during what is often a stressful period for any property owner.
The Just Quote Me Difference
We pride ourselves on a pragmatic and straightforward approach to insurance. Being an FCA-authorised firm serves as your badge of trust, confirming that we operate with the highest standards of reliability and transparency. We don’t believe in one-size-fits-all solutions; instead, we focus on providing the specific advice you need to protect your capital. Our regional expertise in the West Midlands allows us to offer insights that national competitors simply cannot match. This personal touch is what differentiates a dedicated partner from a faceless automated system.
Get Protected Today
Securing the correct unoccupancy cover provides the peace of mind you need to focus on your next tenant or renovation project. Don’t leave your investment to chance with a standard policy that might fail when you need it most. Take a proactive step toward full protection with expert guidance that simplifies the administrative burden of property management. We’re here to ensure your assets remain secure, regardless of how long they stay empty.
Secure Your Property Portfolio for Every Transition
Protecting a vacant building requires a move beyond standard rental policies that often expire after 30 or 60 days. You’ve learned that managing risks through documented inspections and meeting strict security standards is essential for maintaining valid cover. Securing specialist landlord insurance for unoccupied property ensures your investment remains protected against the costliest threats, such as escape of water and vandalism, even when no tenants are present. It’s about maintaining a continuous shield that adapts to your property’s status.
As an FCA Authorised and Regulated broker with over 30 years of independent experience, we provide more than just a policy. We offer access to a broad network of top UK insurers and the bespoke advocacy you need if a claim arises. Our pragmatic approach simplifies the complex administrative burden so you can focus on your next tenancy with confidence. Just Quote Me to find a solution tailored to your specific needs. Your investment is in safe hands, allowing you to manage your portfolio with absolute peace of mind.
Get Your Free Business Insurance Quote now
Request a Call back for free Expert advice
Frequently Asked Questions
How long can a rental property be empty before I need specialist insurance?
Most standard rental policies allow for a vacancy period of 30 or 60 consecutive days before cover is restricted or cancelled. Once you exceed this specific window, you must switch to specialist landlord insurance for unoccupied property to maintain full protection against risks like theft or water damage. It’s vital to check your policy wording immediately, as some providers have even shorter limits for certain high-risk perils.
Is unoccupied property insurance more expensive than standard landlord insurance?
Premiums for empty buildings are generally higher because insurers view them as a greater risk for undetected leaks, vandalism, and arson. Without a tenant present to monitor the premises, a small issue like a dripping pipe can quickly become a catastrophic structural claim. However, you can often manage these costs by choosing a flexible, short-term policy that only covers the exact duration of the vacancy rather than a full year.
Do I need to tell my mortgage lender if my property is empty?
You must inform your mortgage lender if the property will be vacant for an extended period to avoid breaching your loan agreement. Most lenders require the building to be fully insured at all times, and a standard policy that has lapsed due to an unoccupancy clause could put your mortgage at risk. Providing proof of a specialist unoccupied policy ensures you remain compliant while protecting the lender’s financial interest in the asset.
Can I get insurance for a property undergoing major renovations?
Specialist cover is available for properties undergoing renovations, provided you disclose the full scope of the work to your broker before projects begin. While cosmetic updates are usually acceptable, structural changes or “hot works” require specific underwriting to account for the increased risk of fire or collapse. In some cases, you may need to combine your landlord insurance for unoccupied property with additional contractors’ protection to ensure the project is fully covered.
What is FLEA cover and why should I avoid it for empty properties?
FLEA cover is a restricted form of insurance that only protects against Fire, Lightning, Explosion, and Aircraft damage. Standard insurers often drop to this minimal level of protection once a property has been empty for over 30 days, leaving you completely vulnerable to theft, vandalism, and burst pipes. Avoiding this trap is essential, as the excluded risks are the most common causes of financial loss for vacant residential buildings.
Does unoccupied property insurance cover squatters?
Many specialist policies include legal expenses cover to help you regain possession if squatters occupy the building. While the insurance itself won’t prevent unauthorized entry, it provides the necessary financial backing for legal proceedings and can cover the cost of repairing malicious damage caused during the occupation. You should verify that “legal expenses for eviction” is explicitly included in your policy schedule to ensure you have this support if needed.
How often do I need to visit my empty property for the insurance to be valid?
Most insurers mandate a physical inspection of the premises every 7 or 14 days as a condition of the policy warranty. You must perform a thorough internal check and keep a detailed written log of every visit, including the date, time, and any actions taken to secure the site. Failing to maintain this log or missing a scheduled inspection can lead to a total claim rejection if an incident occurs between your visits.
Can I buy a short-term 3-month policy for an empty house?
Flexible short-term policies for 3, 6, or 9 months are widely available through specialist brokers and are ideal for temporary void periods. These options are perfect for landlords who only need cover during a sale, a probate period, or a quick refurbishment project before new tenants move in. Choosing a pro-rata term ensures you don’t pay for a twelve-month contract when you only need a few weeks of specialized protection.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Jul 25, 2026 | Insurance
Did you know that 26% of UK holidaymakers with health histories admit to withholding details from their insurers to avoid high costs? While it’s tempting to skip the fine print, an undisclosed diagnosis can turn a dream holiday into a financial nightmare if a claim is rejected. Finding reliable travel insurance for pre existing medical conditions shouldn’t feel like a choice between going unprotected or paying an extortionate premium. You’re likely frustrated by automated forms that don’t understand your specific situation or reject you for minor, well-managed health issues.
We’re here to change that by simplifying the medical screening process. This guide explains how to secure comprehensive protection, including vital emergency medical repatriation, without overpaying for specialist cover. We’ll also break down the latest 2026 FCA regulations, such as the new £200 premium trigger for medical signposting, so you know exactly where you stand. You’ll gain a clear understanding of what counts as a pre-existing condition and how to ensure your policy is ironclad before you head to the airport. It’s time to replace confusion with the confidence that you’re fully covered.
Key Takeaways
- Understand why standard policies often exclude known health issues and how a tailored policy ensures you aren’t left footing a massive medical bill.
- Navigate the medical screening process with ease by learning how to answer simple declaration questions accurately to protect your future claims.
- Identify the three main pillars—age, destination, and condition severity—that determine your premium costs, especially for high-cost regions like the USA or Spain.
- Learn why booking your travel insurance for pre existing medical conditions immediately after your holiday is confirmed is the best way to secure vital cancellation cover.
- Discover the advantage of using an independent broker who shops the specialist market to find you comprehensive cover while managing the administrative burden on your behalf.
What is Travel Insurance for Pre-Existing Medical Conditions?
When you plan a trip, you expect your policy to be a safety net. However, many travellers discover too late that standard policies are designed only for the “unforeseen.” If you have an ongoing health issue, a standard policy might exclude it entirely. This is where travel insurance for pre existing medical conditions becomes essential. It is a tailored form of coverage that explicitly includes health issues you already have, ensuring that if you need treatment related to that condition while abroad, you aren’t left with a massive bill. To understand the broader context of these policies, it’s helpful to first ask What is Travel Insurance? and how it functions as a risk management tool.
As of 2026, the industry threshold for what counts as “pre-existing” usually covers any condition you’ve been diagnosed with, treated for, or prescribed medication for within the last 24 months. This includes everything from high blood pressure and diabetes to more complex histories like cancer or heart disease. While this sounds restrictive, having a medical history doesn’t make you uninsurable in the UK. The market for specialist travel insurance is robust, and most travellers can find comprehensive cover if they know where to look and how to declare their health accurately.
The Difference Between Standard and Specialist Cover
Standard policies are built for healthy travellers and focus on accidents or sudden illnesses. They often have strict medical exclusions that leave you vulnerable. Specialist policies are different. They are specifically designed for chronic illnesses, terminal diagnoses, and post-surgery recovery. Choosing a “cheap” standard policy when you have a health history is often the most expensive mistake you can make. If you fall ill due to an undeclared condition, the insurer can void the entire policy, leaving you to pay for hospital stays and emergency flights out of your own pocket.
Why Medical Disclosure is a Legal Necessity
In the UK, the Insurance Act mandates a duty of fair presentation. You must provide an honest and complete picture of your health. Non-disclosure, even if accidental, can lead to total claim rejection and policy cancellation. In the context of UK travel insurance, a material fact is any piece of information regarding your health history that would influence an insurer’s decision to offer cover or determine the premium rate. Being transparent during the application ensures your peace of mind and the validity of your protection.
Understanding the Medical Screening Process in 2026
The screening process is the engine behind every specialist policy. It isn’t a hurdle designed to catch you out; it’s a data-gathering exercise that allows brokers to quantify your personal health risks accurately. When applying for travel insurance for pre existing medical conditions, you’ll find the process has become significantly more streamlined in 2026. Most UK insurers use an intelligent “Medical Declaration” system. This consists of a series of direct “Yes/No” questions about your diagnoses and recent hospitalisations. Understanding the Medical Screening Process helps you realise that this transparency is what keeps your cover valid and ensures claims aren’t rejected later.
Preparation is the key to a stress-free screening. Before you start, you’ll need a comprehensive list of your current medications and the dates of any surgeries. Accuracy here is vital. The answers you provide generate a “medical risk rating.” This rating doesn’t just look at your condition in isolation. It considers how that health history might interact with your destination’s climate or local healthcare costs. If the process feels overwhelming, it’s often better to speak with a specialist broker who can guide you through the nuances of the questionnaire.
Common Conditions That Require Specialist Declaration
Insurers focus on conditions most likely to require emergency care abroad. Cardiovascular issues, such as high blood pressure, heart disease, or a history of strokes, are always high on the list. Respiratory conditions also require careful declaration; this includes asthma if it’s ever led to a hospital stay, and Chronic Obstructive Pulmonary Disease (COPD). Chronic illnesses like Type 1 or Type 2 diabetes, Crohn’s disease, and any history of cancer must be declared to ensure you’re fully protected.
The Role of the UK Global Health Insurance Card (GHIC)
The GHIC remains a valuable tool in 2026, but it’s never a substitute for a private policy. It provides access to state-provided healthcare in EU countries at the same cost as a local resident. However, it has major gaps. Most notably, the GHIC doesn’t cover emergency medical repatriation. If you need a private medical flight back to the UK, costs can reach tens of thousands of pounds. Private insurance covers these catastrophic expenses while the GHIC only manages basic bedside care.
Calculating the Cost: Why Premiums Vary for Medical Travel
Understanding the pricing of travel insurance for pre existing medical conditions requires looking at three core pillars: your age, your destination, and the severity of your health history. Statistics from 2026 show that age remains a primary driver for premiums. For instance, the average single-trip policy for a healthy traveller aged 26 to 34 costs approximately £13, while the same cover for someone aged 81 or over rises to around £64. When you add a medical condition to the mix, insurers must balance these age-related risks with the likelihood of your condition requiring treatment while you’re away.
Your choice of policy type also influences the final price. A single-trip policy might have a median price of £27, whereas an annual multi-trip policy often sits around £71. For travellers with chronic conditions, an annual policy can offer better value if you plan multiple breaks, but insurers may apply more stringent criteria for year-long cover. Trip duration is another factor. Longer stays increase the statistical window for a medical emergency, which is why a three-week holiday costs significantly more to insure than a short weekend break.
The Hidden Costs of Non-Specialist Insurance
Opting for the cheapest available cover often leads to high out-of-pocket expenses. In 2024, medical claims accounted for 34% of all travel insurance payouts, with an average settlement of £1,528. However, serious emergencies far exceed this average. An air ambulance repatriation from the USA can easily cost over £80,000, a debt that could fall on your family if your policy is voided due to non-disclosure. A specialist travel insurance policy acts as a financial firewall, protecting you from inheriting life-altering medical debt.
Destination Risk: Where Medical Costs Soar
- North America: The USA and Canada have the highest healthcare inflation rates globally. For those planning extended stays or relocating, securing cheap car insurance Canada is another essential step in managing your international expenses. Without a bespoke policy, a simple hospital observation stay can cost thousands.
- Spain: Despite being close to home, Spain often carries higher premiums for UK residents because tourists are frequently directed to expensive private hospitals rather than state facilities.
- Reciprocal Agreements: While the UK has agreements with some nations, these rarely cover the full scope of treatment or any form of repatriation.
As an independent broker, Just Quote Me assesses these regional risks by shopping a broad network of top UK insurers. We understand that a traveller heading to France with high blood pressure faces different risks than one heading to the Caribbean. By evaluating the specific healthcare landscape of your destination, we help you find cover that is comprehensive without being unnecessarily expensive. We manage the complex administrative side so you can focus on your trip.
Actionable Tips for Finding Affordable Medical Travel Cover
Securing affordable travel insurance for pre existing medical conditions requires strategy rather than just clicking the first result on a comparison site. One of the most effective ways to protect your investment is through “Early Booking.” You should buy your policy the moment you confirm your trip. This ensures you’re covered for cancellation if your health takes an unexpected turn before you even leave the UK. Since 34% of all claims in 2024 were for medical expenses, having cancellation cover in place early is a vital financial safeguard.
You should also evaluate whether you need a “Full Comprehensive” policy or a “Medical-Only” policy. If your primary concern is health and you already have baggage cover through a premium bank account, a medical-only policy might be more cost-effective. Another common mistake is the “Family Policy” trap. Automated comparison sites often apply the highest risk rating to every person on a group quote. In many cases, it’s cheaper to insure the person with the health condition on a specialist solo policy while the rest of the family uses a standard product. To find the best balance for your specific needs, you can get a personalized quote from our experts who understand these market nuances.
Managing Your Excess to Lower Premiums
Increasing your voluntary excess is a direct way to reduce your upfront premium. This is the amount you agree to pay toward a claim yourself. It’s a useful tool for lowering costs, but you must ensure the excess remains affordable. If you have a terminal condition, you might look for “Excess Waiver” options. These plans often have a higher initial cost but remove the financial burden of the excess if you need to make a claim during a difficult time.
Reviewing Your Cover Annually
If you hold an annual multi-trip policy, you must update your broker on any health changes as they happen. Don’t wait for the renewal date. A key factor in pricing is the “Stability Period.” Many insurers offer lower rates if your condition has been stable with no changes in medication for at least 12 months. Keeping your Travel Insurance records accurate ensures your protection remains valid. Using an FCA-authorised broker allows you to navigate these niche rules with human guidance rather than relying on a rigid algorithm.
The Just Quote Me Advantage: Bespoke Medical Insurance
Securing the right policy shouldn’t be a battle against a rigid computer program. At Just Quote Me, we’ve spent 30 years refining a human-centric approach to the insurance market. As an independent, FCA-authorised broker, our loyalty lies with you rather than a single insurance provider. This independence allows us to shop a broad network of top UK insurers to find the most competitive travel insurance for pre existing medical conditions. We understand that your health history is personal, and we treat it with the professional restraint and precision it deserves. Instead of navigating complex administrative hurdles alone, you can rely on our Stone-based specialists to manage the details on your behalf.
The process is designed for maximum efficiency. From your initial inquiry, we move quickly to assess your specific needs through a guided conversation rather than a cold, automated form. This assessment allows us to identify the nuances of your condition and match them with an underwriter who understands that specific risk. Once we’ve compared the market, we present you with a bespoke policy that provides genuine protection. This steady hand in a complex market ensures that you aren’t just buying a piece of paper, but a reliable safety net for your next journey.
Why Stafford and Stone Residents Trust Just Quote Me
Our local high-street presence in Staffordshire is a marker of our commitment to individualized service. We combine this regional expertise with national access to provide a level of care that larger, impersonal competitors simply can’t match. We specialize in “hard-to-place” risks, including those that automated comparison sites often decline due to complex medical histories or terminal diagnoses. This reputation for reliability is why many local clients also trust us to manage their Business Insurance and other professional risks. We bridge the gap between niche medical requirements and comprehensive legal protections.
Securing Your Peace of Mind for 2026
Before you head to the airport, run through a final checklist to ensure your trip is stress-free. Always keep a digital and physical copy of your policy documents and ensure your emergency assistance numbers are readily available. Most importantly, verify that your disclosure confirmation exactly matches your current health status. If anything has changed since you took out the policy, contact us immediately to update your cover. The Just Quote Me promise is simple: we provide expert advice and pragmatic solutions so you can travel with confidence. It’s time to stop worrying about the “what-ifs” and start looking forward to your holiday.
Get Your Free Business Insurance Quote now
Request a Call back for free Expert advice
Secure Your Next Journey With Confidence
Finding the right protection for your health history shouldn’t be a source of stress. By declaring your conditions accurately and understanding the medical screening process, you ensure that your policy remains a valid safety net rather than a source of potential claim rejection. It’s about securing the freedom to explore without the fear of financial medical debt if the unexpected happens. Just Quote Me is an FCA Authorised and Regulated firm with 30+ years of brokerage experience, offering independent advice from top UK underwriters to help you secure comprehensive travel insurance for pre existing medical conditions.
We manage the administrative weight and complex market comparisons so you can focus on your destination. Whether you’re heading to Europe or North America, our Stone-based team provides the steady hand needed to navigate niche medical requirements. We are committed to straightforward, honest communication that puts your security first, ensuring you leave the UK with the highest level of protection.
Get Your Free Business Insurance Quote now
Request a Call back for free Expert advice
Frequently Asked Questions
Do I need to declare a medical condition if I am no longer taking medication for it?
Yes, you must declare any condition that falls within the standard 24-month look-back period required by most UK insurers. Even if your daily treatment has ceased, a previous diagnosis or a recent hospital consultation remains a material fact that affects your risk profile. Failing to disclose these details could invalidate your cover. Insurers need this information to assess the likelihood of the condition recurring while you’re abroad.
Can I get travel insurance if I am currently on a waiting list for surgery?
You can still obtain cover while on a waiting list, but most policies will exclude claims related to that specific condition or the upcoming procedure. Standard providers often decline these applications because the risk of a pre-departure complication is too high. Working with a specialist broker is the most effective way to find a policy that covers your general health while clearly outlining the exclusions for your pending surgery.
Will my travel insurance be valid if I travel against my doctor’s advice?
Your insurance will be invalid if you travel against a medical professional’s formal advice. Insurers base their risk assessment on the assumption that you’re medically fit to travel at the time of departure. If a doctor has advised against your trip, any subsequent claim, medical or otherwise, is likely to be rejected. Always secure a “fit to travel” confirmation if you’ve recently been unwell or had surgery.
What happens if I am diagnosed with a new condition after I have bought my policy?
You must notify your insurer as soon as you receive a new diagnosis, even if your policy is already paid in full. The insurer will re-evaluate your medical risk rating and may require an additional premium to maintain your cover. If you don’t disclose the change, you risk having future claims rejected. This is because your medical declaration must reflect your health status at the moment you depart, not just when you purchased the plan.
Does travel insurance for pre-existing conditions cover COVID-19 related issues in 2026?
Most travel insurance for pre existing medical conditions in 2026 includes cover for COVID-19 as a standard medical emergency. This typically covers hospitalisation costs and emergency repatriation if you fall ill while abroad. However, you should check the specific terms regarding cancellation or trip disruption, as these vary between underwriters. Ensure your policy explicitly mentions pandemic cover to avoid any ambiguity during a claim.
Why is travel insurance so much more expensive for the USA if I have a heart condition?
The USA has the highest private healthcare costs globally, and heart conditions carry a significant risk of requiring intensive care or emergency surgery. These treatments in American hospitals can cost hundreds of thousands of pounds. Insurers set premiums that reflect the potential for these catastrophic payouts, which are far higher than equivalent treatments in Europe. This destination risk is a major factor in your final quote.
Can I get a policy if I have been given a terminal diagnosis?
You can secure travel insurance for pre existing medical conditions even with a terminal diagnosis. Specialist underwriters focus on providing cover for travellers who have received a life-limiting prognosis, provided they’re currently fit to travel. These policies ensure you have access to palliative care or repatriation if needed. They require a more detailed medical screening to tailor the protection accurately to your specific situation and destination.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Jul 24, 2026 | Insurance
If you import goods from overseas to sell online, you aren’t just a distributor in the eyes of the law; you are the manufacturer. This legal shift means that if a faulty product causes harm, the responsibility rests squarely on your shoulders, not a factory located thousands of miles away. It’s natural to feel overwhelmed by the complex insurance mandates from platforms like Amazon and Walmart, especially when your personal assets are at risk. Finding the right product liability insurance for e-commerce seller needs shouldn’t feel like a legal maze.
Master the complexities of product liability and secure the right protection for your online business with our expert buying guide. We understand that you need to meet strict platform requirements, such as Amazon’s $1 million coverage threshold, while managing the unique risks of global sourcing. This guide explores the essential coverage types for 2026, explains why importers face heightened liability, and provides a clear path to securing a bespoke policy that fits your specific business model. By the end, you’ll have the confidence to grow your brand knowing your assets are fully protected.
Key Takeaways
- Understand why product liability is essential for protecting your personal assets against claims of injury or property damage caused by the items you sell.
- Learn why importing goods from outside the UK places the same legal responsibilities on your business as a manufacturer under the Consumer Protection Act.
- Navigate the 2026 insurance mandates for major marketplaces, including the specific sales thresholds that trigger compulsory coverage for Amazon Pro Merchants.
- Discover how to calculate the correct indemnity limit for your product liability insurance for e-commerce seller requirements, ranging from £1 million to £5 million.
- Find out how a bespoke approach from a specialist broker simplifies the administrative burden while ensuring your policy meets specific platform standards.
What is Product Liability Insurance for E-commerce Sellers?
In the UK, product liability is the area of law that dictates who is responsible when a consumer is harmed by a defective item. For an online business, product liability insurance for e-commerce seller protection acts as a shield against claims involving personal injury or property damage. If a product you sold causes a house fire due to a faulty battery or leads to a severe allergic reaction because of a missing label, you are the one the legal system looks to for compensation. This insurance covers the legal costs of defending your business and the eventual settlement if you’re found liable.
The 2026 e-commerce landscape is more complex than ever. With global supply chains becoming the norm, the distance between the factory and the final customer has grown, but the legal responsibility has stayed local. Common claims often involve items you might consider low risk. For instance, a simple phone charger that overheats and causes a fire, a toy with a small part that becomes a choking hazard, or a dietary supplement that causes an undisclosed adverse reaction can all lead to six-figure lawsuits. Without a robust policy, these claims can easily bankrupt a growing online store.
The Difference Between Public and Product Liability
It’s easy to confuse these two types of cover, but they serve very different purposes. Public Liability Insurance generally protects you against claims of injury or damage that happen in connection with your business activities or on your premises. If a delivery driver trips over a box in your home office, that’s a public liability issue. However, once a product is sold and leaves your possession, it falls under product liability. This “after-sale” protection is the most critical element for e-commerce sellers because your primary risk isn’t who visits your office; it’s the thousands of items you’ve sent out into the world. Most specialist e-commerce policies bundle these together to ensure there are no gaps in your protection.
Is Product Liability Insurance a Legal Requirement?
Unlike Employers Liability Insurance, which is a statutory requirement if you have staff, product liability isn’t strictly required by UK law. However, it’s effectively mandatory for most professional sellers due to contractual obligations. Major platforms have strict rules. For example, Amazon requires sellers to provide proof of insurance within 30 days of hitting $10,000 in monthly gross proceeds. Walmart Marketplace sets its threshold at $100,000 in annual sales. Even if you don’t use these platforms, the financial risk of going uninsured is immense. In a litigious market, a single faulty batch of products could result in multiple claims that target your personal assets if your business isn’t properly protected.
The Importer Trap: Why Your Business Model Dictates Your Risk
Many online entrepreneurs believe they are shielded from lawsuits because they don’t physically manufacture the products they sell. This is a dangerous misconception. Under the Consumer Protection Act 1987, if you import goods from outside the United Kingdom, you are legally treated as the manufacturer. This means that in a courtroom, you hold the same level of responsibility as the factory that actually produced the item. While seeking common kinds of business insurance is a standard step for any startup, e-commerce sellers must look deeper into how their sourcing affects their legal standing.
The legal principle of “Strict Liability” is at the heart of this risk. Unlike other areas of law where a claimant must prove you were negligent, strict liability only requires the claimant to prove that the product was defective and that it caused them harm. They don’t need to show that you knew about the defect or that you failed to check the item. If you brought the product into the UK market, the buck stops with you. Identifying who is the “Producer” versus the “Seller” is a critical step in setting up your business correctly. Getting a policy that reflects your actual business model is vital; you can consult with our team to ensure your coverage matches your supply chain reality.
Insurance for Dropshippers
Dropshipping is often marketed as a low-risk business model, but from a liability perspective, it carries significant weight. Even if you never touch the product or store it in a warehouse, you remain the “contractual seller” in the eyes of the consumer. If an item dropshipped from an overseas supplier causes an injury, the customer will sue the person they paid: you. Finding specific product liability insurance for e-commerce seller needs is essential for dropshippers to ensure their policy explicitly covers items dispatched directly from third-party suppliers.
White-Labeling and Re-branding Risks
Placing your own logo on a generic product is a popular way to build a brand, but it also shifts 100% of the liability to your business. By “holding yourself out” as the manufacturer through branding, you waive the ability to pass the blame to the original factory. You must verify that your suppliers hold valid testing certifications, such as UKCA or CE marks, to ensure the products meet safety standards. Under the Consumer Protection Act, re-branders face strict liability for any defects because the law views the brand owner as the primary producer of the goods. This makes having the right product liability insurance for e-commerce seller protection a non-negotiable part of your brand-building strategy.
- Supply Chain Transparency: Always document your original sources and keep copies of safety certificates.
- Contractual Indemnity: Where possible, ensure your supplier contracts include clauses that protect you, though these are often difficult to enforce with overseas factories.
- Batch Tracking: Maintain records of batch numbers to limit the scope of a potential recall.
Major e-commerce platforms operate as marketplaces, not manufacturers. To protect their own interests, they increasingly shift the burden of liability onto the individual seller. While these platforms provide the digital storefront, they don’t provide a safety net for your personal assets. Obtaining e-commerce business insurance has transitioned from a recommendation to a strict requirement for high-volume sellers. If you fail to provide a valid Certificate of Insurance (COI) when prompted, platforms can and will freeze your disbursements or suspend your account entirely.
Amazon remains the most rigorous in its enforcement. As of July 2026, Amazon requires Pro Merchants to carry product liability insurance once they reach $10,000 in monthly gross proceeds. Once you hit this threshold, you have exactly 30 days to upload proof of coverage. The policy must provide at least $1 million in coverage per occurrence and in the aggregate. Providing the correct product liability insurance for e-commerce seller documentation is a precise task; the COI must explicitly name “Amazon.com Services LLC and its affiliates and assignees” as an additional insured to be accepted by their verification teams.
Amazon Insurance Accelerator and External Policies
Amazon offers an “Insurance Accelerator” to help sellers find coverage, but these off-the-shelf options aren’t always the most cost-effective or comprehensive for UK-based businesses. An independent broker can often secure a bespoke policy that offers better value while ensuring you meet the “Additional Insured” clause requirements. A critical factor for UK sellers is geographic reach. If you sell to customers in the USA or Canada, your policy must specifically include North American coverage. Many standard UK policies exclude these regions due to their high litigation costs, so you must verify this detail to remain compliant with Amazon’s global terms.
Etsy and eBay: Liability for Handmade and Vintage Goods
As of July 2026, platforms like Etsy, eBay, and Shopify do not have a formal insurance mandate for their sellers. However, the lack of a requirement doesn’t mean you lack risk. Handmade sellers face unique dangers regarding material toxicity, small-part durability, and flammable fabrics. If you sell vintage goods, the risk is even more complex because the original manufacturer may no longer exist, leaving you as the sole target for legal action. You shouldn’t rely on a standard home insurance policy. Most domestic providers exclude business activities and product-related claims, meaning a single lawsuit could leave you personally liable for damages. Secure a professional policy to ensure your business remains resilient as these platforms evolve their seller protection policies.
- Submission Tip: Ensure the name on your insurance policy matches your legal entity name on the platform exactly.
- Threshold Monitoring: Don’t wait until you hit the $10,000 mark to start shopping; the 30-day window for Amazon compliance is tight.
- Coverage Limits: While $1 million is the Amazon minimum, high-risk categories like electronics or toys often require higher indemnity levels.
Buying Guide: How to Choose the Right Level of Cover
Choosing the right level of product liability insurance for e-commerce seller needs involves more than just meeting platform minimums. While Amazon might only require a £1 million limit, your actual exposure could be much higher. Common indemnity limits are £1 million, £2 million, or £5 million. If you sell high-volume items or products with the potential for serious injury, opting for a higher limit is a pragmatic decision. You should also consider “Product Recall” cover as an optional extra. This helps manage the significant logistical and financial costs of pulling a dangerous batch of items from the market.
Several factors influence your premium. Your annual turnover is a primary indicator of risk volume. The destination of your sales also matters; selling to the US or Canada typically increases costs due to higher legal fees. Finally, the nature of the product itself is the biggest driver. Understanding the difference between “Claims-Made” and “Claims-Occurring” policies is vital. A “Claims-Occurring” policy covers you for incidents that happen during the policy period, regardless of when the claim is filed. Conversely, a “Claims-Made” policy only covers claims filed while the policy is active. Given that product issues can take years to surface, this distinction is critical for long-term security.
Assessing Your Product Risk Profile
Essential Policy Add-ons for E-commerce
In 2026, a digital storefront is as vulnerable as a physical one. Integrating Cyber Insurance protects you against data breaches and the financial fallout of website downtime. You should also consider Stock and Goods in Transit cover to protect your inventory from the moment it leaves the supplier until it reaches the customer. Business Interruption cover is another essential consideration. It provides a financial cushion if your supply chain is disrupted, such as a major fire at your primary manufacturer’s facility. To find a policy that balances cost with comprehensive protection for your product liability insurance for e-commerce seller requirements, you can get a tailored quote from our expert team today.
Securing Your E-commerce Future with Just Quote Me
Choosing the right product liability insurance for e-commerce seller needs shouldn’t be left to a generic algorithm. While comparison sites offer speed, they often lack the depth required to understand a complex online business model. A bot won’t ask about your specific sourcing in East Asia or the nuances of your white-labeling agreements. Just Quote Me provides a human-centric alternative, where 30 years of industry experience acts as your primary safeguard against administrative errors and coverage gaps. We pride ourselves on being a steady hand in a complex market, managing the heavy lifting so you don’t have to.
Our team takes a pragmatic approach to your protection. We understand that as your turnover grows, your risk profile shifts. We don’t just provide a policy; we build a partnership that evolves alongside your storefront. For sellers based in Staffordshire and the West Midlands, we offer the accessibility of a local service provider backed by the authority of an established independent broker. This regional expertise ensures we understand the specific challenges facing UK businesses in a global marketplace. It’s about more than just a certificate; it’s about having an advisor who knows your sector inside out.
Bespoke Solutions vs. Off-the-Shelf Policies
The danger of “automatic” quotes is that they often leave significant gaps in your coverage. Generic options might satisfy a platform’s basic checklist but fail when a real claim arises. We negotiate directly with a broad network of top UK insurers on your behalf. This allows us to secure terms that reflect your actual operational risks rather than a generalized industry average. Read more about our approach to Business Insurance to see how we tailor our services to different professional sectors.
Get Started with Expert Advice
Our process is designed for efficiency and clarity. From your initial enquiry to securing full cover, we manage the administrative burden so you can focus on scaling your brand. Our 30 years of experience means we’ve seen every type of claim, from minor property damage to complex international litigation. Just Quote Me and secure your business with the confidence that only expert advice can provide. We make the transition from inquiry to action seamless and logical.
Protect Your Assets and Scale with Confidence
As the e-commerce landscape evolves in 2026, the legal burden on sellers has never been higher. Whether you are navigating the importer trap under the Consumer Protection Act or meeting the strict $10,000 monthly threshold for Amazon, the right coverage is your business’s most vital asset. Relying on automated quotes can leave your personal assets exposed to long-tail risks that only a human expert can identify. Securing the correct product liability insurance for e-commerce seller needs ensures that a single faulty batch won’t derail years of hard work.
Just Quote Me brings over 30 years of brokerage experience to the table. As an FCA-authorised and independent firm, we focus on providing straightforward, reliable advice that simplifies the complex administrative burdens of online retail. Don’t leave your future to chance when you can access tailored protection designed specifically for your niche. Your growth deserves a partner who understands the nuances of the digital market. We are here to help you build a resilient e-commerce brand today. Visit Just Quote Me to see how we can support your journey.
Get Your Free Business Insurance Quote now
Request a Call back for free Expert advice
Frequently Asked Questions
Do I need product liability insurance if I sell through Amazon FBA?
Yes, you definitely need it. Amazon FBA is a fulfillment service that handles storage and shipping, but it doesn’t assume your legal liability for the products themselves. Once your monthly gross proceeds reach $10,000, Amazon requires proof of a valid policy. Failing to provide this within 30 days can lead to account suspension or held disbursements.
What happens if a customer is injured by a product I imported from China?
Under UK law, you are legally treated as the manufacturer if you import goods from outside the United Kingdom. If a customer is injured, they’ll file a claim against your business rather than the overseas factory. This makes having robust product liability insurance for e-commerce seller protection essential to cover legal defense fees and potential compensation payouts.
How much does product liability insurance cost for a UK e-commerce startup?
Premiums are calculated based on several specific factors rather than a flat rate. Insurers look at your annual turnover, the types of products you sell, and where your customers are located. High-risk items like electronics or baby products will naturally command higher premiums than books or stationery. Working with a specialist broker helps you find a bespoke rate that fits your startup’s budget.
Does my policy cover me for sales made to customers in the USA?
Coverage for the USA and Canada is usually excluded from standard UK policies unless specifically requested. These regions are considered high-risk due to their litigious legal environments and high settlement costs. If you sell to North American customers, you must ensure your broker adds a territorial extension to your policy to remain fully protected and platform-compliant.
Can I get product liability insurance if I am a sole trader?
Yes, sole traders can and should obtain this insurance. Because you and your business are the same legal entity, your personal assets are directly at risk if a claim is made against you. Specialist product liability insurance for e-commerce seller coverage provides a vital safety net that protects your home and savings from the financial fallout of a product-related lawsuit.
What is a product recall extension and do I need it?
A product recall extension covers the logistical costs of removing dangerous or defective items from the market. This includes expenses for customer notifications, shipping, and disposal of the faulty goods. If you sell batches of items where a single defect could affect hundreds of customers, this extension is a pragmatic addition to your core policy.
Will my home insurance cover my e-commerce stock and liability?
Standard home insurance policies almost always exclude business-related stock and liability claims. If you run your business from home, you shouldn’t assume your domestic provider will cover a fire caused by your inventory or a claim resulting from a product you sold. You need a dedicated commercial policy to ensure your business activities are properly recognized and protected.
How do I prove to Etsy or Amazon that I have valid insurance?
You prove your coverage by providing a Certificate of Insurance (COI) issued by your broker. For Amazon specifically, the certificate must name “Amazon.com Services LLC and its affiliates and assignees” as an additional insured. It’s critical that the business name on your policy matches the legal entity name on your seller account exactly to avoid verification delays.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Jul 24, 2026 | Insurance
Fatalities from falls from height accounted for 25% of all workplace deaths in 2025/26, with 31 workers losing their lives. This statistic isn’t just a safety warning; it’s a major red flag for your business’s financial security. If your company doesn’t strictly adhere to the Work at Height Regulations 2005, your insurance for working at height regulations could be voided right when you need it most. Most tradespeople understand the physical risks of high-level work, but the fear of a rejected claim due to perceived negligence is a constant source of stress.
You shouldn’t have to guess whether your policy covers a specific ladder height or a complex scaffolding project. In this guide, you’ll learn how these regulations directly impact your insurance validity and how to keep your business protected. We’ll simplify the compliance process, explain the hierarchy of control, and ensure you have the right cover to meet HSE standards so you can focus on the job at hand with confidence. Our goal is to provide the clarity you need to manage high-risk tasks without the administrative burden or the worry of an invalid policy.
Key Takeaways
- Understand why the 2005 Regulations apply to any task where a fall could cause injury, regardless of the specific height or trade.
- Learn how to structure your Public Liability and Employers’ Liability policies to remain valid during high-risk site activities.
- Discover how following the HSE Hierarchy of Control can reduce your workplace risks and potentially lower your insurance premiums.
- Identify the common “Reasonable Precautions” clauses that can invalidate your insurance for working at height regulations if ignored.
- Find out how specialist brokers provide bespoke policy wording that accounts for your specific height limits and professional requirements.
Understanding UK Work at Height Regulations 2005
The Work at Height Regulations 2005 remain the cornerstone of Occupational safety and health for UK trades. Many business owners mistakenly believe these rules only apply to extreme heights or specific industries like construction. In reality, the law defines “working at height” as any activity where a person could fall a distance liable to cause personal injury. This includes working on a flat roof, using a ladder, or even standing near an opening in a floor. Whether you’re a roofer or a shopkeeper stacking high shelves, the same statutory duties apply to ensure every task is properly planned and supervised.
For insurers, these regulations serve as a critical benchmark for “reasonable care.” When you apply for insurance for working at height regulations, underwriters assume you’re operating within these legal boundaries. If an accident occurs and an investigation reveals a breach of these regulations, your insurer may argue that you failed to take reasonable precautions. This turns a standard claim into a legal and financial nightmare. Compliance isn’t just about avoiding HSE fines; it’s about protecting the very validity of your insurance policy.
Who is Covered by the Regulations?
The regulations cast a wide net. They apply to every employer, the self-employed, and any person who controls the work of others, such as a facilities manager or a building owner. These individuals are known as “duty holders.” Even if you hire casual workers or sub-contractors, you still hold a level of responsibility for the safety of the site. Minor tasks are often the most dangerous because they’re frequently overlooked. A quick five-minute job on a step-ladder is subject to the same planning requirements as a week-long scaffolding project. Neglecting these small tasks is a common way businesses find themselves in breach of the law.
The Intersection of Law and Liability Insurance
A breach of statutory duty can have a devastating impact on your Employers Liability Insurance or Public Liability policy. Insurers distinguish between “accidental” risks, which are covered, and “avoidable” risks caused by negligence. If you skip a risk assessment or use faulty equipment, the insurer might view the resulting fall as an avoidable event. For detailed support on navigating these complexities, you can access Specialist working at height insurance guidance to ensure your policy aligns with current HSE expectations. Don’t leave your coverage to chance by ignoring the finer points of the 2005 Regulations. Clear documentation and strict adherence to safety standards are your best defense against a rejected claim.
Essential Insurance Covers for High-Risk Height Work
High-level work carries risks that standard business policies often fail to address. When seeking insurance for working at height regulations, you must look beyond basic premiums to find cover that actually responds in an emergency. Public Liability Insurance is your first line of defense against third-party claims. If a tool falls from a scaffold and injures a passerby, or if a tile damages a neighboring roof, this cover handles the legal fees and compensation costs. Without it, a single mistake could bankrupt your business.
A common trap for tradespeople is the “height limit” clause. Standard policies might cap coverage at 10 or 15 meters. If you accept a contract for a four-story building or a tall chimney that exceeds this limit, your insurance is void for that entire project. You won’t just be underinsured; you’ll have no cover at all for that specific task. Always check your policy schedule for these restrictions before you step onto the site.
Public Liability vs. Employers’ Liability at Height
Falls from height are the primary cause of workplace deaths in the UK, accounting for 31 fatalities in 2025/26 alone. This makes Employers’ Liability Insurance a critical legal requirement for any business with staff or contractors. You must hold at least £5 million in cover to protect your business from staff injury claims. Failing to have this insurance can lead to fines of up to £2,500 for every single day you’re without cover. Adhering to The Work at Height Regulations 2005 is essential. Insurers view these rules as the minimum standard for safety; if an accident occurs and you’ve ignored these regulations, your policy might not pay out.
Professional Indemnity is equally important for safety consultants and scaffolding designers. If a design error causes a fall, standard liability cover won’t protect you from professional negligence claims. You need height-specific PI cover to ensure your advice or designs are fully backed by your insurer.
Specialist Add-ons and Endorsements
Specific projects require more than just liability cover. Contractors all risks insurance is vital for high-level builds, protecting the actual structure and materials from damage while the work is underway. You should also consider plant and machinery insurance for expensive equipment like cherry pickers, MEWPs, or owned scaffolding. For those in the building trade, understanding builders insurance essentials helps ensure every high-risk activity is accounted for. If you’re concerned about hidden height limits in your current policy, you can speak with a broker to clarify your coverage and ensure your business remains fully protected.
The Hierarchy of Control: Reducing Risk and Premiums
Insurance underwriters don’t just look at the industry you work in; they look at the specific steps you take to prevent a claim from ever happening. The “Hierarchy of Control” is a systematic approach to managing safety that directly influences your insurance for working at height regulations. By demonstrating a commitment to this hierarchy, you signal to insurers that your business is a lower risk, which can lead to more competitive premiums and more favorable terms. This methodology moves from the most effective level of protection to the least, and underwriters expect to see this logic applied to every project.
- Step 1: Avoid. The first priority is to eliminate the need to work at height. If you can use long-reach tools from the ground or assemble components before lifting them into place, you remove the risk entirely. Underwriters view avoidance as the ultimate risk management strategy.
- Step 2: Prevent. If work at height is unavoidable, you must use existing safe places of work or collective protection. This includes permanent guardrails or scaffolding that protects everyone on the site simultaneously.
- Step 3: Minimise. When collective protection isn’t enough, you must use equipment that reduces the distance and consequences of a fall. This often involves personal fall protection like safety nets or harnesses.
Following this structure is essential for compliance with HSE guidance on working at height. When a broker presents your business to an insurer, being able to document how you consistently apply these steps makes a significant difference in how your risk profile is perceived.
Risk Assessments as Insurance Documents
A risk assessment is more than a safety checklist; it’s a legal record of your “reasonable care.” If an accident occurs, your insurer will likely request these documents to verify that you were meeting your statutory duties. For 2026, a robust assessment must include the specific hazards of the site, the equipment selected, and the weather conditions. A competent person is someone who possesses the required combination of training, skills, experience, and knowledge to perform the specific task safely. Without a signature from such an individual, your risk assessment may carry little weight during a claim investigation.
Equipment Maintenance and Records
The Lifting Operations and Lifting Equipment Regulations (LOLER) require that all lifting equipment is fit for purpose and subject to regular thorough examinations. Keeping detailed inspection logs for ladders, scaffolding, and harnesses is vital for maintaining your coverage. If a piece of equipment fails and you cannot provide a recent inspection record, your insurer may argue negligence. Having comprehensive plant and machinery insurance complements your safety regime by covering the financial loss of damaged assets, but it doesn’t replace the need for strict maintenance logs. Consistent record-keeping is the bridge between a safe site and a valid insurance policy.
Why Falls at Height Insurance Claims Get Rejected
Insurance for working at height regulations is designed to provide a financial safety net, but that net only holds if you’ve followed the rules of the game. A common misconception is that having a policy automatically guarantees a payout following an accident. In reality, most commercial policies contain a “Reasonable Precautions” clause. This condition requires you to take all sensible steps to prevent injury or damage. If an investigation finds you ignored the hierarchy of control or failed to conduct a proper risk assessment, the insurer may argue you were “grossly negligent” and refuse the claim entirely.
Weather conditions also play a significant role in policy validity. If your team continues to work on scaffolding during high winds or icy conditions against HSE advice, you’re likely breaching your duty of care. Similarly, failing to provide or enforce the use of Personal Protective Equipment (PPE) can leave you exposed. While your Employers’ Liability Insurance is legally required to pay out to an injured employee, the insurer may later seek to recover those costs from you if they can prove you intentionally bypassed safety protocols.
Height Limits: The 10-Metre Trap
Many tradespeople discover too late that their standard policy includes a strict height limit, often set at 10 or 15 metres. This is known as the “10-metre trap” because it often covers a standard two-storey house but fails the moment you step onto a taller commercial building or a chimney. If an accident occurs at 11 metres on a 10-metre limited policy, the insurer has grounds to deny the entire claim. For those working on high-rise structures or as steeplejacks, a bespoke endorsement is essential to ensure your specific working environment is protected. You can find more detail on aligning your trade with the right cover in The Ultimate Guide to Builders Insurance in the UK.
The Danger of ‘Standard’ Aggregator Policies
Automated comparison sites are excellent for car insurance, but they often fail high-risk contractors. These “one size fits all” platforms rarely ask the nuanced questions required to identify industry-specific exclusions. A broker acts as a professional safeguard by identifying these hidden gaps and ensuring your policy wording matches the actual risks of your daily operations. They understand that a roofer in Staffordshire has different needs than a window cleaner in a city centre. To avoid the risk of a rejected claim, it’s always better to consult an expert broker who can tailor your coverage to your specific trade requirements.
Securing the Right Cover with Just Quote Me
Securing reliable insurance for working at height regulations requires more than just a quick search on a comparison site. Automated aggregators often miss the critical endorsements needed for high-risk trades, leaving you vulnerable to rejected claims. Just Quote Me acts as the human alternative, providing access to a broad network of top UK insurers and specialist underwriters who truly understand the risks of your industry. We don’t just sell policies; we build bespoke solutions that align perfectly with the Work at Height Regulations 2005, ensuring your cover remains valid even during the most demanding tasks.
For tradespeople in Stone, Staffordshire, and across the West Midlands, having a local partner offers a level of security that impersonal national firms cannot match. We combine our regional expertise with a pragmatic approach to safety and compliance. Our team manages the complex administrative burdens and policy documentation on your behalf, which allows you to focus on your projects without worrying about the fine print. We pride ourselves on being a steady hand in a complex market, offering straightforward advice that simplifies the insurance process.
Why Choose an Independent Broker?
Just Quote Me brings over 30 years of industry experience to every consultation. We’ve spent decades navigating the complexities of UK health and safety legislation, giving us the insight to spot hidden gaps in standard policies. We offer comprehensive business insurance solutions that go beyond the basics. Instead of relying on generic algorithms, we provide personalised risk assessments to ensure your height limits and liability requirements are accurately reflected in your policy wording. This tailored approach is your best defense against the “10-metre trap” and other common reasons for claim denial.
Get Started with Expert Advice
Our quote process is designed for maximum efficiency and clarity. We start by reviewing your current coverage to identify any potential weaknesses that could compromise your insurance for working at height regulations. This expert review ensures that your policy is not just a piece of paper, but a robust financial safeguard. Whether you are a sole trader or manage a large construction firm, we provide the professional restraint and expert guidance needed to protect your business. Don’t leave your compliance to chance when you can have a specialist broker manage the details for you.
Get Your Free Business Insurance Quote now
Take Control of Your High-Risk Protection
Compliance with the Work at Height Regulations 2005 is more than a legal box to tick; it’s the foundation of your business’s financial safety net. By following the hierarchy of control and maintaining meticulous inspection logs, you ensure that your insurance for working at height regulations remains fully valid when it matters most. Avoiding the common pitfalls of hidden height limits and generic policy exclusions is essential for any professional trade operating above ground level. These small details often make the difference between a successful claim and a devastating financial loss.
As an FCA Authorised and Regulated broker with over 30 years of experience, our Staffordshire-based expert team is here to help you navigate these complexities. We bridge the gap between strict legal requirements and practical, affordable coverage, acting as a human alternative to automated systems. You don’t have to manage these administrative burdens alone. Let us help you secure a policy that actually pays out in an accident, giving you the peace of mind to focus on your daily operations.
Secure your business with expert height-risk insurance today.
Get Your Free Business Insurance Quote now
Request a Call back for free Expert advice
Frequently Asked Questions
What is the maximum height I can work at without specialist insurance?
There is no universal height that triggers a need for specialist cover, but most standard policies include a fixed limit of 10 or 15 metres. If your project exceeds this distance, you must notify your broker to secure a specific endorsement. Working even a centimetre above your policy’s stated limit can completely invalidate your cover, leaving you personally liable for any damages or injuries that occur on-site.
Do the Work at Height Regulations apply to self-employed sole traders?
Yes, the Work at Height Regulations 2005 apply to self-employed sole traders just as they do to larger companies. If you are working at height where a fall could cause injury, you have a legal duty to plan the work properly and use the correct equipment. Maintaining high standards is vital because failing to comply can void your insurance for working at height regulations during a claim investigation.
Is Public Liability insurance enough for a roofing contractor?
Public Liability is essential for third-party damage, but it’s rarely enough for a professional roofing contractor. You also need Employers’ Liability if you use any staff, sub-contractors, or casual labour. Additionally, many roofers opt for Contractors All Risks to protect the building materials and works in progress from damage or theft while the project is active, ensuring every angle of the job is covered.
What happens if an employee falls and I don’t have Employers’ Liability insurance?
You face severe legal and financial consequences, including fines of up to £2,500 for every day you operate without the required cover. Beyond these statutory fines, you would be personally responsible for paying any compensation, legal fees, and medical costs arising from the employee’s injury. These costs often reach hundreds of thousands of pounds, which can easily bankrupt a small business or sole trader.
Does my insurance cover me if I use a ladder instead of scaffolding?
Your insurance covers you as long as you follow the hierarchy of control and HSE guidelines for equipment selection. Ladders should only be used for low-risk tasks of short duration where more stable equipment like scaffolding isn’t practical. If an accident occurs because you used a ladder for a high-risk, long-term task, an insurer might argue you failed to take reasonable precautions and deny the claim.
How can I lower my insurance premiums for high-risk height work?
Demonstrating a robust safety culture is the most effective way to lower your insurance costs over time. Providing proof of staff training, maintaining detailed equipment inspection logs, and consistently using collective protection shows underwriters that you are a lower risk. Using a specialist broker to present your risk profile accurately to insurers can also help secure more competitive rates than automated comparison sites.
Can an insurer refuse to pay if I didn’t complete a formal risk assessment?
Yes, insurers can refuse to pay claims if you cannot provide evidence of a formal risk assessment. Most policies include a clause requiring you to take all reasonable steps to prevent an accident. Without a documented assessment that identifies hazards and outlines control measures, the insurer may conclude that you breached your policy conditions by acting with negligence, making your insurance for working at height regulations ineffective.
Do I need special insurance for using a cherry picker or MEWP?
While your liability insurance covers the risks of operating the machinery, you need Plant and Machinery insurance to protect the equipment itself from damage or theft. You must also ensure the equipment has a valid LOLER inspection certificate. Using a cherry picker or MEWP without regular statutory inspections can lead to claim rejection if a mechanical failure causes a fall or injury on-site.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.
by jqm | Jul 23, 2026 | Insurance
Did you know that falls from height remained the leading cause of workplace fatalities in 2025/26, accounting for 31 deaths according to provisional HSE data? It’s a sobering statistic that explains why finding the right Working At Height insurance often feels like an uphill struggle. You likely already know the frustration of seeing premiums climb or feeling confused by “height limits” that seem to change from one policy to the next. It’s stressful to work when you’re worried that a single compliance oversight or a misunderstood clause could lead to a rejected claim.
This expert guide helps you navigate the complexities of high-risk liability to secure tailored protection for your business. We’ll show you how to manage your specific risks while ensuring you remain fully compliant with the Work at Height Regulations 2005. We’ll break down exactly what “height” triggers specialist requirements and explain how to find affordable cover that offers total peace of mind, so you can focus on the job at hand without the administrative headache.
Key Takeaways
- Understand why standard Public Liability often falls short and how Working At Height insurance acts as a critical extension for high-risk trades.
- Learn why exceeding your policy’s specified height limit by even one metre can lead to a rejected claim and total loss of cover.
- Identify how to accurately assess your maximum working height and equipment needs to ensure your policy matches your actual site activity.
- Discover the specific insurance requirements for high-level trades like roofing, scaffolding, and commercial maintenance crews.
- Find out how to secure bespoke protection that ensures full compliance with the Work at Height Regulations 2005.
What is Working At Height Insurance and Why is it Essential?
Working At Height insurance isn’t a standalone policy you buy off a shelf. It’s a specialist extension designed to bridge the gap left by standard tradesman cover. Many business owners assume their basic Public Liability insurance covers every task they perform. However, many “off-the-shelf” policies contain restrictive height limits, often capping out at just 3 or 5 metres. If you’re working on a roof or scaffolding above these limits, your insurer might refuse to pay out entirely. This makes specialized Working At Height insurance a necessity rather than an optional extra.
The financial stakes are high. Falls from height cost the UK economy over £956 million in 2023/24 according to the No Falls Foundation. For a small business, a single claim without the right cover isn’t just a setback; it’s a potential bankruptcy. Beyond safety, having the correct documentation is vital for growth. Larger contractors and local authorities won’t let you on site without proof that your insurance specifically covers the heights you’ll be reaching. It’s about more than just a certificate; it’s about securing your company’s future contracts.
The Core Components of a Robust Policy
A reliable Working At Height policy combines several layers of protection. Public Liability remains the foundation, protecting against third-party injury or damage to property. If you employ anyone, Employers’ Liability insurance is a legal requirement. It’s essential because falls are the leading cause of fatal injuries in the workplace. You should also consider Contractors All Risk insurance. This protects the ongoing project itself, such as a roof under repair, from accidental damage before completion.
Legal Requirements: The Work at Height Regulations 2005
Your insurance compliance should mirror your legal safety compliance. Under the broader framework of UK Health and Safety Regulations, you have a statutory duty to ensure all work is properly planned and supervised. Insurers will often check if you’ve followed these rules before settling a claim. If you haven’t performed a risk assessment or provided the right equipment, you’re at risk of claim rejection. The Work at Height Regulations 2005 serve as the primary legal benchmark for safety and compliance for any UK business performing tasks off the ground.
Who Needs Specialist Cover for High-Level Work?
Many tradespeople assume that specialist cover is only for those working on skyscrapers or major infrastructure projects. In reality, the need for Working At Height insurance extends to any professional whose work involves a risk of falling a distance liable to cause personal injury. This includes a wide array of sectors, from traditional construction to niche maintenance roles. If your daily tasks involve ladders, scaffolding, or mobile elevating work platforms (MEWPs), you must verify that your policy actually accounts for these specific activities and the heights involved.
Construction and Maintenance Specialists
For scaffolders and steel erectors, the risks are inherent and constant. These trades require high-limit protection because the potential for severe injury or property damage is significantly higher than in ground-level work. Similarly, HVAC engineers and roofers often find themselves navigating complex structures or pitched roofs where a standard liability policy might contain restrictive clauses. It’s vital to review your builders insurance to ensure it doesn’t include a “height limit” that leaves you vulnerable during a commercial contract. If you’re unsure about your current limits, seeking bespoke insurance solutions can clarify your position and fill any gaps in your cover.
Niche High-Risk Sectors
Beyond the building site, several niche sectors face unique challenges. Tree surgeons and arborists, for instance, deal with unpredictable natural environments and heavy machinery at height, necessitating specialized liability terms. Signage installation and billboard maintenance teams often work in busy public areas, where the risk to third parties is just as significant as the risk to the worker. Even security firms installing CCTV systems or alarms often work at heights that exceed the standard 3-metre or 5-metre limits found in basic policies. These professionals must ensure their insurance reflects the reality of their on-site duties.
Telecommunications and solar panel engineers also fall into this high-risk category. As the UK continues its push toward greener energy solutions, the number of engineers working on residential and commercial rooftops has surged. These roles require a deep understanding of safety protocols, and consulting HSE’s Guide to Working at Height is an excellent way to align your operational safety with legal expectations. Even in the hospitality and events sector, stage builders and lighting technicians often operate at height to create complex structures, proving that Working At Height insurance is a cross-industry essential for modern businesses.
The Critical ‘Height Limit’ Clause: What You Must Know
Standard policies are often built for ground-level trades. They frequently include a “hidden” height limit, usually set at 10 metres. This is the single biggest reason claims fail in high-risk sectors. If you’re working at 11 metres on a policy capped at 10, you aren’t just “partially” covered; you’re often not covered at all. Insurance companies view these limits as absolute. Exceeding them by a single metre can void your entire Working At Height insurance claim, leaving you to face the full financial burden of any accident.
Choosing between limited and unlimited cover depends on your typical contract. Limited cover is more affordable but requires you to be precise about your maximum reach. You must measure from the ground to the highest point of your work, not just where your feet are standing. If your projects vary in scale, unlimited height cover offers the security of knowing you’re protected regardless of the building’s size. To ensure your business is never left exposed during a complex project, Just Quote Me.
Negotiating Limits with a Broker
Automated quote engines are designed for simple, low-risk scenarios. They often fail to capture the nuance of high-level work, leading to policy wording that doesn’t actually fit your business. With over 30 years of experience, an independent broker understands how to structure bespoke policies that reflect your actual site activities. You can adjust your cover as your business grows. If you take on a taller project next month, it’s a simple matter of updating your policy rather than starting from scratch.
The Impact of Risk Assessments on Premiums
Documented safety protocols are your best tool for reducing insurance costs. When you provide detailed method statements that align with international principles like OSHA Fall Protection Standards, you demonstrate a commitment to safety that underwriters value. This isn’t just about ticking boxes; it’s about proving you manage risk effectively. A broker uses your risk assessment to prove your competence to underwriters. This professional validation often leads to better terms and lower premiums for your Public Liability insurance. It’s a pragmatic way to lower overheads while maintaining high safety standards.
How to Choose the Right Policy for Your Trade
Selecting the right Working At Height insurance requires a pragmatic approach that matches your daily site reality. A generic policy often leaves dangerous gaps in cover that only become apparent when you try to make a claim. To avoid this, follow a structured process to evaluate your specific needs. First, identify your maximum working height across all current and upcoming contracts. Don’t just estimate; check your project specifications. A solar panel installer working on commercial warehouses needs significantly different limits than a residential decorator. Second, evaluate your equipment. Whether you use ladders, scaffolding, or cherry pickers, your insurer needs to know the exact methods you use to access your workspace.
Third, check for Contractors All Risk insurance requirements. Larger builds often mandate this to protect the project itself, including materials and temporary structures, from damage during construction. Finally, consult an independent broker. Specialist markets for high-risk trades are complex, and a broker can compare options that automated sites simply cannot access. These experts understand the nuances of regional trade requirements, ensuring your policy wording is ironclad and compliant with the latest safety standards.
Tailoring Cover to Your Equipment
Your choice of access equipment dictates your risk profile and your premium. If you operate heavy machinery, you must distinguish between owned and hired-in plant. Standard liability often excludes damage to the machines themselves. You can secure specific plant and machinery insurance to cover these expensive assets against theft or accidental damage. Special considerations also apply to niche methods like rope access or cradles. These activities require bespoke policy wording to ensure your Working At Height insurance remains valid during specialized maneuvers. Don’t assume your equipment is covered by default; always declare it clearly to your broker.
Additional Protections to Consider
Liability is only one part of the puzzle for a modern trade business. If you provide design advice, site surveys, or consultancy as part of your high-level work, you likely need Professional Indemnity insurance. This protects you if a design flaw or professional error leads to a client’s financial loss. For sole traders, personal accident cover is a vital safety net. If an injury at height prevents you from working for weeks or months, this provides essential financial support to cover your bills. Additionally, high-level equipment is costly and often targeted by thieves. Ensure your van and tools insurance is sufficient to replace specialized gear if it’s stolen from your vehicle or a secure site.
To get a policy that actually fits your trade and provides real security, compare specialist insurance quotes with an expert today.
Why Just Quote Me is the Trusted Partner for High-Risk Trades
Choosing an insurance partner is as critical as choosing your safety gear. With over 30 years of industry experience, we understand that high-risk trades require more than just a standard policy document. We’ve built our legacy as an independent UK broker by focusing on bespoke solutions for those who work where others won’t. You won’t deal with anonymous call centres or automated scripts here. Instead, you get direct access to expert advice from our teams in Stone and Stafford. This human-centric approach ensures your Working At Height insurance is handled by someone who actually understands the nuances of your specific trade.
Our independence is your greatest asset. We aren’t tied to a single provider; instead, we have access to a broad network of top UK insurers who specialise in high-risk construction. This panel allows us to find cover for complex scenarios that mainstream insurers often decline. We manage the complex administrative burdens and provide efficient claims support, so you can focus on your projects. If the worst happens, you have a steady hand to guide you through the process, ensuring your business remains resilient. Our team acts as your advocate, dealing with underwriters directly to resolve issues quickly and fairly.
The Advantage of an Independent Broker
We leverage our 30-year history to find competitive pricing without compromising the depth of your cover. While automated engines might offer a lower headline price, they often hide exclusions that leave you vulnerable. We focus on regional expertise, serving the whole UK from our heartland in Staffordshire and the West Midlands. This local knowledge allows us to provide a level of service that larger, impersonal competitors simply can’t match. Whether you need comprehensive tradesman insurance or a specific height extension, we tailor every policy to your unique risk profile. Our Stafford and Stone offices are staffed by professionals who know the local industry inside out.
Get Started with a Specialist Quote
Securing the right protection doesn’t have to be a slow or frustrating process. We’ve streamlined our system to move you quickly from inquiry to action. Our name is more than just a brand; it’s a commitment to efficiency. When you need to secure a new contract or renew your existing cover, Just Quote Me. We provide the expert guidance you need to navigate high-risk liability with confidence. You can start by following our simple process to Get Your Free Business Insurance Quote now. We’ll help you secure the tailored Working At Height insurance your business deserves, backed by three decades of specialist knowledge.
Protect Your Business with Expert High-Risk Cover
Securing the right Working At Height insurance is about more than just legal compliance; it’s about protecting the long-term longevity of your business and your professional reputation. We’ve explored how standard policy height limits can leave you dangerously exposed and why accurate equipment declarations are essential for ensuring a valid claim. By understanding these critical nuances, you move from a state of administrative uncertainty to one of total operational confidence on every site you visit.
As an FCA Authorised Independent Broker with over 30 years of industry experience, Just Quote Me specialises in these complex, bespoke high-risk liability requirements. We provide a pragmatic, human alternative to impersonal automated systems, ensuring your policy wording is as robust as your own on-site safety protocols. You don’t have to manage these complex burdens alone.
You can secure your business with our expertise today and let our specialists build the specific cover your trade demands. We’re here to ensure you can reach the heights your projects require with the peace of mind you deserve.
Frequently Asked Questions
What is the standard height limit for tradesman insurance?
Standard tradesman policies often cap height limits at 3 or 5 metres by default. Some mid-range policies might extend this to 10 metres, but it’s rarely a standard feature for every trade. You must check your policy schedule specifically for a “Height Limit” clause to avoid gaps. If your work exceeds these standard markers, you’ll need a specialist extension to ensure your liability remains valid during the project.
Is Working at Height insurance a legal requirement in the UK?
There’s no specific law requiring a product named “Working at Height insurance,” but Employers’ Liability is a legal necessity for any business with staff or subcontractors. Additionally, the Work at Height Regulations 2005 mandate that you manage risks effectively. Most commercial clients and local authorities will refuse to hire you unless you can prove your Public Liability specifically covers the heights you’re working at.
Does my policy cover me if I use a ladder instead of scaffolding?
Your cover depends on the equipment you declared when setting up the policy. Some insurers have strict “ladder exclusions” for certain heights, preferring the use of more stable access like scaffolding or MEWPs. If your risk assessment justifies a ladder and your policy doesn’t explicitly forbid it, you’re usually covered. Always ensure your equipment choice aligns with the safety protocols your insurer expects for your specific trade.
Can I get one-off insurance for a single high-level project?
Yes, it’s possible to secure short-term cover or a temporary extension to your existing annual policy for a specific project. This is a practical solution if you typically work at ground level but have secured a one-off contract for high-level maintenance or roofing. Contacting a broker is the fastest way to arrange this “top-up” cover without renegotiating your entire yearly premium or switching providers entirely.
What happens if I work above the height limit specified in my policy?
Working even one metre above your policy limit can lead to a total claim rejection. Insurers treat height limits as absolute conditions of the contract. If an accident occurs at 12 metres on a 10-metre limited policy, you’ll likely be responsible for all legal costs and compensation payments yourself. It’s a high-stakes risk that can easily lead to business bankruptcy if a major incident occurs.
Does working at height insurance cover my tools if they fall?
Working At Height insurance primarily focuses on liability for injury to people or damage to third-party property. While it covers you if a dropped tool hits a car or a pedestrian, it won’t pay to replace your own damaged equipment. For that, you need a specific tool insurance extension. This ensures that expensive high-level gear is protected against accidental damage or theft from the site or your vehicle.
How much does working at height insurance cost for a sole trader?
Costs vary based on your specific trade, the maximum heights you reach, and your previous claims history. A sole trader performing minor gutter repairs at 5 metres will pay a different rate than a roofer working at 15 metres. Because high-risk work is assessed on an individual basis, the most efficient way to find an accurate price is to request a tailored quote based on your actual contract needs.
Can a broker help if I’ve been refused cover elsewhere due to high-risk work?
Absolutely. Independent brokers have access to specialist underwriting panels that automated quote engines simply can’t reach. If a mainstream insurer has refused you due to “high-risk” activities like rope access or scaffolding, a specialist broker can often find a bespoke solution. They understand the nuances of the industry and can present your risk assessments to insurers to prove your competence and safety standards.
Article by
Just Quote Me
JustQuoteMe Ltd is an independent UK insurance brokerage specialising in business and personal insurance solutions. With over 35 years of industry experience, the company provides tailored insurance cover for businesses, landlords, tradespeople, hospitality venues, fleets, and individuals across the UK. Known for its personal service, expert advice, and competitive premiums, JustQuoteMe Ltd works with leading insurers to deliver bespoke policies designed around each client’s unique needs. The company is authorised and regulated by the Financial Conduct Authority (FCA No. 586607) and has built a reputation for trusted, straightforward insurance guidance and long-term client relationships.