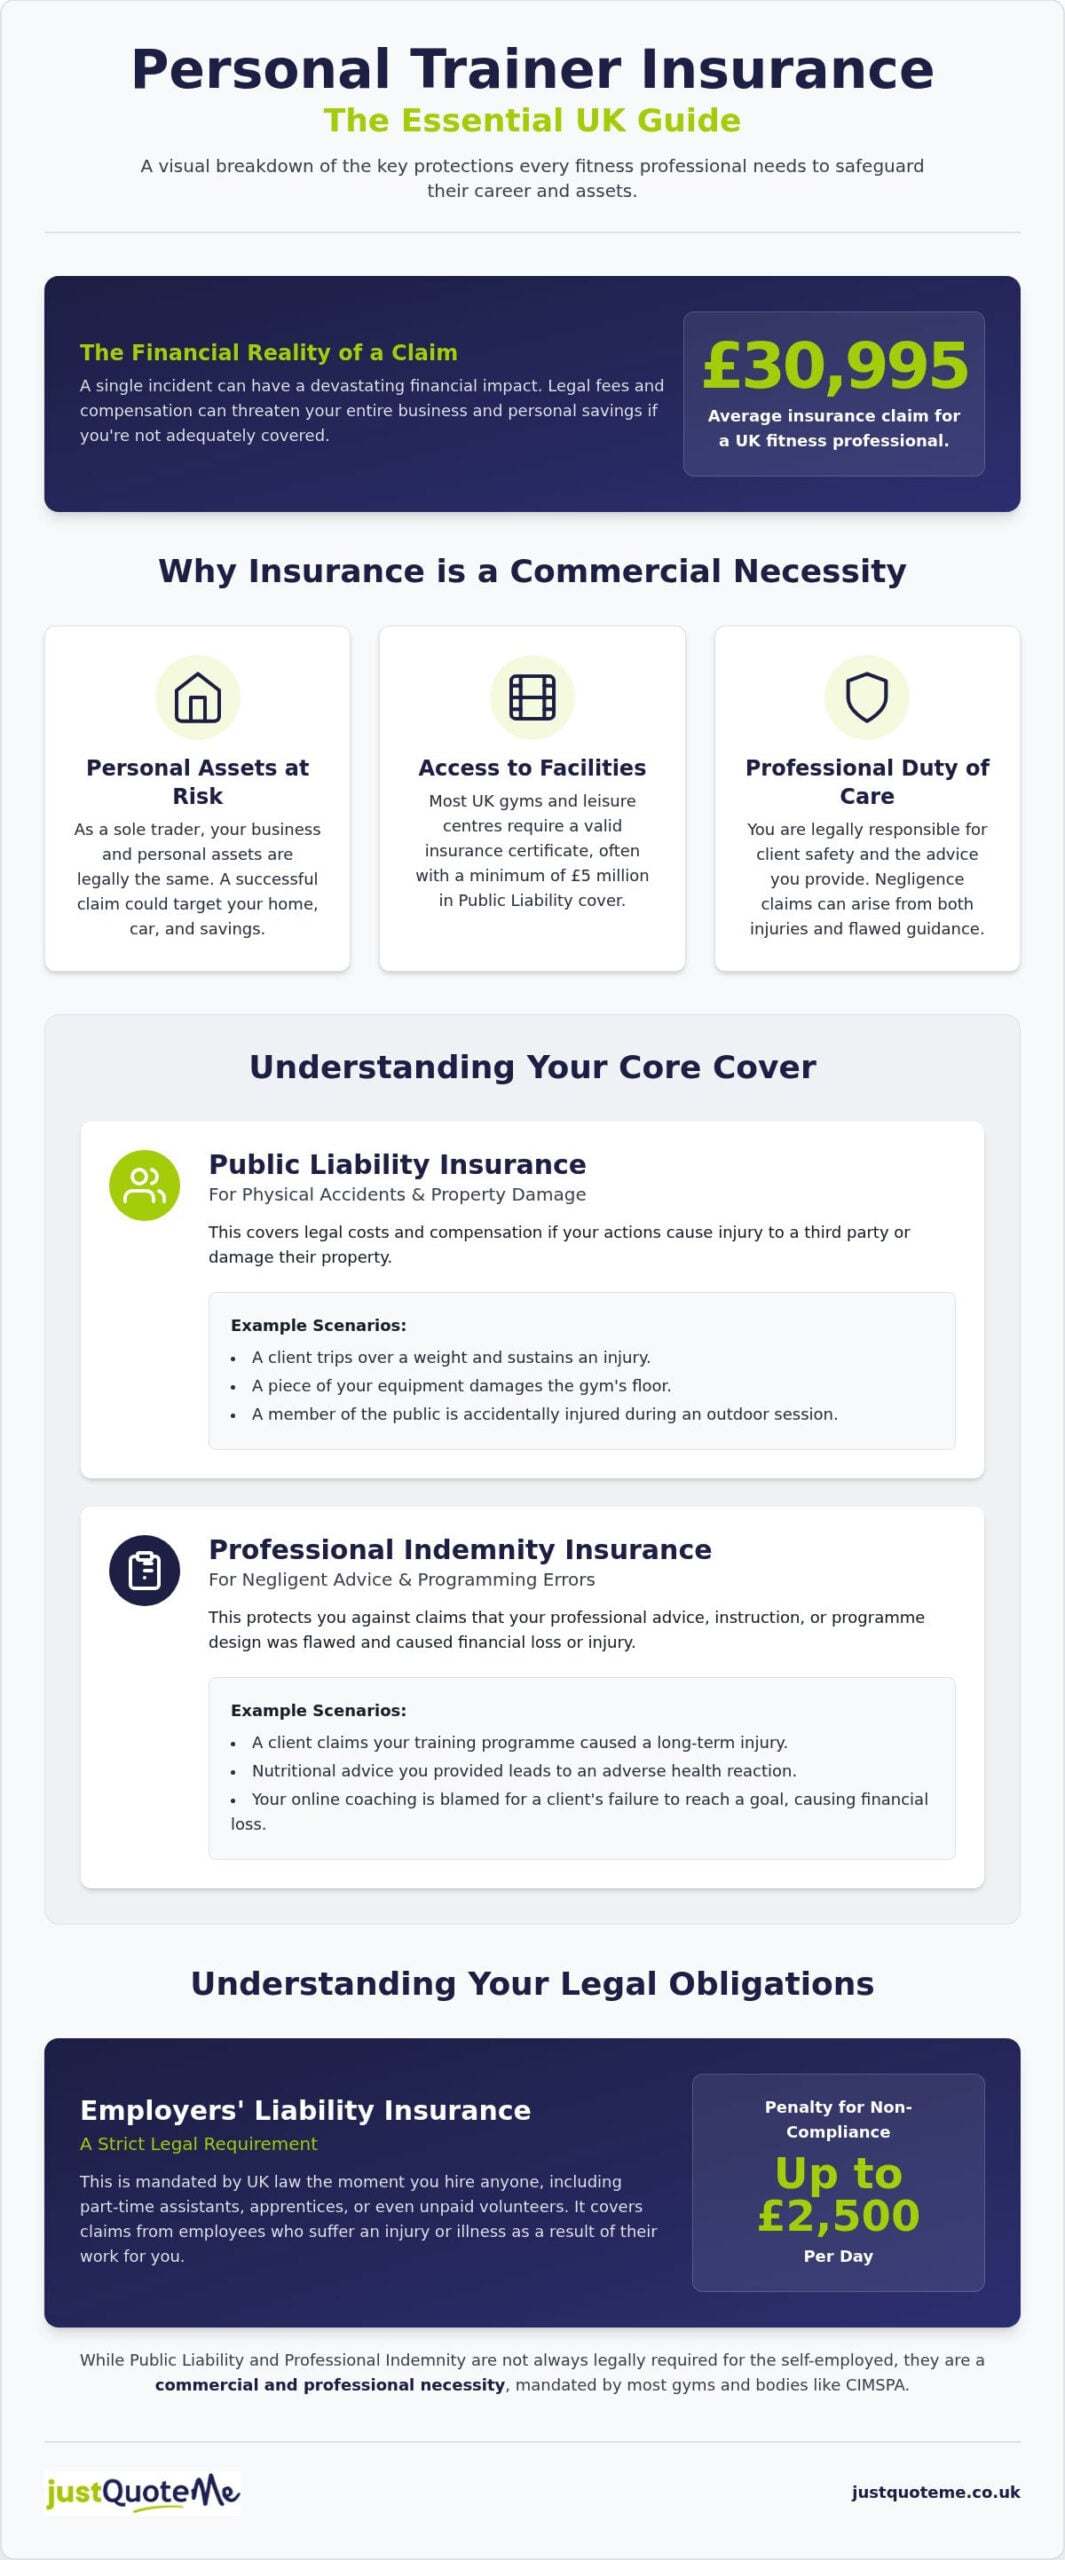
Did you know the average insurance claim for a UK fitness professional recently reached £30,995? For many, a single injury claim or a piece of misunderstood advice can lead to a financial burden that threatens their entire career. Finding the right personal trainer insurance uk shouldn’t feel like a workout in itself, yet the confusion between Public Liability and Professional Indemnity often leaves trainers feeling exposed.
We understand that you want to protect your business and satisfy gym requirements without spending hours deciphering legal jargon. You need to know that if a client gets injured or your advice is questioned, your policy will actually pay out. This guide simplifies the complex world of fitness insurance, ensuring you get the protection you need at a price that makes sense for your budget.
We will explore the specific policies required for 2026, including the latest CIMSPA standards and the essential cover needed for online coaching. By the end of this article, you will have a clear roadmap to securing your business. This allows you to get back to what you do best: changing lives through fitness with total peace of mind.
Key Takeaways
- Understand why operating as a sole trader puts your personal assets at risk and how the right cover provides a vital safety net.
- Learn the critical difference between Public Liability for physical accidents and Professional Indemnity for claims involving negligent advice or programming.
- Determine if you are legally required to hold Employers’ Liability insurance or if you need additional protection for your portable fitness equipment.
- Discover how to secure comprehensive personal trainer insurance uk that satisfies gym contracts without overpaying for unnecessary extras.
- Find out how using an independent broker with 30 years of experience helps you find bespoke cover tailored to your specific training niche.
Why Personal Trainer Insurance is Essential in the UK
Securing personal trainer insurance uk is a suite of policies designed to protect fitness professionals from legal and financial claims. Personal trainer insurance is the safety net for your professional advice and physical interactions. Without it, you are exposed to significant risks that could derail your career before it truly gains momentum.
Operating as a sole trader brings specific risks. In this business structure, there’s no legal separation between your personal assets and your professional liabilities. If a client sues you and wins, your home, car, and savings could be at risk to cover the settlement. This makes comprehensive cover a non-negotiable part of your business setup.
UK gym requirements are another major factor. Most commercial facilities and leisure centres won’t grant you access to train clients without seeing a valid insurance certificate. They typically require a minimum of £5 million in Public Liability Insurance to protect their own interests and ensure that any accidents on their premises are covered.
The concept of ‘Duty of Care’ is central to your role. You’re responsible for client safety during every rep and for the accuracy of any nutritional guidance you provide. If a client follows your programme and suffers a health complication or injury, they may seek compensation for negligence. Professional cover ensures you have the resources to defend your expertise.
The Risks of Training Without Cover
The financial impact of a claim is significant. Data shows the average personal trainer claim recently reached £30,995. Even if you haven’t done anything wrong, the cost of a legal defence can run into thousands of pounds. Beyond the money, a single high-profile incident can cause irreparable reputational damage. Alongside this, a lack of insurance can lead to contractual breaches that void your lease or gym agreement, effectively shutting down your business.
Is Personal Trainer Insurance a Legal Requirement?
Strictly speaking, Public Liability is not mandated by UK law for self-employed trainers. However, Employers Liability Insurance is a legal requirement the moment you hire an assistant, apprentice, or even an unpaid helper. Failing to hold this cover can result in fines of up to £2,500 per day. While some policies aren’t “law,” they are a commercial necessity in 2026. Professional bodies like CIMSPA mandate that practitioners hold valid Professional Indemnity Insurance and public liability for all sessions, including online coaching and free taster classes. To qualify for most policies, you’ll also need a recognised Level 3 Diploma in Personal Training.
Public Liability vs. Professional Indemnity: Knowing the Difference
Understanding the nuances of personal trainer insurance uk begins with distinguishing between physical accidents and professional errors. While these two pillars of protection often overlap on the gym floor, they address fundamentally different legal threats. One protects your bank balance when a client trips over a dumbbell; the other protects your reputation when your training programme is blamed for a chronic injury.
Personal trainers uniquely need both because they operate at the intersection of physical space and professional instruction. You aren’t just providing a venue; you’re providing life-altering advice. If you’re unsure which level of cover matches your specific training style, you can consult an independent broker to tailor a policy to your needs.
Public Liability Insurance for Fitness Professionals
This policy covers third-party injury and property damage. If a client slips on a wet floor in your studio or a heavy weight plate damages the gym’s expensive flooring, Public Liability Insurance provides the necessary cover. Historically, many trainers opted for £1 million in coverage. However, in 2026, most major UK gym chains and local authorities require a minimum of £5 million or even £10 million to allow you on-site. This shift reflects the rising costs of legal fees and medical compensation payouts across the fitness industry.
Professional Indemnity: Protecting Your Expertise
While liability covers the ‘where,’ Professional Indemnity Insurance covers the ‘what.’ It protects you against claims of negligence, bad advice, or a breach of professional duty. This is critical for trainers who provide bespoke nutritional plans or specialised rehabilitation programmes. Even the Financial Conduct Authority guidance highlights the importance of indemnity for firms providing professional services, as it ensures clients have recourse if advice leads to a loss or injury.
Consider a real-world scenario. You design a high-intensity deadlift programme for a client. Three weeks in, the client suffers a severe back injury and claims your instructions were technically flawed or the progression was too aggressive for their level. This isn’t a ‘trip or slip’ accident. It is a challenge to your professional expertise and the quality of your programme. Without PI cover, you would be responsible for defending your methodology and paying any resulting damages out of your own pocket.
Key Coverage Extensions for Modern PTs
The fitness industry has evolved beyond the traditional gym floor. Modern trainers often manage hybrid businesses that include mobile sessions, small teams, and digital platforms. Because your business is multifaceted, your personal trainer insurance uk must provide more than just the basic protections. Standard policies often leave gaps when it comes to hiring staff, carrying expensive equipment, or handling sensitive client data.
Specialised extensions ensure that your specific way of working is fully protected. If you provide sports massage or manual therapy alongside your coaching, you must verify that your policy includes “hands-on” treatments. Standard instruction-based cover rarely extends to physical manipulation. Likewise, protecting your digital footprint is no longer optional if you store client health data or progress photos on your devices.
Employers’ Liability: The Legal Must-Have
If you employ anyone to help run your business, Employers’ Liability Insurance is a legal requirement in the UK. This mandate applies even if you only hire part-time admin staff, apprentices, or unpaid helpers. Many trainers believe they are exempt because they use subcontractors. However, the ‘Control Test’ is the deciding factor. If you set their hours, provide the equipment, and direct exactly how the work is done, the law likely views them as employees. Operating without this cover is a massive risk. You can be fined £2,500 for every single day you trade without a valid certificate.
Equipment and Outdoor Training Risks
Mobile trainers often carry thousands of pounds worth of weights, benches, and tech in their vehicles. A common mistake is assuming that home or standard car insurance will cover these items. Most personal policies have strict “business use” exclusions that leave your kit unprotected if it’s stolen from your car or damaged in transit. You need dedicated Van and Tools Insurance to ensure your livelihood isn’t wiped out by a single theft.
Training in public spaces also brings unique challenges. If you use local parks for boot camps or one-on-one sessions, most UK councils require you to hold a permit. To get this permit, you’ll need to prove you have a specific level of liability cover. Councils often demand higher indemnity limits to protect public property and other park users. Having the right extension ensures you can train anywhere with total confidence.
Get Your Free Business Insurance Quote now
Request a Call back for free Expert advice
How Much Does Personal Trainer Insurance Cost in 2026?
Determining the exact price of personal trainer insurance uk involves several variables. While some providers offer generic “from” prices, these rarely reflect the reality of a bespoke fitness business. This is where the ‘Broker Advantage’ becomes clear. Instead of buying a rigid, off-the-shelf policy direct from an insurer, an independent broker searches a broad network of top UK insurers to find the best value for your specific risk profile. We manage the complex administrative burden so you can focus on your clients.
Your location also plays a part in the final calculation. Training clients in high-density urban areas like London or Birmingham can lead to slightly higher premiums due to the increased volume of foot traffic and higher local legal costs. For a broader look at how these variables interact with specific policy types, you can read our guide on How Much Does Public Liability Insurance Cost in the UK?
Factors That Influence Your Premium
The level of cover you choose is the primary driver of cost. As discussed earlier, many gyms now mandate £5 million or £10 million in Public Liability cover, which naturally costs more than a basic £1 million policy. Your specialisms also matter. Insurers view training professional athletes, children, or the elderly as higher risk categories, which can adjust your premium. Your claims history is equally vital; having a clean record over several years demonstrates reliability and often results in lower rates. Finally, your annual turnover and the number of clients you train provide insurers with a scale of your “exposure” to potential claims.
How to Keep Your Insurance Costs Low
You can actively manage your premiums by demonstrating a commitment to safety. Maintaining thorough risk assessments and documenting your safety protocols shows insurers that you are a lower risk. When it comes to payment, choosing an annual lump sum is usually cheaper than monthly instalments. Monthly plans often include interest charges that increase the total cost over the year. However, the biggest mistake is “under-insuring” to save a few pounds. Saving a small amount on your monthly premium is a poor trade-off if a £30,000 claim isn’t fully covered. To ensure you aren’t paying for cover you don’t need, you should get expert advice from a broker who understands the fitness sector.
Get Your Free Business Insurance Quote now
Request a Call back for free Expert advice
How to Get the Right Policy with Just Quote Me
Choosing the right partner to protect your livelihood is a decision that shouldn’t be left to a computer algorithm. Just Quote Me has been a trusted advisor in the industry for over 30 years. Since our founding in 1989, we’ve focused on providing a human-centric alternative to the impersonal world of automated comparison sites. As an FCA-authorised firm, we offer the reliability and security you need to train your clients with total peace of mind.
Our roots are firmly planted in Newcastle-under-Lyme and Staffordshire, but our reach extends across the entire United Kingdom. We combine local service values with the power of a national network. This allows us to offer bespoke personal trainer insurance uk that fits your specific niche, whether you’re a mobile coach or a studio owner. We don’t believe in off-the-shelf solutions because no two training businesses are identical.
Our Simple 3-Step Quote Process
We’ve refined our system to be as efficient as possible. First, you provide your basic business details and any training specialisms, such as pre-natal fitness or rehabilitation coaching. Second, we search our extensive panel of top UK insurers to find the best fit for your specific requirements. Finally, you receive your bespoke quote. You can choose to buy online or speak directly to one of our experts for tailored advice if your business model has unique complexities.
Why Choose an Independent Broker Over a Comparison Site?
The primary advantage of working with an independent broker is human expertise. Automated sites often miss the critical details that make your business unique. If you offer specialized services like sports massage or online programming, a generic policy might leave you exposed. We understand these nuances and ensure your Public Liability Insurance and Professional Indemnity Insurance are watertight. We also stand by you if you ever need to make a claim, acting as your advocate rather than just a middleman.
Finding comprehensive cover doesn’t have to be an administrative burden. We manage the complex fine print so you can get back to the gym floor. Our team is dedicated to finding you cover that doesn’t break the bank while ensuring you are fully protected against the risks of 2026.
Get Your Free Business Insurance Quote now
Request a Call back for free Expert advice
Secure Your Fitness Business Today
Operating as a fitness professional in 2026 requires a proactive approach to risk management. The right personal trainer insurance uk provides a vital safety net that separates your personal assets from professional liabilities. You now understand the critical difference between Public Liability for physical accidents and Professional Indemnity for your expert advice; you also know the legal necessity of Employers’ Liability if you grow your team.
Don’t let the confusion of the fine print hold your business back. Just Quote Me is an FCA-authorised independent broker with over 30 years of industry experience. We are here to simplify the administrative burden so you can focus on your clients. Whether you need a bespoke policy for a unique niche or high-limit cover for a major gym contract, we search the market to find the best value for you.
Get Your Free Business Insurance Quote now
Request a Call back for free Expert advice
Take the final step toward total peace of mind and get back to the gym floor with confidence. Our team is ready to help you secure the protection your business deserves.
Frequently Asked Questions
Is personal trainer insurance a legal requirement in the UK?
Public Liability insurance is not a statutory legal requirement for self-employed trainers, but Employers’ Liability is mandatory if you hire any staff. However, having personal trainer insurance uk is a commercial necessity. Most gyms and local authorities will not permit you to train on their premises without seeing a valid insurance certificate, as it protects both you and the venue from significant financial loss.
What is the difference between Public Liability and Professional Indemnity?
Public Liability covers physical accidents, such as a client tripping over a kettlebell or you damaging a gym’s equipment. Professional Indemnity protects you against claims regarding your professional expertise, such as a client claiming your exercise programme caused a long-term injury. Since personal training involves both physical space and professional instruction, most trainers require a policy that bundles both protections for full security.
Does my insurance cover me for outdoor training in parks?
Most comprehensive policies include cover for outdoor sessions in public spaces, provided you have the necessary permits from the local council. Councils typically require a minimum of £5 million in Public Liability cover before they allow you to run boot camps or one-on-one sessions in parks. It is essential to confirm that your policy does not have a “premises only” restriction that could void your cover outdoors.
Am I covered if I provide nutritional advice to my clients?
Nutritional advice is generally covered under Professional Indemnity, as long as the guidance remains within the scope of your Level 3 qualification. If you provide specialised dietetic advice or specific meal plans for medical conditions, you must ensure your policy includes this specific extension. Just Quote Me can help you verify that your nutritional coaching is fully protected within your bespoke policy wording.
How much Public Liability cover do I actually need (e.g., £1m or £5m)?
While £1 million was once the industry standard, most major UK gym chains and local councils now mandate a minimum of £5 million. Some high-end facilities may even require £10 million to account for rising legal and medical compensation costs. Opting for a higher limit ensures you can accept contracts at any facility without needing to adjust your policy mid-term, providing greater professional flexibility.
What happens if a client gets injured during a session?
If an injury occurs, you should record the incident in an accident book and notify your insurance broker immediately. Even if the client does not suggest they will take legal action, early notification is a requirement of most policies. Your insurer will then provide the legal support needed to investigate the claim and manage any potential compensation, allowing you to continue running your business with minimal disruption.
Does my insurance cover me for online or virtual training sessions?
Online coaching often requires a specific extension to a standard gym-based policy. This covers you for remote programming, live-streamed workouts, and pre-recorded video content. You should also check if your policy has territorial limits, as training clients based outside the UK may require additional cover. Ensuring your digital services are declared to your broker is vital for maintaining a valid policy in 2026.
