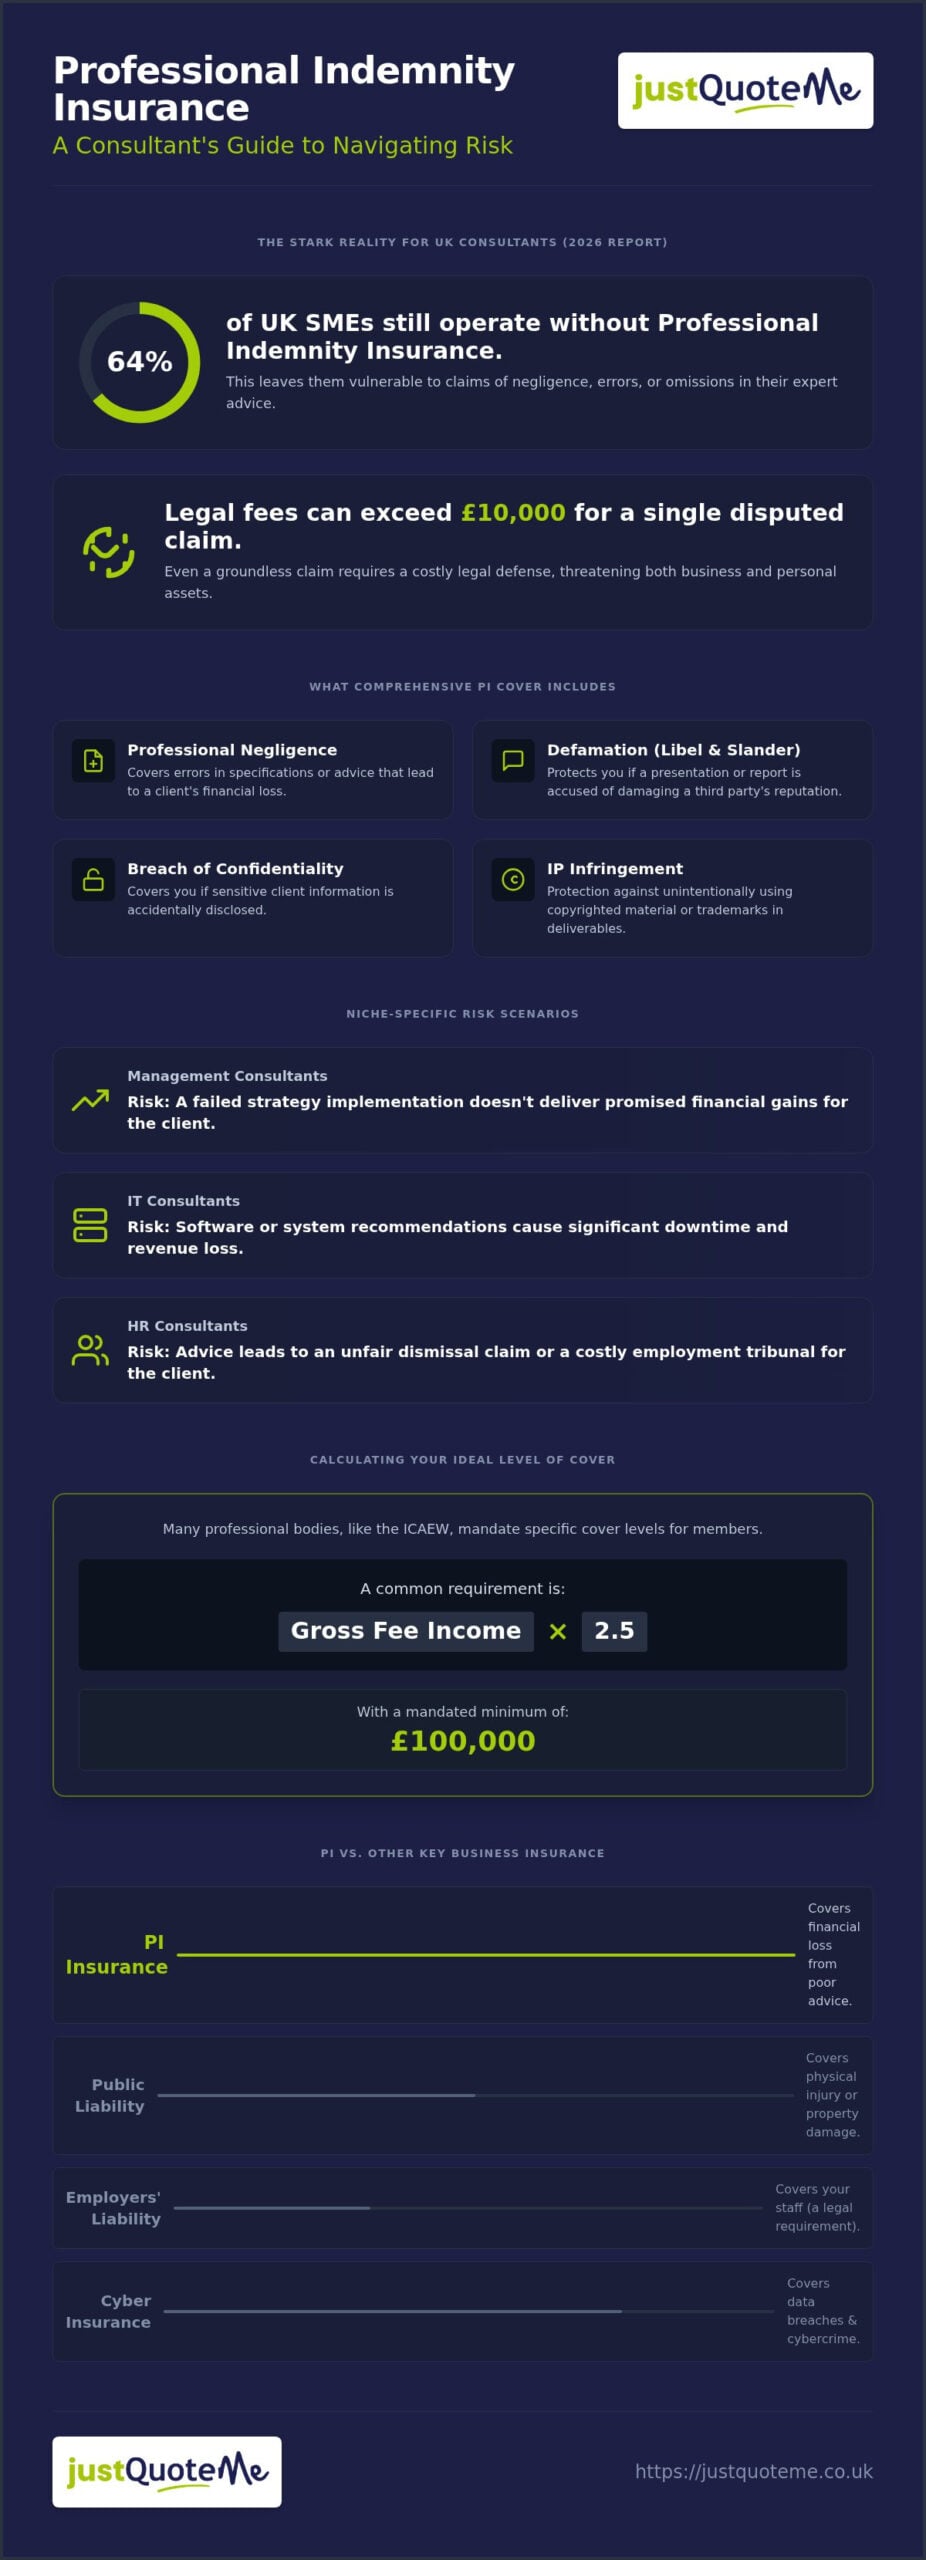
A 2026 report from the Association of British Insurers reveals that 64% of UK SMEs still operate without professional indemnity insurance. For a consultant, your expertise is your most valuable asset, yet a single piece of disputed advice can lead to legal fees exceeding £10,000. We understand the pressure of staring at a new contract that demands specific indemnity levels you aren’t sure you have. It’s common to feel caught between the fear of a costly court battle and the confusion of determining exactly how much cover is “enough” for your specific niche.
This guide will help you secure the right professional indemnity insurance for consultants, ensuring you meet every contractual obligation while protecting your personal assets. We’ll break down the latest 2026 market trends, from the importance of “claims-made” wording to the necessity of run-off cover. You will discover how to navigate the current soft market to find tailored protection that doesn’t slow your business down. By the end of this article, you’ll have a clear roadmap to achieving full compliance and total peace of mind. To simplify your search, Just Quote Me.
Key Takeaways
- Understand how professional indemnity insurance for consultants protects your practice against claims of negligence, errors, or omissions in your expert advice.
- Identify the specific risks included in comprehensive policies, such as defamation and professional mistakes, to ensure no gaps in your defensive strategy.
- Determine the correct level of indemnity by assessing your maximum potential liability and aligning with standard UK contractual requirements.
- Discover the advantages of using an independent, FCA-authorised broker to access bespoke cover from a broad network of top UK insurers.
- Learn how to simplify the administrative burden of insurance by using a human-centric approach that prioritises speed and reliability.
Understanding Professional Indemnity Insurance for UK Consultants
Professional indemnity insurance for consultants is a specialized form of Professional liability insurance designed to protect your business if a client claims your advice or services caused them financial loss. Unlike a manufacturer who risks physical product defects, your primary exposure lies in the intellectual delivery of your expertise. If a client alleges negligence, error, or omission in your reports or strategies, you face significant legal and financial repercussions. This cover acts as a financial safety net, managing the costs of legal defense and any settlements awarded against you.
The 2026 UK market has shifted significantly. Clients are more risk-aware than ever; almost every corporate contract now includes professional indemnity as a non-negotiable prerequisite. Consultants are uniquely exposed because their “product” is intangible. If a strategy fails to deliver expected ROI or a specification leads to a project delay, the client looks for someone to blame. This differs from product-based businesses where physical failures are often easier to define and quantify. You often cannot even step through the door of a new project without proving you have adequate cover in place.
Why Consultants Cannot Afford to Ignore PI Cover
Even if a claim is entirely groundless, the cost of a legal defense can be crippling. Research indicates that legal fees for defending a professional indemnity claim often exceed £10,000. To help manage these risks through expert commercial legal advice, you can visit MAR Legal. As a consultant, you hold a “duty of care” toward your clients. If they believe you failed that duty, they have a legal right to seek compensation. Many professional bodies, such as the ICAEW, mandate specific levels of cover for their members. They require coverage equal to 2.5 times gross fee income, with a minimum of £100,000. This isn’t just about protecting your bank account; it’s about maintaining your professional standing and license to operate.
It is vital to distinguish PI from other common protections. While Public Liability Insurance covers physical injury or property damage, it does not cover financial losses resulting from poor advice. Similarly, Employers Liability Insurance is a legal requirement if you have staff, but it protects them, not your professional work. For digital advisors, Cyber Liability Insurance acts as a necessary partner to PI, covering data breaches that your indemnity policy might exclude. When searching for professional indemnity insurance for consultants, remember that bespoke packages provide better value than generic, standalone policies. To ensure your coverage is seamless and your administrative burden is minimal, Just Quote Me.
What Does Consultant Professional Indemnity Insurance Actually Cover?
Consultant professional indemnity insurance isn’t just about paying legal fees. It’s a comprehensive shield against the specific risks inherent in providing expert advice. Most policies center on professional negligence, which covers errors in specifications or advice that lead to a client’s financial loss. However, modern policies for professional indemnity insurance for consultants extend much further. They include protection against defamation, covering you if a presentation or report is accused of libel or slander. Breach of confidentiality is another critical component, protecting you if sensitive client data is accidentally disclosed. Finally, intellectual property infringement cover ensures you aren’t left vulnerable if you unintentionally use copyrighted material or trademarks in your deliverables.
Niche-Specific Risk Scenarios
Different consulting fields face unique threats that generic policies might miss. For management consultants, a claim might arise from a failed strategy implementation that doesn’t deliver the promised financial gains. IT consultants often face liability if their software recommendations cause significant system downtime, leading to lost revenue for their clients. HR consultants carry risks related to advice that leads to unfair dismissal claims or employment tribunals. Understanding these nuances is why we recommend a professional indemnity insurance policy tailored to your specific sector rather than a one-size-fits-all solution.
Standard Exclusions to Watch Out For
While the cover is broad, it isn’t infinite. Policies won’t cover deliberate acts of dishonesty, fraud, or criminal behavior. You also cannot claim for circumstances you were already aware of before the policy started. It’s vital to understand the “claims-made” nature of these policies. This means the policy active at the time the claim is filed is the one that responds, not the policy you had when the work was originally performed. This is why continuous cover is so important. Professional bodies, such as the Chartered Institute of Taxation (CIOT) requirements, emphasize this continuity to ensure members remain compliant with their standards even after a project ends. If you’re unsure if your current policy covers these specific gaps, you can speak with a specialist to review your unique risks and find a more robust solution.
Calculating Your Risk: How Much PI Cover Does a Consultant Need?
Choosing the right level of professional indemnity insurance for consultants requires a pragmatic assessment of your worst-case scenario. It isn’t just about the fees you charge; it’s about the financial damage your advice could potentially cause. If you’re advising a small business, a mistake might cost a few thousand pounds. However, if you’re consulting for a multinational corporation, that same error could lead to millions in lost revenue or project delays. You must evaluate the scale of your clients and the complexity of the projects you handle to determine a safe limit.
Contractual obligations often dictate your starting point. In the current 2026 UK market, it’s standard for corporate clients to mandate a minimum indemnity limit of £1 million, with many larger contracts pushing this requirement to £5 million or more. This is a common requirement when securing high-level IT and accountancy placements through specialist agencies like HT Recruit Ltd, where the financial stakes of a project are significant. Signing a contract without the corresponding insurance level can leave you in breach of your agreement before you’ve even started work. Beyond the potential compensation, you have to factor in the legal costs of defending a claim in the UK court system. With legal fees for even groundless claims frequently exceeding £10,000, your cover needs to be robust enough to handle high-end solicitor fees alongside any eventual settlement.
Factors That Influence Your Premium
Your industry sector plays a significant role in determining your premium. High-risk fields like structural engineering or financial services naturally attract higher rates than general administrative consulting. Your annual turnover is another key metric; insurers view higher revenue as an indicator of higher risk exposure. Finally, your claims history is scrutinized. A clean record helps you secure more competitive 2026 rates, while previous incidents can lead to higher premiums or more restrictive terms.
The “Any One Claim” vs. “Aggregate” Limit Debate
Understanding how your limit applies is just as important as the amount itself. Any One Claim cover is the maximum the insurer will pay for each individual claim made during the policy period. This is generally the preferred option for consultants because it ensures that if you face multiple separate claims, your pot of insurance doesn’t run dry. In contrast, an “Aggregate” limit is the total amount available for all claims combined during the policy year. If one large claim exhausts an aggregate limit, you’re left unprotected for the remainder of the term. To ensure your policy structure matches your risk profile and provides the best value, professional indemnity insurance should be sourced through a specialist who understands these nuances. Just Quote Me.
Beyond the Premium: Choosing the Right Policy and Broker
Buying professional indemnity insurance for consultants shouldn’t be a transaction with a faceless website. While direct insurers often promote their own platforms, they’re limited to their own products. This approach restricts your choices and might leave you with a policy that doesn’t quite fit your niche. An independent broker acts as your advocate, scanning a broad network of top UK insurers to find the most competitive and comprehensive cover. Dealing with an FCA-authorised firm is non-negotiable; it ensures you’re protected by strict industry regulations and that the advice you receive is both professional and transparent.
Off-the-shelf policies often use generic language that might not align with your specific “scope of works.” If your consultancy involves specialized advice, you need a bespoke policy that mirrors your actual daily risks. The real value of your insurance appears when you need to make a claim. Accessing an award-winning claims service means you have a steady hand to guide you through complex legal disputes. This support is vital for maintaining your business reputation while the administrative burden of a claim is managed on your behalf. To find a policy that truly protects your practice, Just Quote Me.
The Local Broker Advantage in Staffordshire and the West Midlands
Regional expertise provides a level of service that automated systems can’t match. For consultants in Staffordshire and the West Midlands, working with a broker who understands the local business landscape is a distinct advantage. You have the accessibility of being able to visit an office in Stone or Stafford to discuss your requirements face-to-face. This human-centric approach builds trust and ensures your insurance partner understands the specific challenges of operating within our region.
How to Compare Professional Indemnity Quotes Effectively
When comparing quotes, it’s essential to look beyond the premium. Check the excess levels carefully; a lower price might hide a prohibitively high excess that you’d have to pay in the event of a claim. Evaluate the reputation and financial strength of the underlying underwriter to ensure they’re reliable. You should also check for “Run-off” cover options. Because PI is a claims-made policy, you’ll need this protection for several years after you retire or close your business to cover any late-surfacing claims. If you’re ready to see how a bespoke approach can benefit your practice, you can get a professional indemnity insurance quote that addresses your unique needs today.
Securing Your Practice with Just Quote Me: Expert Advice for Consultants
Just Quote Me has spent over 30 years helping advisors navigate the complexities of the UK insurance market. As an independent, FCA-authorised broker based in Stone, Staffordshire, we provide a human-centric alternative to faceless automated systems. We understand that your expertise is your business. That’s why we access a broad network of top UK insurers to source professional indemnity insurance for consultants that actually reflects your daily operations. We don’t just sell policies; we provide a steady hand to manage your administrative burdens. This allows you to focus on your clients while we handle the technical details of your professional indemnity insurance.
Our process is designed for maximum efficiency. We do the heavy lifting of comparing the market, ensuring you get bespoke cover without the stress of manual searching. In 2026, speed is essential for satisfying client contracts. We provide proof of insurance quickly, helping you clear compliance hurdles and start work on new projects without delay. By speaking directly to a human expert at our Stone headquarters, you get the benefit of regional expertise and professional restraint that larger, impersonal firms can’t offer. We pride ourselves on being accessible, meaning you can reach a specialist who knows the West Midlands business landscape inside out.
How to Get Your Quote Today
- Step 1: Gather your business details, including your projected annual turnover and any specific indemnity limits required by your current contracts.
- Step 2: Visit our online portal for a fast, free quote that matches your sector-specific risks.
- Step 3: Consult with our experts if you have unique or high-risk requirements that need a more tailored approach than a standard policy offers.
Ready to Protect Your Consulting Business?
Securing your practice with the right professional indemnity insurance for consultants provides more than just a certificate; it gives you the peace of mind that your personal assets and professional reputation are protected. We remain committed to providing straightforward, pragmatic advice that simplifies the insurance process. Whether you’re a management consultant in Stafford or an IT advisor in the West Midlands, we’re here to ensure your practice is resilient against claims of negligence or error. Our focus on individualized service and specialist knowledge ensures you’re never just another number in our system.
Get Your Free Business Insurance Quote now
Request a Call back for free Expert advice
Secure the Future of Your Consulting Practice
Your expertise drives your business; don’t let a single disputed piece of advice put your assets at risk. This guide has shown that the 2026 UK market demands more than just basic compliance. You need a policy that accounts for the nuances of your specific niche and the “claims-made” nature of the industry. Choosing the right professional indemnity insurance for consultants is about finding a partner who understands your duty of care. With over 30 years of industry experience, Just Quote Me provides the human-centric expertise you need to navigate this complex market.
As an FCA-authorised independent broker, we access a broad network of top UK insurers to find bespoke solutions that direct platforms simply can’t offer. We handle the administrative burden so you can focus on delivering value to your clients. Whether you’re satisfying a new contract or reviewing existing cover, our team is ready to help. Protecting your livelihood is straightforward when you have a steady hand to guide you. For professional advice tailored to your practice, Just Quote Me.
Get Your Free Business Insurance Quote now
Request a Call back for free Expert advice
Frequently Asked Questions
Is professional indemnity insurance a legal requirement for consultants in the UK?
It isn’t a universal legal mandate for all consultants, but it’s a regulatory requirement for specific professions such as solicitors, architects, and accountants. For most other advisors, it’s a practical and contractual necessity. Most corporate clients in 2026 won’t allow you to begin work without proof of cover. Even if not required by law, it’s the only way to protect yourself from the costs of negligence claims.
What is the difference between professional indemnity and public liability insurance?
Professional indemnity covers financial losses caused by your expert advice, whereas public liability protects against physical injury or property damage. If you provide a strategy that leads to a client’s financial loss, your indemnity policy responds. If a client trips over your equipment during a meeting, public liability applies. Most consultants need both to ensure they’re fully protected against the different risks they face during their daily operations.
How much does professional indemnity insurance for consultants cost?
The cost of professional indemnity insurance for consultants depends on several factors, including your industry sector, annual turnover, and the level of cover required. High-risk fields like financial services or engineering usually attract higher premiums than general administrative consulting. Your claims history and the complexity of your contracts also play a role. To get an accurate price for your specific practice, it’s best to request a bespoke quote from a specialist broker.
What is “claims-made” insurance and why does it matter for my policy?
Claims-made means the policy in force at the time a claim is reported is the one that handles the case, regardless of when the work was done. This is vital for consultants because a client might not discover a mistake in your advice until years later. You must maintain continuous cover to ensure you’re protected. If you cancel your policy or have a gap in cover, you lose protection for all your previous projects.
Do I need professional indemnity insurance if I am a sole trader?
Yes, sole traders definitely need professional indemnity insurance for consultants because there’s no legal separation between your business and personal assets. If a client sues you for a professional error, your personal savings and property could be at risk to cover legal fees and settlements. A robust policy ensures that the insurer manages these costs, protecting your livelihood and your personal financial stability from the impact of a claim.
What happens if I retire? Do I still need insurance for past consulting work?
You should maintain “run-off” cover for at least six years after you retire or stop trading. Since professional indemnity is a claims-made policy, you need an active policy to handle any claims that arise from work you did in the past. UK law allows clients to bring negligence claims long after a project has finished. Run-off cover provides peace of mind that your historical liabilities remain protected throughout your retirement.
Can I get professional indemnity insurance for a single project?
While it’s possible to find cover for a specific assignment, an annual policy is usually more cost-effective and provides more consistent protection. Single project insurance can be more difficult to arrange and often carries higher relative costs. Most consultants find that an annual policy, which can be updated as their client list grows, offers better value and ensures they aren’t left with dangerous gaps in their coverage between different project start dates.
Will my PI insurance cover me for work I do for international clients?
Most UK policies provide worldwide cover, but there are often specific exclusions or higher premiums for work involving the USA or Canada. You must check the “territorial limits” and “jurisdiction” clauses in your policy documents. Always disclose the location of your clients to your broker during the quote process. This ensures your policy is tailored to cover the specific legal systems and regions where your advice is being delivered.
