A soft insurance market doesn’t guarantee a cheaper hospitality renewal. It may create more opportunity to secure competitive terms, but the outcome still depends on your business’s needs and the risks insurers assess. A hospitality insurance broker in Newcastle-under-Lyme can help you understand the policy options and terms.
It’s reasonable to look for savings when the market softens, but price is only part of the decision. The cover should reflect your operation, whether you run a pub, restaurant, hotel or another hospitality business.
This article explains how market conditions may affect premiums, what can shape cover and cost, and how a local broker can help. It also outlines what to consider when arranging or reviewing hospitality insurance, so you can make an informed decision.
Key Takeaways
- A soft insurance market may create opportunities for competitive terms, but your business’s risks and cover needs still shape the renewal.
- Tailor protection to your hospitality operation, considering liabilities and potential interruption to income.
- Buildings, contents, machinery and stock may all need consideration when arranging commercial cover.
- Local broker support can help you understand suitable options, including Public Liability Insurance and Employers Liability Insurance.
Tailored insurance programmes for hospitality businesses
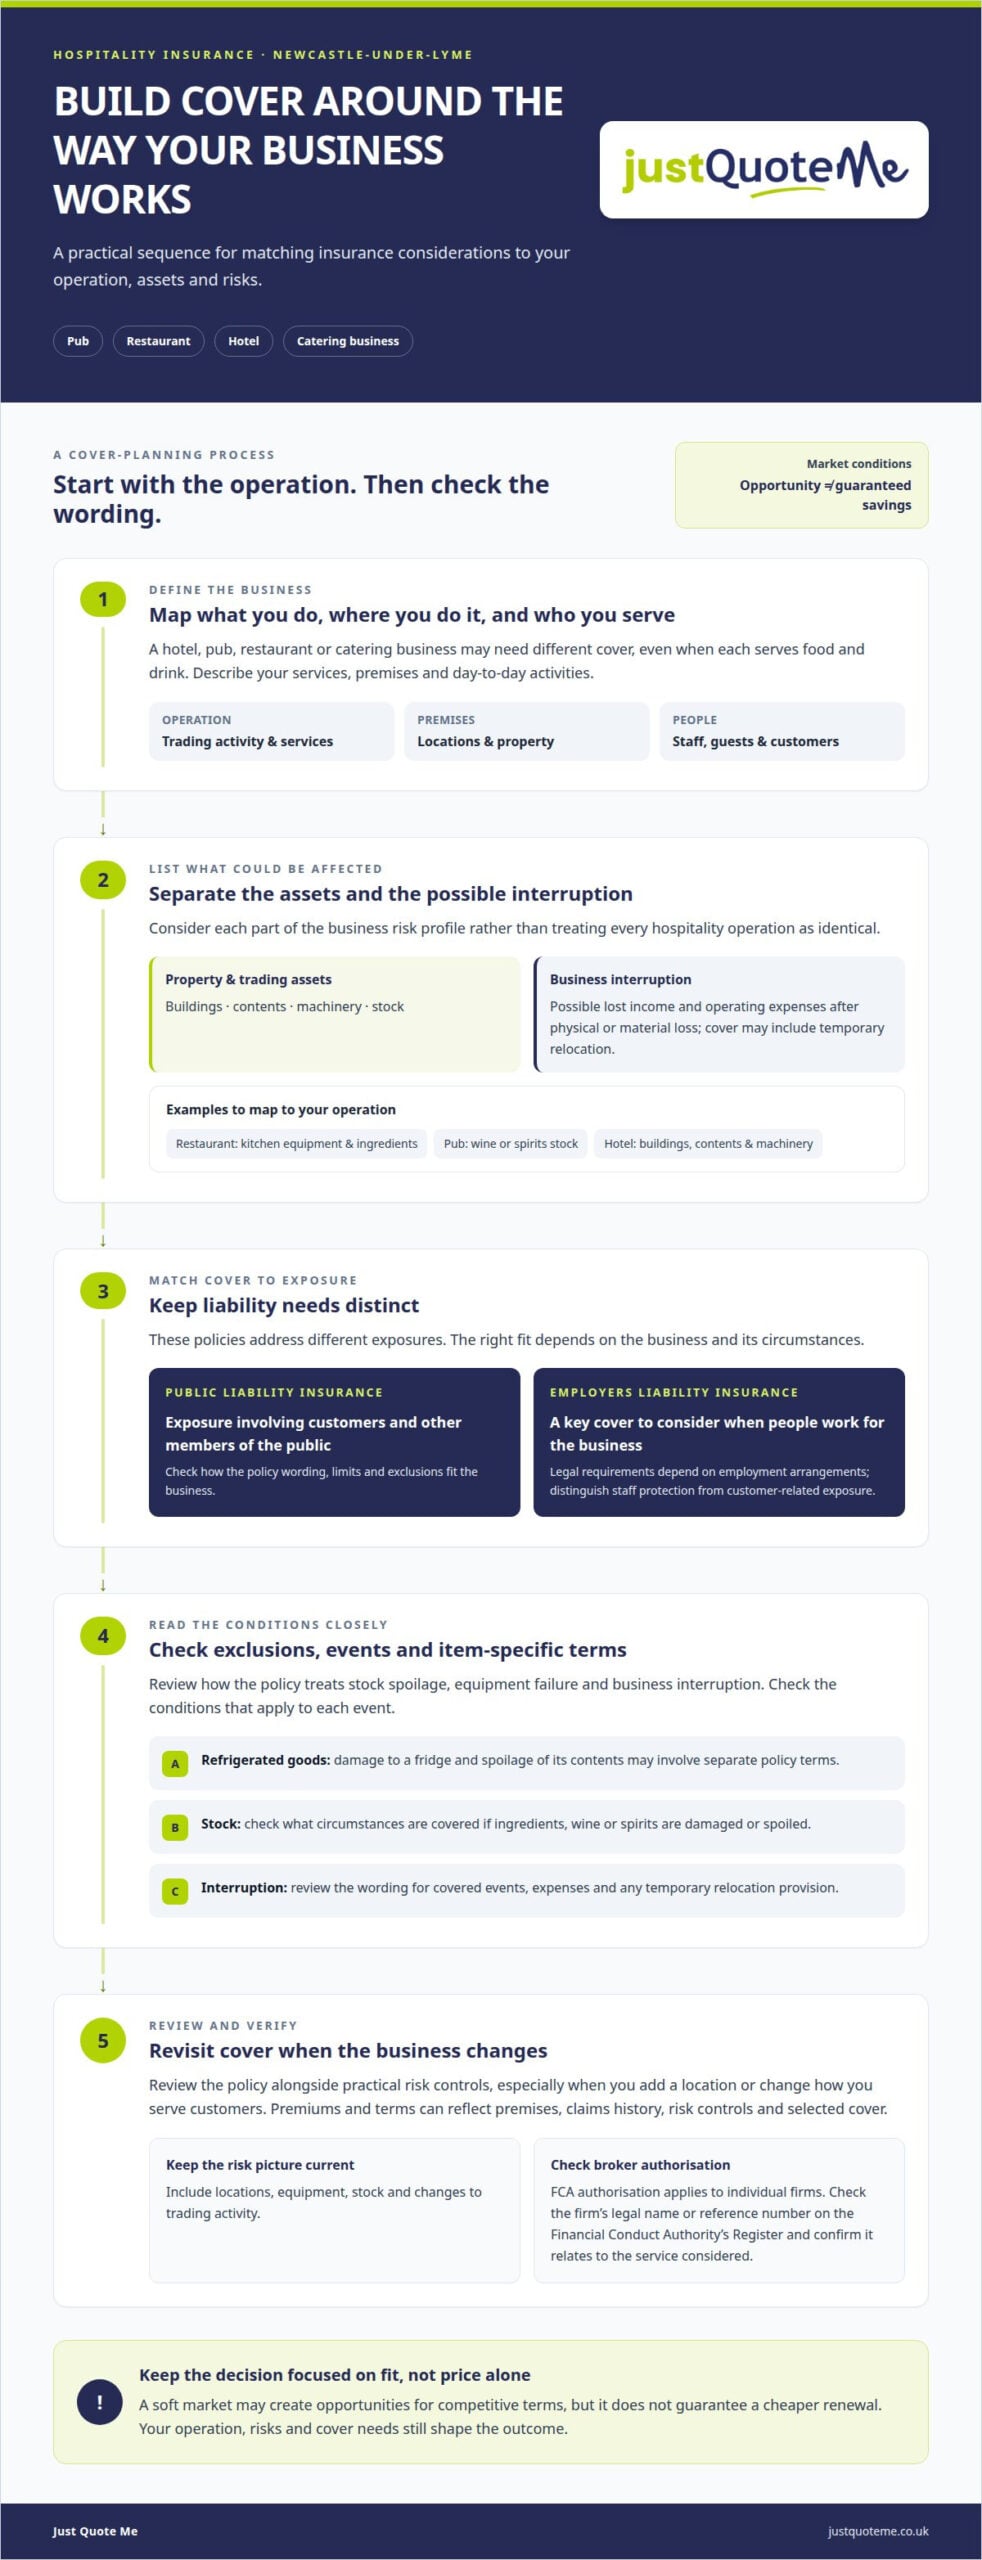
A suitable insurance programme starts with your operation, premises and the risks involved in serving guests or handling food. A hotel, pub, restaurant or catering business may need different cover, even if each serves food and drink.
Required cover and policy exclusions
For UK hospitality businesses, employers’ liability is the key cover to consider when people work for the business, while public liability addresses a different exposure. Legal requirements depend on employment arrangements, so distinguish cover for staff from protection against claims involving customers. Review exclusions relating to stock spoilage, equipment failure and business interruption, and check the conditions that apply to each event.
Business interruption cover may help with lost income and operating expenses after physical or material loss, and may include temporary relocation. For a restaurant or caterer, spoiled ingredients can create a separate financial concern, so check how the policy treats stock loss and which circumstances are covered. A pub or hotel should also consider buildings, contents, machinery and stock as distinct parts of its risk profile.
Broker options and liability cover
Choose a Newcastle-under-Lyme broker with experience arranging cover for hospitality operations, rather than relying on a policy designed for a different trade. Public Liability Insurance and Employers Liability Insurance address different exposures; a broker can help establish which risks each policy responds to and how limits and exclusions fit the business. No named local broker is identified here.
For UK hospitality businesses, cover should reflect the services provided and the risks involving customers, suppliers and day-to-day operations. Risk management can also help identify practical measures for staff safety, theft and business interruption. Review your policy alongside those measures, especially when you add a location or change how you serve customers.
Commercial insurance brokers near Newcastle-under-Lyme
A commercial broker can help shape cover around your premises, stock and trading activity. A hotel may need buildings, contents and machinery considered separately, while a restaurant’s commercial kitchen creates distinct equipment and stock exposures. A pub holding wine or spirits should consider how its stock is treated, including the terms that apply if goods are damaged or spoiled. Your broker should explain these distinctions clearly, rather than treating every business as identical.
FCA authorisation applies to individual firms, not to every broker in Newcastle-under-Lyme. You can check a firm’s status by searching its legal name or reference number on the Financial Conduct Authority’s Register, then confirming the result relates to the service you’re considering.
Commercial cover extends beyond hospitality. A shop has different property, stock and customer risks from a bar, so its policy should reflect its actual activities and premises. If you have both a home and a trading location, personal and commercial insurance address different needs and are not interchangeable. Before discussing cover, make a clear list of locations, equipment and stock.
Ask how the proposed wording treats kitchen equipment, refrigerated goods and wine stock, and whether exclusions or conditions affect those items. For example, damage to a fridge and spoilage of its contents may involve separate policy terms. A broker can explain the relevant sections and identify where cover needs to match the business’s operations. For advice about commercial and personal insurance options, speak with an insurance broker about the risks you need to address.
Personal service from a local agency
A conversation with a broker can help connect business decisions with your personal circumstances. For example, a pub director may want to discuss how an injury could affect daily operations, while keeping personal protection separate from the business policy. Clear advice should explain which policy applies to each situation, rather than treating every concern as one insurance need.
Personal accident cover is different from liability insurance. An individual may consider it for financial support following an injury caused by an accident, but its scope depends on the policy wording. Check the events covered, exclusions, benefit terms and definition of an eligible injury. Don’t assume this cover protects staff, customers or business income.
Personal insurance also serves a different purpose from commercial cover. A restaurant owner’s home and household belongings face different risks from the restaurant’s premises, kitchen equipment and stock. Discuss each requirement separately, and make sure the information used for a quote reflects the right person, property and activity. This helps keep business and personal arrangements clear.
Claims support is another practical part of a broker’s service. If a burst pipe damages a guest house, the owner may need to explain the damage, affected rooms and resulting interruption. Keep relevant records together, such as photographs, repair details and evidence of how the business was affected. A broker can help clarify the claims process and liaise with insurers, while the policy wording determines what the cover responds to. Ask who will handle updates and what information is needed at each stage, so responsibilities are clear during a stressful event.
Local insurance brokerage in Newcastle-under-Lyme
For a hospitality business in Newcastle-under-Lyme, useful brokerage means advice shaped around the operation, not just its postcode. A town-centre café, a pub with rooms and a guest house face different property, customer and trading exposures. Start by mapping each activity, premises and key asset to the cover you’re considering.
A soft market may make insurers more willing to consider particular risks, but it doesn’t automatically make every business cheaper to insure. Premiums and terms still reflect factors such as premises, claims history, risk controls and selected cover. For example, a restaurant with updated fire precautions presents a different risk picture from one with unresolved maintenance issues. A broker can explain how these details shape the options.
Use a simple renewal process. First, outline changes since the last policy, such as new rooms, extended opening or added equipment. Next, identify the value and use of buildings, contents, machinery and stock. Then discuss exclusions, conditions, excesses and how a claim would be handled. This gives your broker a clearer picture and helps you understand what the policy does and doesn’t address.
Local support can also make policy discussions more practical: a broker can explain unfamiliar wording using examples from a hotel, bar or catering operation. That clarity can bring peace of mind, provided the chosen cover matches the risks and the policy terms. To discuss the details of your hospitality operation and possible cover, request insurance support.
Just Quote Me
Just Quote Me helps hospitality operators review their business risks and insurance options. When your renewal approaches, you open a venue, change services or add premises, a broker can assess how those changes affect your cover. Just Quote Me can explain policy terms and help identify suitable options through access to a broad network of UK insurers.
A soft insurance market can create room for competitive terms, but price alone doesn’t show whether a policy fits. Just Quote Me can help you consider relevant exposures, including Public Liability Insurance and Employers Liability Insurance. For a hospitality business serving guests or employing staff, the discussion should distinguish customer-facing risks from employment-related responsibilities.
To make a review useful, provide a concise account of your activities, premises, staffing arrangements and recent changes. A restaurant adding takeaway service, for example, may need its business description and policy details reviewed. Your broker can explain relevant limits, exclusions and conditions, and outline how Professional Indemnity Insurance or Landlord Insurance may relate to particular responsibilities. This keeps the discussion focused on your circumstances rather than generic policy labels.
If you already have cover, your policy schedule and renewal information can help frame the discussion. Just Quote Me can explain how options relate to your hospitality business and what details affect the arrangement, without presenting a softer market as a promise of a lower premium. This can be useful when circumstances have changed or policy wording feels unclear.
For a straightforward discussion, contact Just Quote Me.
Make your next renewal a clear decision
Use your next renewal to align your policy with how your hospitality business operates now. A hospitality insurance broker in Newcastle-under-Lyme can help you discuss changes, understand relevant terms and consider whether the cover still fits your priorities. The value of a soft market lies in reviewing the details, not assuming every renewal will cost less.
Just Quote Me offers Public Liability Insurance, Employers Liability Insurance and Professional Indemnity Insurance. These policies address different business exposures, and a broker can explain how they relate to your circumstances. Start with your operation, the risks you want to address and the applicable policy wording.
You don’t need to make a sales decision before you understand your options. A practical conversation can help identify what to discuss at renewal and what information would clarify the cover. Get Your Free Business Insurance Quote now, or Request a Call back for free Expert advice from Just Quote Me.
Frequently Asked Questions
What hospitality insurance cover do pubs, restaurants, cafés and hotels need in the UK?
Cover depends on your business’s activities, premises and staffing arrangements. Employers’ liability is the policy to discuss when employees work for the business, while public liability addresses claims involving third parties. A café serving takeaway food may also need to consider product-related exposures. For a hotel, the discussion may include guest areas and property. A broker can map each risk to the relevant policy and clarify legal requirements for your circumstances.
How much does hospitality business insurance cost in Newcastle-under-Lyme?
The cost depends on your business and is provided after a quote request. Factors include the type of venue, its activities and premises, the cover selected, claims history and risk controls. A café with limited seating has a different profile from a hotel with guest rooms and a bar. A soft market may influence insurers’ appetite, but it doesn’t establish a standard premium or guarantee a lower renewal.
How can I compare quotes from hospitality insurance brokers in Newcastle-under-Lyme?
Compare the cover, not just the headline premium. For each quote, review insured activities, policy limits, excesses, exclusions and conditions, then check that the same business details appear throughout. For example, a quote should reflect both restaurant dining and takeaway operations if both apply. A hospitality insurance broker in Newcastle-under-Lyme can explain differences in wording and help you understand what each option covers.
Does hospitality insurance cover food poisoning, customer injury and property damage?
These incidents may involve different sections of a policy, and cover depends on the wording and circumstances. A customer injury claim may relate to public liability, while a food poisoning allegation could involve product liability. Damage to business property is a separate consideration. Report incidents promptly in line with the policy’s claims process and keep relevant records, such as incident details, correspondence and receipts.
What cover is available for business interruption, equipment breakdown and stock spoilage?
Business interruption cover may help with lost income and operating expenses after physical or material loss. Cover for equipment breakdown and spoiled stock depends on the policy’s insured events, exclusions and conditions. For example, refrigeration failure may affect stock, but the wording determines whether that cause of loss is covered. Ask how each section responds and whether interruption cover requires damage to insured property first.
How do I get a hospitality insurance quote from a Newcastle-under-Lyme broker?
Prepare details of your trading activities, premises, staffing, claims history and the cover you need. Include changes such as new services or alterations to the venue, so the quote reflects your current operations. Just Quote Me provides free, no-obligation insurance quotes. Get Your Free Business Insurance Quote now, or Request a Call back for free Expert advice.
